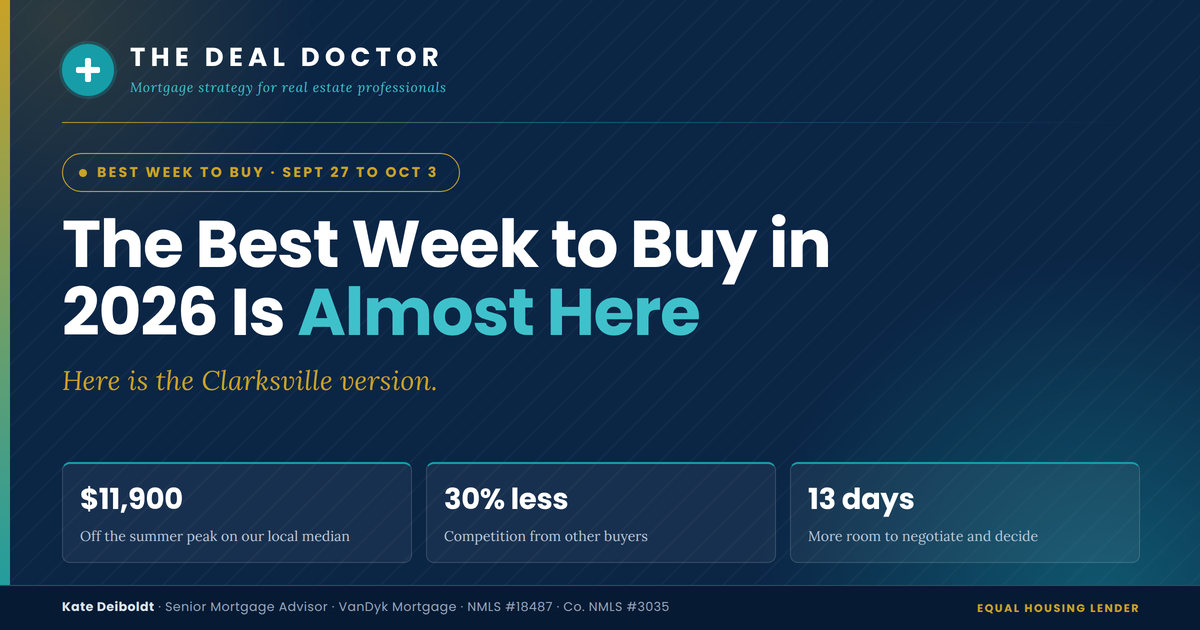
Over the next two weeks you are going to see the same headline everywhere: the best week to buy a home in 2026 is almost here. It is a real finding from real data. It is also about to get repeated by a lot of people who never read past the first paragraph. https://katedeiboldt.vandyk-pos.com/portal
So let us do what we always do here. Look at the actual numbers, figure out which ones matter in Clarksville, and turn it into something you can use this week.
This one is written for two readers. If you are buying a home, the first half is yours. If you are a Realtor or a loan officer, keep going. The second half is where the leverage is.
What the Research Actually Says
Realtor.com scores every week of the year using six supply and demand measures: listing prices, inventory levels, fresh listings, time on market, buyer demand, and price reductions. They used 2018 through 2025 data and deliberately left interest rates out, because rates do not move on a seasonal schedule. The week that scores highest becomes the national Best Week to Buy.
For 2026, that week is September 27 through October 3. Here is what buyers in that window can expect nationally, according to Realtor.com’s report:
| What shifts | The national number |
|---|---|
| Prices below the summer peak | About 3.5%, roughly $14,000 on a median listing near $416,000 |
| Competition from other buyers | 30.1% lower than the annual peak, measured by listing views per property |
| Time on market | About 13 days longer, near 64 days |
| Active listings vs. the start of 2026 | 31.9% more |
| Active listings vs. an average week | 13.3% more |
The supply side checks out independently. In the National Association of Realtors August report, total inventory hit 1.62 million units and months of supply reached 4.9. Lawrence Yun called that “its highest level in over ten years” and said the ample supply “is giving homebuyers better opportunities to negotiate.”
That last word is the one to circle. Negotiate. Not save. We will come back to that.
One Thing the Headline Gets Wrong
You are going to read that 42 of the 50 largest metros have their best week sometime in October. That is a small but meaningful distortion of the finding.
What Realtor.com actually reported is that 42 of the 50 largest metros have a best week within a month of the national window. That is a wider net, and it runs in both directions. New York and Milwaukee already passed their peak in early September. Miami and Tampa do not hit theirs until November 29 through December 5. Only 14 metros line up exactly with the national week.
It matters because a buyer who hears “October is the month” and lives in the wrong market will either rush or wait, and both are expensive. Local timing beats national timing every time.
So When Is Our Window?
Clarksville is not one of the 50 largest metros, so there is no published best week for us. The closest large metro is Nashville, which peaks October 4 through October 10. Memphis is earlier, September 20 through 26. Louisville is much later, November 1 through 7.
Rather than borrow Nashville’s calendar, look at what the Clarksville, TN-KY market is actually doing. These come from the Federal Reserve Bank of St. Louis, which publishes the Realtor.com metrics by market:
| Clarksville, TN-KY | Reading |
|---|---|
| Median listing price, August 2026 | $339,900, down from $344,950 in July |
| Active listings, July 2026 | 2,076, up from 1,712 in March |
| Median days on market, August 2026 | 60 days |
| National median days on market, August 2026 | 60 days |
Three things stand out.
Inventory here has climbed by about 21% since March. Listing prices have started to ease off the summer number. And homes are sitting for 60 days, which is exactly the national pace, not faster and not slower. That last one surprises people who assume a military market always moves quicker.
Translation: the same seasonal softening the national report describes is showing up in our numbers. We just do not have a headline announcing it.
Now the Part Nobody Puts in the Headline
Let us apply that 3.5% seasonal easing to our median listing price of $339,900. That is about $11,900 off the summer number.
Real money. So what does it do to the payment?
Freddie Mac’s survey put the 30-year fixed average at 6.76% on September 10, 2026. At that rate, principal and interest run about $6.49 per $1,000 borrowed over 30 years. On a VA loan at full financing, $11,900 less financed works out to roughly:
$11,900 ÷ 1,000 × $6.49 = about $77 per month
Illustration only, using a published survey average. Not a rate quote, not an approval, and principal and interest are not the whole payment.
Seventy-seven dollars. That is the honest answer, and it is worth having. But if anyone tells you the fall window is going to solve an affordability problem, that number is your reality check.
The Real Prize Is the Other Two Numbers
Go back to the table. Competition down 30%. Homes sitting 13 days longer.
Those are not price statistics. Those are leverage statistics, and leverage is worth far more than $77 a month.
When a seller has watched a listing sit for 60 days and the showing traffic has thinned out, the conversation changes. You can ask for things that were unthinkable in June:
- An inspection contingency that does not get waived to win.
- Repairs actually completed before closing instead of credited away.
- A seller contribution toward closing costs and prepaids.
- A seller contribution structured to fund an eligible rate buydown.
- Time to read documents instead of signing under a deadline someone else set.
Look at that fourth one again. A seller credit aimed at a buydown can move a payment several hundred dollars in the early years. That is the difference between a $77 conversation and a real one.
Seller contributions are capped by loan program, occupancy, loan-to-value, and actual eligible costs. Fannie Mae’s Interested Party Contributions guidance and HUD’s seller contribution answer set very different limits. Confirm the specific structure with your lender before it goes in the contract, not after.
Buyers: What To Do Between Now and October
Here is the trap in every best week story. The window rewards buyers who are already ready. It does nothing for buyers who start getting ready when the window opens.
- Get fully underwritten, not prequalified. A prequalification is an opinion. Underwritten credit approval is a position you can negotiate from when the seller has three offers on the table. https://katedeiboldt.vandyk-pos.com/portal
- Know your total payment, not your principal and interest. Taxes, homeowners insurance, flood insurance if applicable, HOA dues, and mortgage insurance where it applies. Ask for the whole number.
- If you are VA eligible, pull your Certificate of Eligibility now. Entitlement questions, prior use, and restoration take time to sort out. Find out in September, not during a 10-day contingency. https://katedeiboldt.vandyk-pos.com/portal
- Ask about Tennessee Housing Development Agency programs. Down payment assistance has income and purchase price limits that change. Worth a 15-minute conversation before you assume you do not qualify.
- Shop the mortgage, not just the house. Sam Khater at Freddie Mac said it plainly in that same release: getting preapproved early “can potentially save them thousands.” https://katedeiboldt.vandyk-pos.com/portal
- Decide what leverage you want before you find the house. Inspection, repairs, credit toward a buydown, closing date. Emotion is a terrible negotiator.
Realtors and Loan Officers: How To Use This
Your competition is going to share the national article to social media with a one-line caption and call it content. You can do something better in the same ten minutes.
With buyers who have been sitting on the fence
Do not lead with the $14,000. It is a national figure on a national median, and a buyer who later learns our median is $339,900 will feel sold to. Lead with the honest local version.
“There is a seasonal window opening in the next few weeks. In our market that probably looks like a listing price a few percent off the summer number, about a third less competition, and sellers who have been waiting 60 days and are ready to talk. The price part is maybe $77 a month. The negotiating part is worth a lot more. Let us get you underwritten so you can actually use it.”
That is a conversation that builds trust. The $14,000 headline builds a follow-up problem.
With sellers who are still priced for June
This is the harder call and the more valuable one. Your seller is competing against 2,076 active listings in a market that added roughly 364 of them since March. Buyer attention nationally falls about 30% off the peak. A price set in June is now a price set for a market that no longer exists.
The best window for buyers is, by definition, the tighter window for sellers. Say it out loud before they figure it out from their showing log.
The three scenarios to request from your lender
https://katedeiboldt.vandyk-pos.com/portal
Before anyone reduces a price by reflex, ask for a same-day comparison on the same buyer profile:
“Can you run three options for us: the current price, a $10,000 price reduction, and a $10,000 seller credit applied to the most useful eligible strategy for this borrower? Show me total cash to close, year-one payment, permanent payment, and any break-even point.”
Nine times out of ten the credit moves the payment further than the reduction does. Do not spend $10,000 to solve a $77 problem.
One content idea worth more than a reshare
Pull your own numbers for your zip code or your subdivision. Days on market, active listings, price reductions in the last 30 days. Then post the local version of this story with your name on the analysis. The national article is a commodity. Your market read is not.
The company that owns the first click often owns the closing.
The Bottom Line
The best week to buy is real. It is just smaller than the headline and bigger than the skeptics think, and both of those things are true at once.
Smaller, because a few percent off a listing price is about $77 a month here, and no seasonal window is going to outrun a 6.76% rate environment on its own.
Bigger, because 30% less competition and two extra weeks of patience give a prepared buyer something the spring market never offers: room to ask for what they actually need. Inspections. Repairs. A credit structured to move the payment. Time to think.
Rates change. Inventory changes. The calendar comes back around every year. What does not change is that the prepared buyer wins the negotiation and the unprepared buyer watches the window pass.
You have about two weeks. Get underwritten. Decide what you want to negotiate for. Then go use the window instead of reading about it.
Knowledge is power.
Leave a Reply