• Top 5 Mistakes First-Time VA Homebuyers Make When Shopping for a Home

    Top 5 Mistakes First-Time VA Homebuyers Make When Shopping for a Home

    You’ve earned your VA home loan benefit. After years of service, late nights away from family, and more moves than most people make in a lifetime, you finally have a real shot at owning a home — often with zero down payment. But somewhere between “I’m ready to buy” and “let’s close this deal,” a lot of first-time VA homebuyers in Clarksville, TN and the Fort Campbell area make a handful of costly mistakes that can slow everything down, shrink their purchasing power, or cost them the home they wanted.

    The good news? Every single one of these mistakes is completely avoidable. I’ve spent over 25 years helping military families navigate the homebuying process right here in Middle Tennessee and Southern Kentucky, and I see the same patterns come up time and time again. Think of this like Google Maps for mortgages — I’m going to show you exactly where the wrong turns are, so you can skip straight to the destination.

    Mistake #1: Shopping for Homes Before Getting Pre-Approved

    This is the big one. A lot of first-time VA homebuyers in the Clarksville and Fort Campbell area start browsing homes on Zillow, falling in love with floor plans, and even scheduling showings — all before they’ve talked to a lender. And I totally get it. Looking at homes is exciting. Talking to a mortgage lender feels like homework.

    But here’s the problem: without a pre-approval, you don’t actually know what you can afford. You might spend weeks touring homes that are over your budget, or worse — find your dream home, make an offer, and lose it to another buyer who had their pre-approval letter in hand.

    In today’s market, especially around Fort Campbell where military buyers are often competing with one another during PCS season, sellers want to see a strong pre-approval before they’ll even entertain your offer. Getting pre-approved first puts you in the driver’s seat. It only takes a few hours — sometimes less — and it costs you nothing.

    Mistake #2: Not Understanding the VA Funding Fee

    VA loans are an incredible benefit. Zero down payment, no private mortgage insurance, and flexible credit guidelines. But there is one cost that catches first-time VA homebuyers off guard: the VA funding fee.

    The funding fee is a one-time cost charged by the VA that helps keep the program running for future service members. For most first-time VA homebuyers using zero down, that fee is 2.15% of the loan amount. On a $300,000 home, that’s $6,450.

    The good news is the funding fee can be rolled into the loan — you don’t have to pay it out of pocket at closing. And some veterans are exempt entirely, including those receiving VA disability compensation.

    The mistake I see most often is buyers who don’t know this fee exists until the closing disclosure lands in their inbox. Understanding it upfront means no surprises — and sometimes it changes the strategy for how we structure the loan. There is no such thing as a dumb mortgage question, and this is one worth asking about early.

    Mistake #3: Opening New Credit or Making Large Purchases During the Process

    You got pre-approved — congratulations! Now is absolutely not the time to finance a new truck, open a credit card at the furniture store, or co-sign on anything for a family member.

    I know this sounds obvious, but it happens more than you’d think. The excitement of buying a new home makes people want to start filling it. A new washer and dryer on a store credit card, a big purchase at the PX — these things can change your debt-to-income ratio and potentially derail your loan just days before closing.

    After you’re pre-approved, keep your finances exactly as they are. No new debt. No large cash deposits without documentation. No job changes if you can avoid them. Your lender will pull your credit again right before closing — and what they find has to match what they originally approved.

    Mistake #4: Assuming Every Lender Knows VA Loans

    VA loans are not like conventional loans. They have their own appraisal standards (called Minimum Property Requirements), their own timeline considerations, their own documentation requirements — and they require a lender who actually knows what they’re doing.

    Not every lender in the Clarksville or Hopkinsville area handles VA loans regularly. Some accept VA loans but process very few of them, which means longer timelines, more back-and-forth, and a higher chance of hitting avoidable roadblocks.

    When you’re a Fort Campbell military family on a PCS timeline, you don’t have time for a lender who has to look up the answer to your questions. You need someone who has closed hundreds of VA loans — including ones involving deployment, Power of Attorney, BAH calculations, and tight move-in deadlines.

    Ask your lender: How many VA loans did you close last year? What’s your typical VA closing timeline? Do you offer any fee waivers for VA buyers? The answers will tell you everything you need to know.

    Mistake #5: Letting Online Calculators Set Your Budget

    Online mortgage calculators are a great starting point. But they almost always leave out the things that matter most — property taxes, homeowner’s insurance, HOA fees (if applicable), and the VA funding fee. What looks like an affordable $1,400/month payment online might actually be closer to $1,750/month once all the real numbers are included.

    I’ve seen buyers in the Clarksville area experience real payment shock once the full picture comes together. That’s a stressful place to be — especially when you’re navigating a military move and trying to make a decision quickly.

    A real pre-approval conversation with an experienced VA lender gives you actual numbers: your real monthly payment, your real closing costs, and a clear picture of what homeownership will actually look like for your family. Let’s see what’s actually possible — and make sure the number makes sense before you fall in love with a house.

    Frequently Asked Questions

    Do I need a down payment for a VA loan in Clarksville, TN?

    No — eligible VA borrowers can purchase a home with zero down payment. This is one of the most powerful benefits of the VA loan program and one of the few true zero-down options available to buyers in the Clarksville and Fort Campbell area.

    What credit score do I need for a VA loan?

    The VA itself doesn’t set a minimum credit score, but most lenders look for a score of 580 or higher. Every situation is different, and there are strategies to improve your score quickly if you’re not quite there yet. Don’t assume you don’t qualify until you’ve had a real conversation — even if you’ve been told no before.

    How long does the VA loan process take near Fort Campbell?

    With an experienced VA lender, most VA loans close in 2–4 weeks from contract to closing. The biggest variable is the VA appraisal, which can take 1–3 weeks depending on appraiser availability in the Clarksville area. Getting your documents in early and working with a lender who knows VA timelines makes a significant difference.

    Can I use my VA loan if I’m currently deployed?

    Yes, absolutely. We handle VA loans for deployed service members regularly. In most cases, a spouse or authorized representative can sign documents using a Power of Attorney. This is something we navigate all the time for Fort Campbell families — it doesn’t have to slow things down.

    Are there fees I should know about as a first-time VA homebuyer?

    VA loans eliminate the need for private mortgage insurance (PMI), which is a significant savings. The main cost to plan for is the VA funding fee (typically 2.15% for first-time use with zero down), which can be rolled into the loan. Some veterans with service-connected disabilities are exempt. Our team charges no underwriting or processing fees for VA homebuyers, keeping your costs as low as possible.

    Your VA home loan benefit is one of the most powerful tools you’ll ever have access to. The key is knowing how to use it — and having someone in your corner who has done this hundreds of times, right here in Clarksville, TN and the Fort Campbell community.

    If you’re a first-time VA homebuyer and want to walk through your options, I’m here. Text me at (931) 980-9764 — there is no such thing as a dumb mortgage question, and your clear path home starts with a single conversation.

    Kate Deiboldt | NMLS #18487 | VanDyk Mortgage Corporation | Licensed in TN, KY, FL, GA, AL, TX

  • How Self-Employed Borrowers Get Approved for a Mortgage

    How Self-Employed Borrowers Get Approved for a Mortgage

    If you’re self-employed, you can get a mortgage — approval is mainly about documenting stable income and clean business finances. In Clarksville and across Middle Tennessee, the hurdle isn’t your job; it’s proving income in a way an underwriter can verify.

    TL;DR — Key takeaways

    • Most self-employed buyers need two years of tax returns (personal + business) to document income.
    • Cash flow matters more than revenue — write-offs can lower the income you can use for qualifying.
    • Keep business and personal funds separate; clean statements make underwriting faster.
    • A profit-and-loss statement is not optional for many loan types; it’s often required near closing.
    • Get pre-approved early so you can shop confidently for homes in Clarksville, Nashville, and Montgomery County.

    Self-employed income is income you earn from your own business or contract work rather than a W-2 paycheck. Qualifying income is the underwriter-verified amount used to approve your mortgage, based on your documented earnings after certain adjustments. Debt-to-income ratio is the comparison of your monthly debts to your monthly qualifying income.

    Here’s what lenders look for — and how to prepare if you’re a 1099 contractor or business owner buying near Fort Campbell.

    1) The big rule: expect two years of history

    For most conventional, FHA, VA, and USDA loans, lenders want a two-year history of self-employment or contract work. That doesn’t always mean your business must be two years old, but it usually means you need enough documented history to show stability. If you recently became self-employed in Clarksville, you may still qualify if you stayed in the same line of work and can document continuity.

    2) What “income” actually means for a self-employed borrower

    When you’re self-employed, underwriting doesn’t use your gross deposits. Instead, it typically starts with your taxable income from your personal return and/or business return, then adds back certain allowable non-cash expenses (like depreciation) while subtracting other items that reduce usable cash flow.

    That’s why a business can look “successful” in real life but show lower qualifying income on paper after write-offs. Write-offs are great for taxes, but they can reduce the income that counts for a mortgage.

    3) Documents you’ll almost always need

    For many Clarksville and Montgomery County loan files, plan on:

    • Two years of personal federal tax returns (all schedules)
    • Two years of business returns (if you file one: Schedule C, 1065, 1120S, or 1120)
    • Year-to-date profit & loss (P&L) (and sometimes a balance sheet)
    • Bank statements (personal and business)

    Underwriting is a documentation process. Cleaner paperwork usually means fewer last-minute conditions.

    4) A simple checklist to boost your approval odds in 60–90 days

    If you’re planning to buy a home in Clarksville TN this season, here’s a short preparation list that makes a big difference:

    1. Separate accounts: keep business income/expenses in business accounts and personal spending in personal accounts.
    2. Stabilize deposits: avoid big unexplained cash deposits; document transfers clearly.
    3. Don’t take on new debt: vehicles, cards, and equipment loans can increase your DTI fast.
    4. Keep tax filing current: extensions can be workable, but missing returns are a hard stop.
    5. Plan your write-offs: if you’re close to buying, talk with your tax pro about balancing deductions and mortgage goals.

    5) Common speed bumps (and how we solve them)

    Inconsistent income can reduce what you qualify for, because lenders may average income and limit it if the most recent year is lower.

    Mixed business and personal finances can slow underwriting. Separate statements make the story clearer.

    New business or new industry may require extra documentation. If you’re relocating to Fort Campbell, [INTERNAL LINK: mortgage pre-approval process] helps you plan the timing.

    6) Loan options that can work well for self-employed buyers

    Many self-employed borrowers assume they need a special “bank statement loan.” Sometimes that’s true — but many buyers in Montgomery County qualify with standard programs if their documented income supports it.

    • Conventional loans: can be a great fit with strong credit and stable income documentation.
    • FHA loans: flexible for credit and down payment, but still document-heavy for self-employment.
    • VA loans: excellent for eligible Fort Campbell service members and veterans; self-employment is allowed with proper documentation.

    If you’re still comparing programs, see [INTERNAL LINK: Conventional vs. FHA vs. VA] for a Clarksville-focused breakdown.

    7) How pre-approval works when you’re self-employed

    A self-employed pre-approval is strongest when we review your tax returns and income documentation before you shop. Once we confirm your qualifying income and DTI, we can set a realistic price range and cash-to-close estimate — which helps you write confident offers on homes for sale near Fort Campbell or in the Clarksville housing market.

    For extra preparation, you can also review [INTERNAL LINK: mortgage documents checklist] so you’re not hunting for paperwork at the last minute.

    Quick reference table: self-employed mortgage documentation

    Item Why it matters
    2 years personal tax returns Shows earnings patterns over time
    2 years business returns (if applicable) Verifies business income and structure
    Year-to-date P&L Confirms current-year performance
    Bank statements Documents funds and clean cash flow

    Reminder: guidelines vary by loan type and borrower profile. For official consumer guidance, review CFPB mortgage application documents (2025) and Fannie Mae employment and income analysis (2026).


    Frequently Asked Questions

    1) Can I get a mortgage with only one year of self-employment?

    Sometimes. Many programs prefer two years, but an exception may work if you stayed in the same line of work and can document stable income. The right next step is a quick lender review of your returns and a current-year P&L.

    2) Do lenders use my gross receipts or my net income?

    Usually net income (after expenses) from your tax returns, with certain allowable add-backs. Heavy write-offs can lower qualifying income. If you’re shopping in Montgomery County or Nashville, get your numbers reviewed early so you know what truly counts.

    3) What if my income went down this year?

    A decline can reduce qualifying income because lenders want stability. They may average two years and then cap it if the most recent year is lower. If you’re rebounding now, a strong year-to-date P&L and clean statements can support the story.

    4) Do I need a profit-and-loss statement for underwriting?

    Often, yes. Many lenders require a year-to-date P&L and may request an updated one right before closing. It confirms the business is active and income hasn’t dropped since the last filed return — especially for buyers near Fort Campbell.

    5) Can I qualify if I pay myself mostly through owner draws?

    Yes. Owner draws are common, but underwriting still relies on documented earnings on your tax returns and business financials. The key is showing the business has enough profit and cash flow to support the income used to qualify.

    6) Will my business bank statements be required?

    Frequently. Underwriters may request business statements to verify cash flow, confirm the business is active, or document funds for closing. Separate accounts make this smoother and faster for a Clarksville TN mortgage lender review.

    7) Does being a 1099 contractor count as self-employed?

    Yes. If you receive 1099 income, you’re treated as self-employed for mortgage purposes. Lenders typically want a documented history and will verify it through tax returns (and sometimes current-year earnings). Many first-time homebuyer Clarksville buyers fall into this category.

    8) Can I use a bank statement loan instead of tax returns?

    Possibly, depending on your profile and the programs available. Bank statement loans can help when tax returns don’t reflect true cash flow, but pricing and guidelines can differ. A side-by-side comparison shows which option fits your goals best.

    9) What credit score do I need as a self-employed borrower?

    It depends on the loan type (conventional, FHA, VA, USDA) and your overall file. Self-employment doesn’t automatically require a higher score, but stronger credit can offset complexity and improve terms. If you’re in the Clarksville real estate market, ask for a targeted plan.

    10) How early should I get pre-approved if I’m self-employed?

    Ideally before you start touring homes. Self-employed files can require extra review of returns, P&L, and statements. Getting pre-approved early helps you move fast on homes for sale near Fort Campbell and reduces last-minute conditions.

    By Kate Matties-Deiboldt (NMLS #18487), VanDyk Mortgage — Clarksville TN mortgage lender serving Fort Campbell, Montgomery County, Nashville, and Middle Tennessee.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about self-employed mortgage approval, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)

    The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)

    If you’re buying a home in Clarksville, the mortgage pre-approval process is the fastest way to find out what you can afford and prove to sellers you’re a serious buyer. In plain English: you share your income, assets, credit basics, and documentation, and a lender confirms (in writing) what loan amount you can qualify for.

    • Pre-approval is a documented loan review—not a casual estimate.
    • Expect to provide pay stubs/W-2s (or tax returns), bank statements, and ID.
    • Your lender will verify income, assets, credit, and debts before issuing a letter.
    • In the Clarksville housing market, a strong pre-approval letter can strengthen your offer.
    • Plan for updates: your letter may need to be refreshed if your search takes longer.

    Below is a step-by-step walkthrough of what happens, what you’ll be asked for, and how to avoid the delays that trip up first-time homebuyers in Montgomery County and Middle Tennessee.

    Step 1: Pick the right lender (not just the lowest rate)

    A mortgage pre-approval is a lender’s written commitment to lend—based on the information you provide and the verification they complete. That means the lender’s process matters. A “great quote” doesn’t help if the loan can’t be closed on time.

    If you’re shopping homes for sale near Fort Campbell or commuting toward Nashville, ask lenders about: typical turn times, how they verify income, and how quickly they can update your pre-approval letter for a new offer.

    [INTERNAL LINK: How Much House Can I Really Afford in Clarksville TN?]

    Step 2: Share your goals and your basic numbers

    This is where we match your plan to the right loan type—Conventional, FHA, VA, or USDA. Your loan program is the rulebook: it determines minimum down payment, credit expectations, and how we calculate qualifying income and debts.

    Bring answers to a few core questions:

    • Target monthly payment comfort range (not just a purchase price)
    • Down payment and how long you’ve had the funds
    • Timeline (30–90 days? A PCS move? Lease ending?)
    • Any “must haves” like using a Fort Campbell VA loan benefit or a THDA option

    Step 3: Complete the application (the part most people overthink)

    A mortgage application is the formal record of your financial profile—employment, income, housing history, assets, debts, and the credit authorization. Most pre-approvals start with the same standard application (1003).

    Tip: accuracy beats speed. Small errors (wrong employer dates, missing debts, unexplained deposits) can create extra documentation requests later.

    Step 4: Provide documents (and know what lenders are really looking for)

    This is usually the make-or-break step. Lenders aren’t trying to be difficult—we’re trying to document that your income and assets are stable, usable, and compliant with loan guidelines.

    What you provide Why it matters
    Pay stubs (most recent 30 days) Shows current income and year-to-date earnings
    W-2s (last 2 years) Confirms income history and employer consistency
    Bank statements (most recent 2 months) Verifies down payment, reserves, and large deposits
    Photo ID Meets identity and anti-fraud requirements
    Tax returns (often for self-employed/commission) Documents variable or business income

    If you’re a first-time homebuyer in Clarksville, the most common hangups are large cash deposits, missing pages of bank statements, and switching jobs mid-process without telling your lender.

    [INTERNAL LINK: Mortgage Documents Checklist: Everything Your Lender Will Ask For]

    Step 5: Credit, debt, and DTI review (what the underwriter cares about)

    Your debt-to-income ratio (DTI) is the percentage of your monthly income that goes to monthly debts—including the proposed housing payment. This is one of the main “guardrails” for approval.

    For buyers around Montgomery County TN homes, remember that your total monthly payment can include principal, interest, property taxes, homeowners insurance, HOA dues (if any), and mortgage insurance when applicable.

    Also: don’t open new credit while you’re house hunting. A new car payment can change your DTI overnight.

    [INTERNAL LINK: Debt-to-Income Ratio Explained: How Much Debt is Too Much for a Mortgage?]

    Step 6: Get your pre-approval letter (and use it strategically)

    Once the review is complete, you’ll receive a pre-approval letter showing a maximum loan amount (and sometimes a purchase price). In a competitive Clarksville real estate market, your agent may ask for a letter tailored to the offer—matching the offer price rather than broadcasting your maximum.

    Pre-approval letters are time-sensitive. If your home search stretches out, you may need updated pay stubs, bank statements, or a refreshed credit check.

    Step 7: Keep your file “clean” until closing

    Pre-approval is the beginning—not the finish line. The biggest goal is to keep your financial picture stable while you shop in Clarksville TN and possibly beyond (Fort Campbell to Nashville corridors). Avoid these last-minute issues:

    • Changing jobs or moving from W-2 to self-employed without a plan
    • Large undocumented deposits
    • New credit cards, new loans, or co-signing for someone else
    • Draining savings needed for cash-to-close

    Frequently Asked Questions

    How is pre-approval different from pre-qualification?

    Pre-qualification is usually a quick estimate based on what you tell the lender. Pre-approval is a documented review where income, assets, and credit are verified enough to issue a letter for your offer. In Clarksville, sellers typically take pre-approval more seriously than a pre-qual.

    Does getting pre-approved hurt my credit score?

    Most pre-approvals involve a hard credit inquiry. A single inquiry may cause a small, temporary score change, but it’s usually minor compared to the value of knowing your buying power. If you shop lenders within a short window, credit models often group inquiries together.

    How long does a mortgage pre-approval take?

    If you provide documents quickly, many buyers can be pre-approved in 24–72 hours. Timelines vary based on income type (W-2 vs. self-employed), how complete your bank statements are, and how fast employers or third parties can verify information.

    What documents do I need for pre-approval?

    Most Clarksville TN mortgage lender requests include pay stubs, W-2s, two months of bank statements, photo ID, and permission to pull credit. If you’re self-employed or have commission income, you may also need two years of tax returns and business documents.

    How much can I get pre-approved for in Montgomery County?

    Your pre-approval amount depends on income, debts, credit, down payment, and the loan program—plus local taxes and insurance estimates. Two buyers with the same salary can qualify for different amounts if one has student loans or car payments. The goal is a payment you can live with.

    Can I get pre-approved before I have a house picked out?

    Yes. In fact, that’s the best approach. Pre-approval helps you shop with confidence, prevents wasted time on homes outside your comfort range, and allows you to act quickly when the right property comes up near Fort Campbell or in Clarksville.

    Can I get pre-approved with a new job or recent job change?

    Often, yes—especially for W-2 borrowers who stay in the same field. But job changes can require extra documentation and careful income calculation (bonus, commission, overtime). If you’re relocating to Middle Tennessee, tell your lender early so we build the right plan.

    What if I’m using a VA loan for Fort Campbell?

    VA pre-approval includes confirming eligibility and documenting income, debts, and residual income requirements. You’ll also need a Certificate of Eligibility (COE). A Fort Campbell VA loan can be a powerful option, but the file still needs clean documentation and stable finances.

    How long is a pre-approval letter good for?

    Many letters are valid for 60–90 days, but lenders may require updated pay stubs and bank statements as time passes. If rates change or your income/debts change, your numbers may need to be re-verified. Plan to refresh your letter if your search takes longer.

    What should I avoid doing after I’m pre-approved?

    Avoid opening new credit, financing a car, running up card balances, moving money around without documentation, or changing jobs without talking to your lender. The safest plan is “steady and boring” until closing day. That helps protect your approval and your timeline.


    By Kate Matties-Deiboldt, NMLS #18487
    VanDyk Mortgage · Clarksville TN mortgage lender · Fort Campbell VA loan specialist

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about mortgage pre-approval, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • Mortgage Documents Checklist: Everything Your Lender Will Ask For

    Mortgage Documents Checklist: Everything Your Lender Will Ask For

    If you’re getting ready to buy a home, your lender will ask for documents that prove who you are, how you earn money, what you owe, and where your down payment comes from. The easiest way to make your approval smooth is to gather the “core set” early and keep your paperwork consistent from pre-approval through closing.

    A mortgage documents checklist is a simple list of the paperwork a lender uses to verify your income, assets, debts, and identity for underwriting. Underwriting is the lender’s process of confirming you meet the loan program rules before final approval. Verification is the “prove it” step—turning what you said on the application into documented facts.

    TL;DR — Key takeaways

    • Expect to share ID, income, asset, and housing-history documents—plus explanations for anything unusual.
    • The fastest approvals happen when names, addresses, and dates match across every document.
    • Don’t move money between accounts (or open new credit) without checking first—paper trails matter.
    • Self-employed and VA/FHA buyers may need a few extra items, but the core list is the same.
    • If you’re buying in Clarksville, Fort Campbell, or Montgomery County, having documents ready helps you write a stronger offer.

    As a Clarksville TN mortgage lender, I’m asked all the time: “Why do you need so much paperwork?” Because your mortgage is a regulated loan and your lender must document your ability to repay. Whether you’re buying in Clarksville, commuting to Nashville, or relocating to Fort Campbell, this checklist keeps things moving.

    1) Identity & legal documents (prove you are who you say you are)

    Most buyers provide a government-issued photo ID and basic personal information. If your name changed (marriage/divorce), we’ll document it so underwriting can match your records cleanly.

    2) Income documents (prove how you get paid)

    Income documentation is the set of pay and tax records used to verify stable earnings and calculate qualifying income. The exact items depend on whether you’re W-2, hourly, salary, commissioned, or self-employed—but lenders generally want a two-year view and a current snapshot. If you work on or near Fort Campbell, this is also where we handle LES-style or military-related pay nuances if they apply to you.

    Income type Common documents
    W-2 employee Last 30 days of pay stubs + last 2 years of W-2s (sometimes tax returns)
    Overtime/bonus/commission Pay stubs showing YTD + 2-year history (W-2s and/or returns) to document consistency
    Self-employed / 1099 2 years personal + business tax returns, year-to-date P&L, and sometimes balance sheet
    Other income (alimony, child support, disability, retirement) Award letters, deposit proof, and terms/continuance documentation

    3) Asset & down payment documents (prove you have the funds)

    Asset documentation is the paper trail that shows you have enough money for down payment, closing costs, and required reserves. Typically, underwriting wants statements for any account you’ll use (checking, savings, brokerage). For buyers in Middle Tennessee, this becomes especially important when you’re trying to keep your cash-to-close low with seller concessions or lender credits.

    • Most recent 60 days of bank statements (all pages)
    • Retirement/brokerage statements if those funds are being used or counted as reserves
    • Documentation for large deposits (see “red flags” section below)
    • If selling a home: settlement statement (Closing Disclosure) from the sale

    4) Gift funds, transfers, and “paper trails” (where did the money come from?)

    Seasoning is how long funds have been in an account before closing, and it helps a lender confirm the money is legitimate and not undisclosed borrowing. If a family member is helping, that’s totally common—especially for first-time homebuyer Clarksville households—but we must document it properly. The safest move is to talk about gifts before money moves so we can choose the cleanest method.

    • Gift letter (lender-provided template)
    • Evidence of donor ability (donor statement) and transfer (check/wire/receipt), depending on program
    • Documentation for any recent transfers between accounts

    5) Housing history & real estate documents (rent, own, or buy)

    Housing history is the record of where you’ve lived and what your housing payment has been. If you rent in Clarksville or near Fort Campbell, we may document your rent to strengthen the file. Once you’re under contract, we’ll also collect contract and title-related documents so closing stays on schedule in Montgomery County.

    • Landlord contact info (or 12 months canceled checks if required)
    • Homeowner’s insurance quote (once under contract)
    • Signed purchase contract + addenda (when you have an accepted offer)
    • Earnest money documentation (receipt or cleared check)

    7) A simple way to stay organized (and get to “clear to close” faster)

    Here’s a practical approach that works well for first-time homebuyer Clarksville clients and military relocation Clarksville buyers alike:

    1. Create one folder (digital or paper) labeled “Mortgage Docs.”
    2. Download PDF statements (not screenshots) for bank, retirement, and credit accounts you’ll use.
    3. Keep your pay stubs current; most lenders will ask for an updated stub close to closing.
    4. Avoid moving money between accounts unless we’ve talked through the paper trail first.
    5. Text or email questions early—small issues are easiest to fix before underwriting reviews the file.

    Want a personalized checklist based on your loan type and income? Start here: [INTERNAL LINK: The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)] and [INTERNAL LINK: Debt-to-Income Ratio Explained: How Much Debt is Too Much for a Mortgage?].

    Frequently Asked Questions

    Do I really need to provide “all pages” of my bank statements?

    Usually, yes. Underwriting needs complete statements, even blank pages, to confirm nothing is missing. If your bank portal won’t download the full PDF, tell me and we’ll request an official statement.

    Can I use screenshots instead of PDFs?

    PDF statements are best because they show your name, dates, and full history in one format. Screenshots often miss details and trigger follow-ups. PDFs help keep your Clarksville or Montgomery County file moving.

    How recent do my pay stubs need to be?

    Most lenders want the most recent 30 days for pre-approval and an updated stub close to closing. It confirms you’re still employed and earning what we used to qualify you.

    Why do lenders ask for two years of W-2s or tax returns?

    Two years helps confirm income stability and supports using overtime, bonus, or commission averages. If pay varies, this history is what underwriting relies on to count it.

    What counts as a “large deposit” that needs an explanation?

    Deposits that are unusual for you—especially cash or person-to-person transfers—can be flagged. Underwriting just needs a source. A receipt, bill of sale, or written explanation with proof usually works.

    Can I move money between my checking and savings accounts?

    You can, but frequent transfers can create extra documentation. Underwriting wants a clear trail into the account used for closing. If you’re consolidating funds, ask first.

    What do I need for gift funds from family?

    Usually a gift letter plus proof the donor had the funds and proof of transfer (check, wire, or receipt). Rules vary by loan type, so don’t move money first.

    Do I need documents for earnest money?

    Yes. Keep the receipt plus the cleared check or wire confirmation. Underwriting may also want to see the withdrawal on your bank statement.

    What if I’m self-employed—what documents will I need?

    Most self-employed buyers provide two years of personal and business returns, a year-to-date profit and loss statement, and sometimes a balance sheet. Underwriting is verifying stable business income. [INTERNAL LINK: How Self-Employed Borrowers Get Approved for a Mortgage]

    When will my lender ask for updated documents again?

    Expect updates when your file enters underwriting and again right before closing. Employment may be re-verified near closing. It’s to confirm nothing material changed while you were shopping near Fort Campbell or Nashville.


    Author: Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about mortgage documents, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • Housing Inventory Is Telling Two Very Different Stories in 2026: What It Means for Homebuyers in Tennessee, Kentucky & Around Fort Campbell

    By Kate Deiboldt, Sr. Mortgage Advisor | VanDyk Mortgage. NMLS 18487/NMLS 3035

    If you’ve been watching the housing market over the past couple of years, you’ve probably heard two completely different stories.

    One headline says:

    “The housing market is flooded with inventory.”

    The next says:

    “There still aren’t enough homes for sale.”

    So…which one is true?

    Actually, both are.

    One of the biggest mistakes buyers—and even some real estate professionals—make is assuming the national housing market behaves like one giant market. It doesn’t.

    The real estate market has always been local. In 2026, it’s becoming even more regional.

    Let’s break down what the latest housing inventory trends mean and, more importantly, what they mean if you’re buying or selling a home in Clarksville, Fort Campbell, Montgomery County, or Middle Tennessee.


    National Housing Inventory Is Barely Growing

    According to recent housing market data, active inventory across the United States has increased only about 1.9% year over year.

    That’s a dramatic slowdown.

    Just one year ago, inventory growth was nearly 29%.

    In other words…

    The rapid increase in available homes that many economists expected has largely stalled.

    Instead of seeing inventory explode across the country, we’re seeing something much more interesting:

    Some states are experiencing significant inventory growth while others remain extremely tight.

    That’s why national headlines can be misleading.


    Some States Have Plenty of Homes…

    Builders in parts of the Pacific Northwest—particularly Washington and Oregon—have acknowledged they need to make affordability adjustments to move inventory.

    Why?

    Because those markets have experienced:

    • Higher mortgage rates
    • Slower buyer demand
    • More speculative new construction
    • Greater affordability challenges

    When inventory builds faster than buyers can absorb it, sellers have to compete harder.

    That often means:

    • Price reductions
    • Builder incentives
    • Interest rate buydowns
    • Closing cost assistance
    • More negotiating power for buyers

    If you’re buying in one of those markets, today’s environment may create opportunities that simply didn’t exist a year ago.


    …While Other States Are Still Starved for Inventory

    Meanwhile, many parts of the country continue to struggle with an entirely different problem.

    There still aren’t enough homes.

    These markets often experience:

    • Multiple offers
    • Faster sales
    • Limited inventory
    • Stable pricing
    • Strong demand from local buyers

    This is exactly why buyers shouldn’t assume that what they hear on national news applies to their local market.


    What About Tennessee?

    This is the question I get almost every day.

    “Kate…are home prices about to crash?”

    Short answer:

    I don’t believe so—not here.

    Our market around:

    • Clarksville
    • Fort Campbell
    • Montgomery County
    • Hopkinsville
    • Nashville suburbs

    continues to benefit from several long-term demand drivers.

    Those include:

    • Military relocation
    • Job growth
    • Population migration
    • Affordable cost of living compared to many other states
    • Continued new construction

    Does that mean every neighborhood behaves the same?

    Absolutely not.

    Some price ranges are incredibly competitive.

    Others are sitting longer.

    Some sellers are pricing based on 2022 expectations instead of today’s reality.

    That’s why pricing strategy matters more than ever.


    The Fort Campbell Effect

    One reason our market behaves differently than many others is Fort Campbell.

    Every PCS season brings new military families looking for homes.

    Every retirement creates another group of buyers deciding to stay in Middle Tennessee.

    Unlike markets dependent on a single industry, our area benefits from a consistent flow of relocation.

    That creates housing demand that remains relatively steady even when national headlines become negative.

    As someone who has specialized in VA home loans for more than 26 years, I’ve watched this cycle repeat itself many times.

    National headlines change.

    Fort Campbell keeps moving people.


    Why Inventory Matters to Buyers

    More inventory gives buyers something they haven’t had in years:

    Options.

    When inventory increases, buyers can often:

    • Compare more homes
    • Negotiate repairs
    • Ask for seller-paid closing costs
    • Take a little more time making decisions
    • Avoid bidding wars

    That’s a healthier housing market.

    Not because prices collapse…

    But because buyers regain balance.


    Why Inventory Matters to Sellers

    If you’re selling, increased inventory doesn’t necessarily mean bad news.

    It simply means you have more competition.

    That means your home needs:

    • Accurate pricing
    • Professional marketing
    • Excellent photography
    • Strong Realtor representation
    • A financing partner who can get buyers to the closing table

    Homes that are priced correctly continue to sell.

    Homes chasing yesterday’s prices often sit.


    Mortgage Rates Still Matter

    Inventory is only one piece of the affordability puzzle.

    Mortgage rates remain another major factor.

    A small change in interest rates can significantly impact monthly payments, sometimes more than a modest change in purchase price.

    That’s why I encourage buyers to focus less on headlines and more on monthly affordability.

    Sometimes a seller concession or temporary interest rate buydown creates a much larger financial benefit than negotiating another few thousand dollars off the purchase price.

    There are often multiple ways to structure a winning offer.


    Every Market Has Micro-Markets

    One of my favorite sayings is:

    Real estate isn’t one market. It’s thousands of neighborhoods pretending to be one market.

    For example:

    A $250,000 starter home in Clarksville may receive multiple offers.

    Meanwhile…

    A luxury home priced over $900,000 could sit for months.

    Those are completely different markets despite being only a few miles apart.

    Price point matters.

    Neighborhood matters.

    School zones matter.

    Condition matters.

    Marketing matters.

    That’s why broad national statistics only tell part of the story.


    What First-Time Homebuyers Should Know

    If you’ve been waiting because you’re expecting prices to crash…

    Be careful.

    Waiting can sometimes cost more than buying.

    No one—not economists, lenders, or Realtors—can consistently predict the perfect time to purchase a home.

    What you can control is whether you’re financially prepared.

    That’s why I tell my clients:

    Think of me like Google Maps for mortgages.

    You tell me where you want to go.

    I’ll show you the best route to get there.

    Sometimes that means buying today.

    Sometimes it means creating a six-month plan.

    Sometimes it means improving credit or saving a little more for closing costs.

    The important thing is knowing your options before making a decision.


    My Advice After 26 Years in Mortgage Lending

    I’ve helped thousands of families purchase homes through:

    • Record-low interest rates
    • Double-digit interest rates
    • Housing booms
    • Housing recessions
    • COVID
    • Military relocations
    • Market corrections

    One lesson has remained constant:

    The buyers who succeed are the ones who make decisions based on their personal finances—not scary headlines.

    The media gets paid for clicks.

    You deserve guidance that’s specific to your situation.


    Bottom Line

    The 2026 housing market isn’t crashing.

    It isn’t booming everywhere either.

    Instead, we’re seeing a market that’s becoming increasingly local.

    Some states are experiencing rising inventory and greater buyer leverage.

    Others continue to face limited housing supply.

    Here in the Clarksville and Fort Campbell area, demand remains supported by military relocation, job growth, and population migration. That means buyers and sellers need strategies tailored to our local market—not generic national advice.

    Whether you’re a first-time buyer, relocating to Fort Campbell, using a VA loan, or wondering if now is the right time to buy, the best first step isn’t guessing.

    It’s getting a plan.

    As I always tell my clients:

    Knowledge is power.

    If you’d like to see what you qualify for—or simply understand your options with no pressure and no hard credit inquiry for an initial prequalification—I’d be happy to help.

    Kate Deiboldt
    Sr. Mortgage Advisor | VanDyk Mortgage | NMLS #18487
    📞 (931) 980-9764
    🌐 www.justcallkate.info


    SEO

    • 2026 housing market
    • Housing inventory
    • Homes for sale
    • Tennessee housing market
    • Clarksville TN real estate
    • Fort Campbell homes
    • VA home loans
    • First-time homebuyer Tennessee
    • Montgomery County TN homes
    • Mortgage rates 2026
    • Buy a home in Clarksville
    • Relocating to Fort Campbell
    • Home affordability
    • Seller concessions
    • Housing market forecast 2026

  • Pre-Qualified vs. Pre-Approved: Why the Difference Matters in a Competitive Offer

    Pre-Qualified vs. Pre-Approved: Why the Difference Matters in a Competitive Offer

    Pre-qualification is an early estimate; pre-approval is a lender-reviewed commitment based on documentation. In a competitive Clarksville or Nashville-area market, a pre-approval usually gives you stronger negotiating power because it shows you can actually close.

    If you’re shopping in Clarksville, near Fort Campbell, or anywhere in Montgomery County, knowing which one you have (and when to upgrade) can save you time, stress, and missed homes.

    TL;DR — Key Takeaways

    • Pre-qualification is a quick snapshot based mostly on what you tell a lender.
    • Pre-approval is a stronger step that uses verified documents (income, assets, credit).
    • In multiple-offer situations, sellers often favor buyers who are pre-approved (not just pre-qualified).
    • Your pre-approval also helps you set a real budget for homes for sale near Fort Campbell and Clarksville neighborhoods.
    • Even with a pre-approval, your loan still has conditions—so keep your finances steady until closing.

    1) Quick definitions (and what each one really means)

    Pre-qualification is a preliminary estimate of what you might be able to borrow, usually based on a short conversation, a basic application, and unverified information you provide.

    Pre-approval is a lender-reviewed decision that you qualify for a specific loan amount, based on documentation (pay stubs, W-2s, bank statements) and a credit review.

    A pre-approval letter is a written summary of your pre-approval that you submit with an offer to show the seller you’re a serious buyer.

    For a first-time homebuyer in Clarksville, these terms sound similar—but they signal very different levels of certainty to a seller, a listing agent, and even to you.

    2) What a pre-qualification typically includes (and what it misses)

    A pre-qualification is often fast. A Clarksville TN mortgage lender may ask about your income, estimated monthly debts, a rough down payment amount, and your goals (FHA vs. VA vs. Conventional, for example). Some lenders may run credit; some won’t.

    What it can miss is the stuff that causes surprises later: the exact way student loans are counted, overtime/bonus history, job gaps, or how variable income is averaged. If you’re relocating with the military to Fort Campbell, that matters because timelines are tight and offers move quickly.

    Use pre-qualification to start planning, not to make your strongest offer.

    3) What a pre-approval includes (and why sellers care)

    A pre-approval takes more work—but it carries more weight. You complete a full loan application and provide documents so your lender can verify income, assets, employment, and credit details. Then you receive a pre-approval letter for a specific purchase price and loan type.

    In the Clarksville housing market (and across Middle Tennessee when homes get multiple offers), sellers want confidence. A pre-approval reduces the fear that financing will fall apart after they take the home off the market.

    It also helps you set a real payment comfort zone and estimate cash-to-close.

    4) The real-world impact in a competitive offer

    When two offers look similar, sellers often choose the one that feels most certain. Pre-approval is one of the easiest ways to increase certainty without offering more money.

    • Fewer question marks: verified documents show you’re ready to move forward.
    • Cleaner negotiations: it supports realistic timelines for appraisal, underwriting, and closing.
    • Stronger credibility: it signals you’ve done your homework.

    Bottom line: if you’re writing offers on Montgomery County TN homes, you want every advantage—and pre-approval is a practical one.

    5) What can change after you’re pre-approved (conditions to watch)

    Pre-approval is strong, but it’s not the finish line. Your loan still goes through underwriting and closing conditions. Avoid common mistakes like:

    • New debt (car, furniture, big credit card balances).
    • Job or income changes right before closing.
    • Large undocumented deposits or account transfers.
    • Down payment funds that can’t be sourced.

    After you’re pre-approved, keep your finances steady until closing day.

    6) A simple checklist: when to get pre-qualified vs. pre-approved

    Milestone Best Step Why it fits
    You’re 3–6 months out from buying Pre-qualification Get an early budget and identify any quick fixes.
    You want to tour homes soon Pre-approval Be ready to write a clean offer quickly.
    You’re in a multiple-offer area in Clarksville or Nashville Pre-approval Shows the seller you’ve been vetted beyond estimates.
    You’re PCS-ing to Fort Campbell on a tight timeline Pre-approval Reduces delays and last-minute document surprises.

    Related reading: [INTERNAL LINK: The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)] and [INTERNAL LINK: Mortgage Documents Checklist: Everything Your Lender Will Ask For].

    7) Next steps: turn your letter into a stronger offer

    If you’re early, a pre-qualification can help you plan. But if you’re actively touring homes for sale near Fort Campbell or around Clarksville, the winning move is usually upgrading to pre-approval before you write offers.

    • Gather documents up front (pay stubs, W-2s/tax returns, bank statements).
    • Keep your finances steady: avoid new debt, job changes, and large undocumented deposits.
    • Match the loan to the property so your timeline stays realistic.

    Helpful references: CFPB mortgage preapproval basics (2024) and Fannie Mae Single-Family resources (2026).


    Frequently Asked Questions

    1) Is a pre-qualification the same thing as being approved for a mortgage?

    No. A pre-qualification is an estimate based mostly on unverified information. Approval happens later after a full application, documentation review, and underwriting. Think of pre-qualification as an early planning step, not a promise you can close on a home in Clarksville or near Fort Campbell.

    2) Does pre-qualification require a credit check?

    Sometimes, but not always. Some lenders will do a soft pull or no pull for a quick estimate, while others may run credit to give a more accurate picture. If credit is pulled, ask whether it’s soft or hard and how it might affect your next steps toward pre-approval.

    3) How long does a pre-approval take?

    If your documents are ready, many buyers can get pre-approved quickly—often within a day or two. Timing depends on how complex your income is and how fast you can provide items like pay stubs, W-2s, and bank statements. PCS timelines to Fort Campbell often benefit from getting started early.

    4) How long is a pre-approval good for?

    Pre-approvals commonly have an expiration window (often 60–90 days) because income, assets, and credit can change. If your search in Montgomery County takes longer, your lender can usually refresh your file by re-checking documents and credit so your letter stays current for offers.

    5) Can I make an offer with only a pre-qualification letter?

    You can, but it may weaken your offer in a competitive Clarksville housing market. Sellers usually prefer a pre-approval letter because it reflects verified information. If you’re serious about a specific home, upgrading from pre-qualification to pre-approval can be the difference between winning and losing.

    6) What documents do I need for pre-approval?

    Most buyers need recent pay stubs, W-2s or tax returns, bank statements, and permission to pull credit. You may also need proof of retirement income, child support, or VA eligibility if you’re using a Fort Campbell VA loan. A complete checklist is here: [INTERNAL LINK: Mortgage Documents Checklist].

    7) Will getting pre-approved lock my mortgage rate?

    No—pre-approval does not automatically lock your rate. A rate lock is a separate step you take once you’re under contract (or sometimes earlier) depending on strategy and lender options. If Nashville mortgage rates are moving, we’ll talk about whether locking sooner makes sense for your timeline.

    8) Can I be pre-approved with less-than-perfect credit?

    Often, yes. The best path depends on your loan type and your overall profile. FHA guidelines can be more flexible than conventional, and VA loans have their own approach. A pre-qualification can identify the fastest credit improvements to help you reach a clean pre-approval for homes in Middle Tennessee.

    9) Should I get pre-approved before I talk to a Realtor?

    It’s usually smart. A pre-approval helps your Realtor focus your search on homes you can truly afford and strengthens your offer when you find the right one. If you’re still early, a pre-qualification can work as a starting point, but upgrade before serious shopping in Clarksville or Montgomery County.

    10) What’s the biggest mistake buyers make after getting pre-approved?

    Changing their finances. New debt, large purchases, job changes, or undocumented deposits can delay or derail final approval. After you’re pre-approved, keep your budget steady and communicate before you make financial moves—especially when you’re trying to close on a home near Fort Campbell on a tight schedule.

    By Kate Matties-Deiboldt, NMLS #18487 — VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about pre-qualification vs. pre-approval, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender • Fort Campbell VA loan specialist

  • Tennessee First-Time Homebuyer Programs (THDA Great Choice, Plus Local Grants)

    Tennessee First-Time Homebuyer Programs (THDA Great Choice, Plus Local Grants)

    If youre buying your first home in Tennessee, the best programs usually combine a manageable down payment with help covering cash-to-close. In Clarksville and Montgomery County, most first-time buyers start by comparing THDAs Great Choice program (plus down payment assistance) with FHA, VA, USDA, and conventional optionsbecause the “best” program depends on your credit, income, and where youre buying.

    This guide breaks down whats available, how the programs work, and how to choose the right fit for a first-time homebuyer in Clarksville, Fort Campbell, and Middle Tennesseewithout the overwhelm.

    • THDA Great Choice is Tennessees flagship first-time homebuyer program and can be paired with down payment assistance for eligible buyers.
    • Down payment assistance is help with your upfront cash (not a discount on the home price) and typically comes as a second loan you repay over time.
    • A first-time homebuyer is usually someone who hasnt owned a home in the last 3 yearsbut rules can vary by program.
    • Fort Campbell buyers may qualify for VA loans (often 0% down), which can be better than first-time buyer programs if youre eligible.
    • In the Clarksville housing market, getting pre-approved early helps you act quickly and understand your true budget.

    1) What counts as a first-time homebuyer in Tennessee?

    A first-time homebuyer is a person who has not owned a primary residence in the last three years. Thats the most common definition used for state and housing-agency programs, and it matters because it determines whether you can access special rates or down payment assistance.

    Down payment assistance is financial help toward your upfront cash-to-close. Most programs structure it as a second mortgage or deferred-payment loanwhich can be a smart tool, but its important to understand the repayment rules before you commit.

    THDA is the Tennessee Housing Development Agency. THDA administers statewide homebuyer programs, including Great Choice and related assistance options, and sets rules around income limits, purchase price limits, and buyer education requirements.

    A grant is money you typically dont repay, while an assistance loan is money you pay back later. Many grantsadvertised online are actually forgivable or deferred loans, so its worth confirming the exact terms.

    2) The THDA Great Choice program (the big one to know)

    For many first-time homebuyers in Middle Tennessee, THDA Great Choice is the program that starts the conversation. Its designed to make homeownership more accessible by offering competitive mortgage terms and the ability to pair the first mortgage with down payment assistance.

    If youre looking for the most reliable place to start, review THDAs program overview and limits directly: THDA Great Choice Home Loan (2026).

    3) THDA down payment assistance: how it helps (and the trade-offs)

    Down payment assistance can be the difference between ready someday and ready now. It can help cover part of your down payment and/or closing costswhich is especially helpful for first-time homebuyer Clarksville clients who have strong income but limited savings after rent, childcare, or PCS expenses.

    Important: assistance isnt available for every borrower or every property, and the paperwork can be more detailed than a standard mortgage.

    Heres the trade-off: assistance typically creates a second loan. That second loan might be repaid over time or deferred (paid back when you sell or refinance). Either way, it changes your long-term math, so you want to compare scenarios side-by-side.

    • Best for: buyers who can comfortably afford the monthly payment but need help upfront.
    • Watch-outs: second-loan payments can reduce how much house you qualify for; refinancing later may require paying the assistance back.

    THDAs assistance options are summarized here: THDA Down Payment Assistance (2026).

    4) Local grants & city/county programs: what to ask about in Clarksville

    Beyond THDA, buyers sometimes qualify for local grants or employer/occupation-based assistance. These programs change more often than statewide offerings, so the best approach is to confirm whats currently open, what funding cycle its in, and whether theres a waitlist.

    In Montgomery County and the Clarksville real estate market, I recommend asking three very specific questions early:

    1. Is the assistance a true grant, or a repayable second loan?
    2. Are there income or location limits (certain neighborhoods, census tracts, or purchase price caps)?
    3. Does it require homebuyer education, inspections, or additional underwriting steps that affect your timeline?

    If youre relocating to Fort Campbell or commuting toward Nashville, the location limits mattersome programs apply only to specific zip codes or targeted areas.

    5) Dont overlook FHA, VA, and USDA (they can beat first-time programs)

    Many people assume first-time homebuyer programs are the only path. In reality, the best deal often comes from matching the right loan type to your situation.

    • VA loan: For eligible service members, veterans, and some surviving spouses, VA loans can offer 0% down and flexible guidelines. If youre buying homes for sale near Fort Campbell, this is often the first option we test. Start here: VA Home Loans (2026).
    • USDA loan: For eligible rural areas and income limits, USDA can be 0% down. Depending on the property location around Montgomery County TN homes, it may be worth checking.
    • FHA loan: Often a strong fit for buyers with moderate credit scores or limited down payment, especially when paired with assistance.
    • Conventional: Can be excellent for buyers with higher credit, stable income, and some savingsand may have lower long-term costs than FHA in certain cases.

    If you want a quick comparison point, these related reads can help you narrow your path: [INTERNAL LINK: FHA Loans Explained: Who Should Use One in Clarksville TN] and [INTERNAL LINK: Conventional vs. FHA vs. VA: Which Loan Is Right for Your Clarksville Home?].

    6) A simple decision path (so you dont get overwhelmed)

    Heres the cleanest way to decide what to pursue firstespecially for first-time homebuyer Clarksville families who are balancing budget, timelines, and uncertainty:

    Situation Start by testing Why its a good first step
    Eligible for VA VA loan + compare to THDA assistance Often 0% down; may beat assistance programs
    Low savings but stable income THDA Great Choice + down payment assistance Lowers upfront cash barrier
    Moderate credit FHA + check if THDA pairing is possible More flexible credit guidelines
    Buying in USDA-eligible area USDA 0% down + compare costs Can be 0% down with competitive terms
    Strong credit + some savings Conventional (and price in closing costs) Can reduce long-term mortgage insurance costs

    7) How to get started in Clarksville (and what to bring to pre-approval)

    In the Clarksville housing market, speed and clarity matter. A great first-time buyer plan starts with a real pre-approvalnot a quick online estimate. Your pre-approval tells you what price range makes sense and which assistance options youre likely to qualify for.

    Start here if you havent yet: [INTERNAL LINK: How Much House Can I Really Afford in Clarksville TN? (The Real Math)] and (for the process itself) [INTERNAL LINK: The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)].

    Frequently Asked Questions (Tennessee first-time homebuyer programs)

    1) Do I have to be a true first-time buyer to use THDA?

    Often, no. Many programs use the three-year rulemeaning you may qualify if you havent owned a primary home in the last three years. Some exceptions can also apply in targeted areas or special situations. The safest move is to check current THDA rules and confirm eligibility during pre-approval.

    2) Is THDA down payment assistance free money?

    Usually its not free money. Down payment assistance is often structured as a second loan with specific repayment terms. It can still be an excellent deal if it helps you buy sooner and the payment fits your budget. You just want to understand whether repayment is monthly, deferred, or due at refinance/sale.

    3) What credit score do I need for Tennessee first-time homebuyer programs?

    Minimum credit score requirements vary by program and by the underlying loan type (FHA, conventional, etc.). Some buyers with moderate credit can still qualify, especially with stable income and manageable debt. If youre unsure, start with a pre-approval plan and well identify the fastest ways to strengthen your profile.

    4) Are there income limits for THDA Great Choice?

    Yes, THDA programs commonly have income limits and purchase price limits that vary by county. That matters in Montgomery County and Middle Tennessee because limits can affect whether you qualify, even if your credit is strong. During pre-approval, well verify household income the way the program defines it and confirm current limits.

    5) Can I use THDA assistance with a VA loan?

    Sometimes the best path is VA alone, because it may reduce your upfront cash without adding a second loan. Whether THDA assistance can be paired with VA depends on program rules and how the loan is structured. If youre buying near Fort Campbell, well compare both options and choose the one with the cleanest long-term cost.

    6) Whats the difference between down payment help and closing cost help?

    Down payment help is designed to cover the portion of the purchase price you bring to the table. Closing cost help covers fees like lender costs, title, appraisal, and prepaid items like homeowners insurance. Some assistance can be used for either, but the terms matter. Your cash-to-close estimate will break these out clearly.

    7) Will down payment assistance raise my monthly payment?

    It can. If the assistance is a repayable second mortgage, it may add a monthly payment. Even if its deferred, it can affect future refinance options or equity when you sell. The right way to decide is to compare two payment scenarios: with assistance and without assistance, using the same home price and rate assumptions.

    8) How long does it take to get approved for these programs?

    Most of the timeline looks like a normal mortgagebut program steps can add time. Homebuyer education, extra documentation, or program-specific underwriting reviews can extend the process. If youre competing for homes for sale near Fort Campbell or commuting to Nashville, building in extra time can prevent last-minute stress.

    9) Can I combine a seller credit with THDA assistance?

    Often, yesbut there are limits to how much total assistance/credits you can receive based on the loan type and guidelines. In the Clarksville real estate market, seller credits can be a powerful way to lower cash-to-close. Ill help you structure the offer so it stays within program rules while still being competitive.

    10) Whats the first step if Im thinking about buying in Clarksville?

    The first step is a quick, no-obligation conversation to map out your best pathTHDA, FHA, VA, USDA, or conventional. Well look at your credit, income, estimated monthly payment, and cash-to-close, then create a plan. Once youre pre-approved, you can shop confidently in Clarksville, Montgomery County, and Middle Tennessee.


    By: Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about Tennessee first-time homebuyer programs, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    4de Call or text: (931) 980-9764
    4e7 Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender Fort Campbell VA loan specialist

  • Can You Use a VA Loan More Than Once? Entitlement & Restoration Explained

    Can You Use a VA Loan More Than Once? Entitlement & Restoration Explained

    Yes — you can use a VA loan more than once. The key is whether you have VA loan entitlement available (either remaining entitlement or restored entitlement) and you plan to occupy the home as your primary residence.

    If you’re moving to or from Fort Campbell, buying again in Clarksville, or relocating across Middle Tennessee, your next step is usually the same: confirm your entitlement status, then build a plan for how (and when) to restore it if it’s tied up in your current home.

    TL;DR (Key Takeaways)

    • You can reuse a VA loan benefit multiple times — there’s no “one-and-done” rule.
    • Entitlement is your VA guarantee amount; it can be remaining or restored.
    • Full restoration typically happens after you sell and pay off the prior VA loan.
    • A one-time-only restoration may be possible if you paid off the loan but kept the home.
    • With remaining entitlement, some buyers can carry two VA loans at once (case-by-case).

    VA loan entitlement is the dollar amount the VA agrees to guarantee to your lender. Restoration of entitlement is the process of getting previously used entitlement back so you can use it again. A Certificate of Eligibility (COE) is the VA document that shows your eligibility and (often) what entitlement is currently available.

    How VA loan reuse works (the real-world version)

    Your VA benefit is reusable as long as you still meet VA guidelines, you plan to occupy the new home as your primary residence, and you have enough entitlement available for the new purchase.

    Entitlement, in plain English

    VA loan entitlement is the dollar amount the VA agrees to guarantee to your lender. If you have “full entitlement,” many borrowers can buy with $0 down (subject to lender approval). If you have “partial entitlement,” you may still buy again, but the down payment rules can change. For the VA’s official overview, see VA.gov: VA home loan entitlement and limits (2025).

    3 ways to restore VA entitlement

    • Sell + pay off the prior VA loan (common when moving from Clarksville or Fort Campbell).
    • Qualified Veteran assumption with substitution of entitlement.
    • One-time-only restoration if the prior VA loan is paid in full but you still own the home.

    The VA lists these restoration conditions on VA.gov: Eligibility for VA home loan programs (2025). The COE request form also notes the one-time restoration option (VA Form 26-1880 PDF).

    Can you have two VA loans at the same time?

    Sometimes. If you still have remaining entitlement and you meet occupancy requirements, you may be able to buy another primary residence while keeping the first home (common with a Fort Campbell PCS). The entitlement math can be tight, so ask your lender to run the numbers early — especially if you’re shopping in the Clarksville housing market or near Nashville.

    Next steps (quick checklist)

    1. Pull your COE and confirm what entitlement is used vs. available.
    2. Pick a strategy (sell/pay off, substitution, or one-time restoration if eligible).
    3. Confirm occupancy timing for the new home (especially for Montgomery County moves).
    4. Get a written pre-approval before you shop homes for sale near Fort Campbell.

    Related reads: [INTERNAL LINK: VA Loans 101 for Fort Campbell Service Members], [INTERNAL LINK: Mortgage Pre-Approval Process (Clarksville Edition)], and [INTERNAL LINK: Down Payment Myths].


    Frequently Asked Questions

    1) Is there a lifetime limit on how many VA loans I can use?

    The VA doesn’t set a simple lifetime “maximum number of uses.” In practice, you can use the benefit again if you have enough entitlement available and you meet VA and lender requirements. Many Fort Campbell and Clarksville buyers reuse the benefit after selling and restoring entitlement.

    2) What is VA loan entitlement?

    VA loan entitlement is the amount the VA guarantees to your lender. It’s not a cap on your home price by itself. Your COE often shows the entitlement used on prior loans, and your remaining entitlement helps determine whether you can buy again with little or no down payment.

    3) What is a COE and why do I need it?

    A Certificate of Eligibility (COE) is the VA document that proves you’re eligible for a VA-backed loan. It also helps show whether entitlement is available. If you’re buying in Montgomery County or moving toward Nashville, having your COE ready early keeps pre-approval and underwriting smoother.

    4) How do I restore my entitlement after I sell my home?

    Usually, selling the home and paying off the VA loan is the cleanest path. After the loan is paid in full and ownership is transferred, the entitlement tied to that property can be restored. Your lender can often help submit the request, and the VA also allows online COE requests in many cases.

    5) Can I restore entitlement if I paid off the loan but kept the house?

    Possibly. The VA describes a one-time-only restoration option for situations where the prior VA loan is paid in full but you still own the home. This can help with a PCS or a move back to Middle Tennessee, but it’s limited — talk through the strategy before you rely on it.

    For the plain-language version, see the VA’s eligibility page (VA.gov (2025)). For the form reference, see VA Form 26-1880 (2026).

    6) Can someone assume my VA loan and free up my entitlement?

    In some cases, yes. If a qualified Veteran assumes your VA loan and substitutes their entitlement, your entitlement may be restored for future use. This is more technical than a normal sale, so you’ll want clear guidance from your lender and closing team before choosing this route.

    7) Can I have two VA loans at the same time?

    Sometimes. If you have remaining entitlement and you meet occupancy requirements for the new home, you may be able to buy another primary residence while keeping the first. This can come up for military relocation Clarksville situations, but the math depends on what entitlement is already in use.

    8) Do I need a down payment on my second VA loan?

    It depends on your entitlement. With full entitlement, many buyers can still do $0 down (if approved). With partial entitlement, you may need a down payment depending on the purchase price and county loan limit calculations. A quick entitlement review early prevents last-minute surprises.

    9) What form is used to request a COE or entitlement restoration?

    VA Form 26-1880 is the Request for a Certificate of Eligibility. It’s used for a COE and in some entitlement restoration situations. You can see the current form page on VA.gov: VA Form 26-1880 (2026), and your lender may be able to submit electronically.

    10) What should I do first if I’m PCSing to Fort Campbell and want to buy?

    Start with your COE and a quick plan call. We’ll confirm entitlement, look at your timeline, and map a realistic budget based on BAH, credit, and today’s Nashville mortgage rates. If you’re shopping in Clarksville or Montgomery County, a strong pre-approval strategy can help your offer.


    Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about using your VA loan more than once, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • USDA Loans in Montgomery County: Zero-Down Loans for Rural Tennessee

    If you’re trying to buy a home in Montgomery County and the down payment is the biggest hurdle, a USDA loan may be the cleanest path to homeownership. USDA loans are designed for eligible rural and some suburban areas and can offer 100% financing (zero down) for qualified buyers.

    • A USDA loan is a zero-down mortgage backed by the U.S. Department of Agriculture for eligible rural/suburban areas.
    • Many areas just outside Clarksville city limits can qualify, including parts of Montgomery County and nearby communities.
    • USDA loans are income-limited, but the limits are often higher than buyers expect for Middle Tennessee.
    • You’ll still pay closing costs, but seller concessions and lender credits can help reduce cash-to-close.
    • If you’re near Fort Campbell or commuting toward Nashville, a quick address check can tell you if the home is eligible.

    USDA eligibility is address-based and income-based. The property must be in an eligible area, and household income must fall under program limits. Zero-down does not mean zero cost—you still budget for appraisal, inspection, and closing costs.

    What is a USDA loan (and who is it for)?

    A USDA loan is a government-backed mortgage through USDA Rural Development that helps moderate-income households buy with no down payment. It’s for primary residences and especially useful for first-time buyers with stable income who haven’t saved 5%–20%.

    USDA Rural Development is the federal program that sets the rules and publishes property eligibility maps. Lenders (like us) handle the mortgage approval process, then the USDA issues the final guarantee.

    Do homes in Montgomery County qualify for USDA?

    Often, yes—especially once you get outside dense areas. In practical terms for a Clarksville-area buyer, USDA eligibility commonly shows up in pockets around the edges of the city and in surrounding communities. The fastest way to know is to run the exact address through the USDA property eligibility tool.

    Here’s the key takeaway: USDA eligibility is about the property location, not the buyer’s job or military status. So whether you work on-post at Fort Campbell, commute to Nashville, or work locally in Clarksville, the address is what decides the map portion of eligibility.

    Income limits and qualifying: what the USDA looks at

    USDA limits are based on total household income—not just the borrower on the loan. If a spouse or other adult earns income, it may count even if they’re not signing.

    Household income is the total expected income of the household from wages, overtime, bonuses, and other sources. Lenders also qualify you using debt-to-income, credit, and stable employment. A quick review up front tells you if USDA fits.

    Credit, debt-to-income, and the “real” approval picture

    USDA loans are more flexible than buyers expect, but not a free-for-all. You still need responsible credit and enough income to afford the payment.

    • Credit: A strong recent history helps—especially on-time housing and installment payments.
    • Debt-to-income: Your monthly debts (car, credit cards, student loans) must leave room for the proposed mortgage payment.
    • Employment: Stable, documentable income matters; changing jobs isn’t always a deal-breaker, but it needs context.

    Unsure where you stand? Start with [INTERNAL LINK: What Credit Score Do You Really Need to Buy a Home in Clarksville TN?] and [INTERNAL LINK: Debt-to-Income Ratio Explained].

    USDA costs: the “zero down” part vs. your cash-to-close

    USDA’s big headline is zero down, but buyers still need a plan for cash-to-close. You may have:

    • Closing costs (lender fees, title, escrow setup)
    • Prepaids (homeowners insurance, property taxes, interest)
    • Appraisal and inspection costs

    Cash-to-close is the total you bring to closing after down payment, costs, credits, and seller concessions. In Montgomery County, a smart offer strategy can include seller-paid closing costs (when the market allows), and lender credits reduce out-of-pocket expenses.

    USDA vs. FHA vs. VA vs. Conventional (quick comparison)

    Choosing the right loan is about the full picture: payment, upfront costs, monthly insurance/fees, and how quickly you can close.

    • USDA: 0% down, but you must meet area + income rules.
    • FHA: 3.5% down with flexible credit, but mortgage insurance is a factor.
    • VA: Often 0% down for eligible Fort Campbell buyers; funding fee rules apply.
    • Conventional: Down payments can be low, but PMI may raise the payment.

    For a deeper side-by-side, see [INTERNAL LINK: Conventional vs. FHA vs. VA: Which Loan Is Right for Your Clarksville Home?].

    How to check USDA eligibility fast (a simple action plan)

    Here’s a quick, buyer-friendly sequence that works well for Clarksville and Middle Tennessee shoppers:

    1. Run the exact address on the USDA eligibility map (don’t guess by city name).
    2. Confirm household income basics (who lives with you, estimated annual income).
    3. Get pre-approved so your offer is strong and your payment range is real.
    4. Plan cash-to-close (closing costs, prepaids, and any seller concessions strategy).

    If you’re shopping near Fort Campbell or along the commute corridor toward Nashville, this quick check is the difference between “maybe” and a confident offer.


    Frequently Asked Questions

    1) Are USDA loans really zero down?

    Yes—USDA loans can offer 100% financing, which means no down payment is required for eligible borrowers buying an eligible property. You’ll still need to budget for appraisal/inspection and closing costs, but your largest upfront hurdle (the down payment) can be eliminated.

    2) Does Clarksville TN qualify for USDA loans?

    Some areas do and some don’t. USDA eligibility is based on the specific property address, not the county name alone. Portions of Montgomery County and areas outside the more dense parts of Clarksville can qualify, so the best move is to run the exact address on the USDA eligibility map.

    3) Do I have to be a first-time homebuyer to use USDA?

    No. USDA is not limited to first-time buyers. The main requirements are that the home is in an eligible area, it’s your primary residence, and your household income fits within USDA limits. Many repeat buyers use USDA when they want zero down in a qualifying location.

    4) What are the income limits for USDA in Middle Tennessee?

    USDA sets income limits by county and household size, and they can change over time. Also, USDA counts total household income, even from people not on the loan in many cases. If you’re buying in Montgomery County near Clarksville, I can run a quick check based on your household size and income.

    5) Is USDA harder to qualify for than FHA?

    It depends. FHA can be more forgiving on credit, while USDA adds the extra layer of income limits and property eligibility. In practice, many buyers qualify for either program. The right choice comes down to your location, household income, credit profile, and which option creates the best payment and cash-to-close plan.

    6) Can I use USDA if I work at Fort Campbell?

    Yes. Your employer doesn’t determine USDA eligibility—property location and household income do. Many Fort Campbell buyers use USDA when they’re purchasing off-post in eligible areas of Montgomery County or nearby communities. If you’re also VA-eligible, we can compare USDA vs. VA to see which is stronger.

    7) What kind of property can I buy with a USDA loan?

    USDA is for primary residences. That can include many single-family homes and some approved condos, but the property must meet basic safety and livability standards. If you’re looking at homes for sale near Fort Campbell or outside Clarksville city limits, we’ll also confirm the address meets USDA’s location rules.

    8) Can I get closing costs covered on a USDA loan?

    Potentially, yes. Depending on the market and the offer strategy, sellers may be willing to pay some closing costs, and lender credits can also reduce cash-to-close. The goal is to structure your purchase so you’re not surprised at the closing table—especially important for first-time homebuyers in Clarksville and Montgomery County.

    9) How long does a USDA loan take to close?

    USDA loans can close on a typical timeline, but they may include an extra USDA review step after the lender approves the file. Timelines vary by workload and location. The best way to keep your closing smooth is to get pre-approved early and submit documents quickly once you’re under contract.

    10) What’s the first step if I want to use USDA to buy near Nashville or Clarksville?

    Start with a quick address-and-income check, then get a full pre-approval so your payment range and offer strength are real. If USDA isn’t the best fit, we can pivot to FHA, VA (common for Fort Campbell), or Conventional. Either way, the goal is a clear plan for buying in Middle Tennessee.

    Byline: Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions about USDA loans in Montgomery County, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis and a plan to put you in the best position to purchase when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • VA Loans: Refinance, Entitlement & Advanced Topics (Questions 81-100)

    Part 5 of the 5-part series “VA Loans: 100 Questions Answered” by Kate Matties-Deiboldt, Sr. Mortgage Advisor serving Clarksville, Fort Campbell & Montgomery County.

    Overview

    The final article explores refinance options, entitlement calculations and advanced VA loan topics. These answers help you make the most of your benefit across multiple homes and life events near Fort Campbell.

    Questions 81-100

    81. What is an IRRRL (Interest Rate Reduction Refinance Loan)?

    An IRRRL, also called a VA Streamline Refinance, allows you to refinance your existing VA loan to a lower interest rate with minimal documentation. It doesn’t require a new appraisal or income verification in many cases. Your existing loan must be current, and you must benefit from the refinance (usually by reducing the rate or changing from an ARM to a fixed rate).

    82. Can I refinance with cash out using a VA loan?

    Yes. A VA cash-out refinance allows you to refinance up to 90% (sometimes 100%) of your home’s value to pay off other debts, finance home improvements or convert a non-VA loan to a VA loan. This type of refinance requires a credit check, appraisal and full underwriting.

    83. Is an appraisal required for a VA refinance?

    It depends. An IRRRL generally does not require a new appraisal, while a cash-out refinance does. If you’re converting from a conventional loan to a VA loan, expect a full appraisal.

    84. What is the recoupment rule for IRRRLs?

    VA guidelines require the costs of an IRRRL to be recouped within 36 months through savings from the lower rate. The lender calculates recoupment by dividing the total loan costs by the monthly savings. This rule ensures the refinance benefits the borrower.

    85. Can I remove or add a spouse on a VA refinance?

    Yes. On an IRRRL you may remove anyone whose entitlement was not used on the original loan. To add a spouse, you’d typically need to do a cash-out refinance or a new purchase loan. Consult your lender about your specific circumstances.

    86. How often can I refinance a VA loan?

    There is no set limit, but you must meet recoupment requirements and demonstrate a tangible benefit each time. Multiple refinances within a short period may raise red flags for lenders and the VA.

    87. What are VA loan limits and how do they work?

    As of recent changes, there are no loan limits for veterans with full entitlement. You can borrow any amount a lender approves without a down payment, as long as you meet credit and income guidelines. If you have remaining entitlement but not full entitlement (because you still own another VA-financed property), county loan limits apply when calculating how much you can borrow without a down payment.

    88. What is bonus entitlement?

    Bonus entitlement refers to the portion of entitlement beyond the basic $36,000 guaranty. It allows borrowers to obtain larger loans without down payments. Using entitlement on one property reduces the amount of bonus entitlement available for subsequent purchases.

    89. How do I restore my VA loan entitlement?

    You can restore entitlement by selling the property and paying off the VA loan in full, or by obtaining a one-time restoration of entitlement if you paid off the loan but still own the property. Contact the VA to request restoration, and provide proof that the loan has been satisfied.

    90. Can I assume a VA loan?

    Yes. VA loans are assumable if the lender and VA approve the buyer. The person assuming the loan must meet credit and income requirements. When someone assumes your loan, your entitlement may remain tied to the loan unless they are an eligible veteran who substitutes their entitlement.

    91. Can a non-veteran assume my VA loan?

    Yes, but your entitlement will remain tied to the loan until it is paid off. To free your entitlement, the buyer would need to be an eligible veteran willing to substitute their own entitlement.

    92. What happens to my entitlement after an assumption?

    If the buyer is not a veteran or does not substitute entitlement, your entitlement remains tied up until the loan is paid in full. This could limit how much you can borrow on another VA loan.

    93. Can I buy again with a VA loan after a short sale?

    Yes. After a two-year waiting period, you may be able to get another VA loan. Restoring entitlement and re-establishing credit are key factors. Lenders will review your financial recovery and ability to repay.

    94. Can I use a VA loan after bankruptcy or foreclosure?

    Yes, but waiting periods apply (see Questions 37 & 38). Once the waiting period is over and you have re-established credit, you can use your entitlement again, subject to underwriting requirements.

    95. Are there mistakes VA buyers should avoid?

    Common mistakes include:

    • Skipping the home inspection
    • Not understanding the funding fee
    • Taking on new debt before closing (which can affect qualification)
    • Assuming the VA sets interest rates (rates vary by lender)
    • Overlooking residual income requirements

    Working with an experienced VA lender and Realtor can help you avoid these pitfalls.

    96. Is a VA loan always the best option for veterans?

    Not always. While VA loans offer many advantages, there are situations where a conventional or FHA loan may be better—for example, if you have a large down payment or plan to buy an investment property. Compare options with your lender based on your goals.

    97. Can I combine a VA loan with down payment assistance?

    Yes. Some state and local programs offer down payment or closing cost assistance that can be combined with a VA loan. Requirements vary by program and location. Talk to your lender about what’s available in Tennessee and Kentucky.

    98. Are there special benefits for disabled veterans?

    Yes. Veterans receiving disability compensation are exempt from the funding fee. Some states offer additional benefits, such as property tax exemptions or lower closing costs. Check with your local county assessor and state veterans affairs office for details.

    99. Can I use my VA loan benefit to build a multi-generational home?

    Possibly. VA loans can finance up to four residential units, so you could build a duplex or fourplex and house multiple family members. You must live in one unit as your primary residence. Construction VA loans are more complex and may require a different lender.

    100. What should I do next if I’m interested in a VA loan?

    Start by speaking with a VA-approved lender who knows the local Clarksville and Fort Campbell market. Obtain your Certificate of Eligibility and discuss your budget, credit and goals. With guidance from an experienced team, you can leverage your VA benefit to buy or refinance a home.

    Ready to use your VA benefit? Whatever your questions, concerns, or hesitations, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    🌐 Web: www.justcallkate.info

    Knowledge is power. Your clear path home — even if you’ve been told no before.


  • FHA Loans Explained: Who Should Use One in Clarksville TN

    FHA Loans Explained: Who Should Use One in Clarksville TN

    If you need a flexible down payment, a more forgiving credit profile, or you’re buying your first home in Clarksville, an FHA loan can be a strong option. An FHA loan is designed to make homeownership more accessible by allowing lower down payments and more flexible underwriting than many conventional loans.

    In plain terms: An FHA loan is a government-backed mortgage insured by the Federal Housing Administration. That insurance helps lenders approve buyers who don’t fit a perfect “A+” credit box.

    • FHA loans are built for accessibility: lower down payment and more flexible credit guidelines than many conventional loans.
    • Mortgage insurance is required: FHA has upfront + monthly MIP, which impacts payment and cash-to-close.
    • FHA is great for many first-time buyers in Clarksville and Montgomery County who want to preserve savings.
    • FHA has property rules: the home must meet safety/condition standards (important for older homes near Fort Campbell).
    • It’s not one-size-fits-all: sometimes conventional or VA is cheaper—we compare options before you commit.

    What an FHA loan is (and what it isn’t)

    An FHA loan is a mortgage insured by the Federal Housing Administration. It’s offered by regular lenders (not the government directly), but the FHA insurance reduces the lender’s risk. That’s why FHA can work well for a first-time homebuyer in Clarksville TN who has limited savings or a shorter credit history.

    Mortgage insurance premium (MIP) is FHA’s version of mortgage insurance. It includes an upfront fee (often financed into the loan) and a monthly premium that’s part of your payment.

    Debt-to-income ratio (DTI) is the percentage of your gross monthly income that goes toward debt payments. FHA guidelines can be more flexible than conventional in some scenarios, especially when the overall file is strong.

    Who FHA is best for in Clarksville and Middle Tennessee

    As a Clarksville TN mortgage lender, I see FHA work best when you want an affordable path to buy soon. Common fit scenarios in Montgomery County and Middle Tennessee:

    • You’re a first-time homebuyer who wants to keep cash reserves after closing (moving costs, furniture, emergency fund).
    • Your credit score is decent but not perfect, or you’re rebuilding after late payments.
    • You have solid income but higher monthly debts (car payment, student loans), and we need a reasonable DTI path.
    • You’re buying a modest home and want predictable terms rather than a risky product.

    For military families relocating to Fort Campbell, I still compare FHA against VA first, because VA home loans (2026) can offer major advantages (no monthly mortgage insurance and often better pricing for eligible borrowers).

    Mortgage insurance (MIP): why FHA can cost more over time

    FHA helps you qualify, but it isn’t free. Mortgage insurance is the trade-off for flexibility. You’ll typically see:

    • Upfront MIP (often financed into the loan so you don’t pay it out-of-pocket all at once).
    • Monthly MIP added to your payment.

    This is why I run side-by-side comparisons with conventional loans for many Nashville-area and Clarksville buyers. Sometimes conventional with PMI is cheaper. Sometimes FHA still wins because the rate and approval path are better. For a broader comparison, see: [INTERNAL LINK: Conventional vs. FHA vs. VA: Which Loan is Right for Your Clarksville Home?].

    If you like reading the official definitions, the HUD overview of FHA loans (2026) is a helpful starting point.

    Property rules: what the FHA appraisal is really checking

    FHA has minimum property standards: the home must be safe, sound, and sanitary. In Clarksville and Middle Tennessee, this commonly comes up with older homes (peeling paint, missing handrails) or utilities that aren’t on at the appraisal.

    Think of it this way: An FHA appraisal is both a value check and a basic safety/condition check. If the appraiser calls out repairs, they may need to be completed before closing. This is especially important if you’re buying a fixer-upper in Montgomery County or trying to close quickly before a Fort Campbell report date.

    FHA vs. Conventional vs. VA: the simple decision

    Most Clarksville buyers are deciding between FHA and conventional, and Fort Campbell buyers often compare FHA vs. VA. FHA usually wins on approval flexibility. Conventional can win on long-term cost if your credit and savings are stronger. VA often wins for eligible service members because it can eliminate monthly mortgage insurance.

    Bottom line: when FHA is the right move

    FHA is often the right move when you need flexibility, you want a manageable cash-to-close, and you’re buying a primary residence in Clarksville TN or nearby Middle Tennessee communities. It’s not always the cheapest long-term loan, but it can be the most realistic path to homeownership—especially when the alternative is waiting years to save a larger down payment.

    If you’re unsure, start with this: Pre-approval is the planning tool. A pre-approval is what lets us run numbers, compare FHA vs. conventional vs. VA, and map out a confident offer strategy for the Clarksville housing market. You can also read: [INTERNAL LINK: The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)].

    Frequently Asked Questions

    What credit score do I need for an FHA loan in Clarksville?

    FHA can be more flexible than conventional, but approval depends on your full file (income, DTI, down payment, and payment history). If you’re close, we can usually build a short plan to boost scores and strengthen your pre-approval for Clarksville and Montgomery County.

    Do FHA loans require mortgage insurance?

    Yes. FHA requires mortgage insurance premium (MIP): an upfront fee (often financed) plus a monthly premium. MIP helps FHA approvals happen, but it raises the payment. I compare FHA MIP to conventional PMI and VA options so you can see the real monthly cost.

    Can I use gift funds for an FHA down payment?

    Often, yes. FHA can allow eligible gift funds from approved sources (like family), but documentation matters. You’ll need a proper gift letter and acceptable sourcing of the deposit. I’ll show you how to document it cleanly so underwriting doesn’t stall your closing.

    Can I buy a fixer-upper with an FHA loan?

    Sometimes. FHA still requires the home to meet basic safety and livability standards. The FHA appraisal checks value and flags issues like peeling paint, missing handrails, or non-working utilities. For older Clarksville homes near Fort Campbell, we plan ahead so repairs don’t surprise you.

    Are FHA closing costs higher than conventional?

    Not always. Many costs are similar across loan types (appraisal, title, escrow setup). FHA also has upfront mortgage insurance, which can increase total cost. The best way to compare is a personalized estimate showing your cash-to-close, credits, and payment for your Clarksville purchase.

    How long does it take to get an FHA loan approved?

    It depends on your documentation, appraisal timing, and how quickly conditions are cleared. FHA can close on a normal purchase timeline, but property-related repair conditions can add time. If you have a tight move date in Montgomery County, we build a speed-focused plan from day one.

    Can I use an FHA loan for a second home or investment property?

    Generally no. FHA is intended for primary residences, meaning you plan to live in the home as your main residence. If you’re buying an investment property in Clarksville or Nashville, we’ll look at conventional programs designed for rentals and the down payment they require.

    Is FHA better than a conventional loan for first-time buyers?

    It depends. FHA can be easier to qualify for with lower savings or bruised credit. Conventional can be cheaper if you have stronger credit and can get good PMI terms. I compare payment, cash-to-close, and longer-term cost so you pick the best fit for your Middle Tennessee plan.

    What is the FHA loan limit for Montgomery County, TN?

    FHA loan limits are set by county and can change each year. The most reliable source is HUD’s official lookup tool. I’ll confirm the current Montgomery County limit during pre-approval so we set your price range correctly before you shop in Clarksville.

    What’s the first step if I’m considering FHA in Clarksville?

    Start with a quick, no-obligation pre-approval strategy call. We’ll review income, credit, and goals, then compare FHA vs. VA, USDA, and conventional. You’ll leave with a clear plan for buying in Clarksville TN, near Fort Campbell, or around the Nashville area.


    Kate Matties-Deiboldt, NMLS #18487 is a mortgage lender with VanDyk Mortgage serving Clarksville, Fort Campbell, Montgomery County, Nashville, and Middle Tennessee. She helps homebuyers get clear on their numbers and confident in their next step.

    Your Clear Guide Through FHA Loans in Clarksville

    Whatever your questions, concerns, or hesitations about FHA loans, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    Call or text: (931) 980-9764
    Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage

    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • VA Loans: Closing, Occupancy & Interest Rates (Questions 61-80)

    Part 4 of the 5-part series “VA Loans: 100 Questions Answered” by Kate Matties-Deiboldt, Sr. Mortgage Advisor serving Clarksville, Fort Campbell & Montgomery County.

    Overview

    We focus on the closing process, occupancy requirements and interest rate considerations. Understanding these details helps you plan for settlement and long-term affordability in the Middle Tennessee market.

    Questions 61-80

    61. What closing costs do VA buyers pay?

    Although there’s no down payment, VA buyers still pay closing costs, which may include loan origination fees, appraisal fees, title insurance, recording fees, prepaid taxes and homeowners insurance. Some costs may be paid by the seller or rolled into the loan with lender credits, but buyers should budget 2% to 5% of the loan amount.

    62. Can the seller pay all of my closing costs?

    The VA allows the seller to pay all of your normal closing costs (origination charges, appraisal, credit report, title, recording, survey). In addition, the seller can provide concessions up to 4% of the loan amount for things like paying your funding fee, prepaid taxes and insurance, or even paying off collections. Negotiating seller credits is part of the purchase contract.

    63. What are prepaid expenses?

    Prepaid expenses are future costs collected at closing, including homeowners insurance premiums, prepaid mortgage interest and initial escrow deposits for property taxes and insurance. These items ensure that your escrow account has enough funds to cover upcoming bills.

    64. What is cash to close?

    Cash to close is the total amount of money you need to bring to the settlement table after accounting for any earnest money deposit, down payment, closing costs, prepaid expenses, seller credits, lender credits and financing of the funding fee. Your lender will provide a Closing Disclosure three days before closing outlining your final cash to close.

    65. When do I receive my Closing Disclosure?

    The lender must provide a Closing Disclosure (CD) at least three business days before closing. The CD details your final loan terms, closing costs and cash to close. Review it carefully and ask questions if anything looks unfamiliar.

    66. What is the minimum occupancy requirement for a VA loan?

    You must intend to occupy the property as your primary residence within a reasonable period, typically 60 days. If you are deployed or on PCS orders, you may have a bit more flexibility, but the key is that the VA loan is for primary residences, not investment or second homes.

    67. Can my spouse occupy the home if I’m deployed?

    Yes. If you cannot occupy the home due to deployment, your spouse or dependent child may satisfy the occupancy requirement. You will need to document the situation with your lender.

    68. What happens if I deploy after buying a home?

    Deployment does not violate the occupancy requirement. Once you have fulfilled your intent to occupy the home, you can deploy or PCS without jeopardizing your VA loan. Many military families rent out their homes during deployment, and some lenders allow a property management contract to satisfy occupancy.

    69. Can I rent my VA-financed home later on?

    Yes. After meeting the occupancy requirement, you may convert your home to a rental property. There is no specific waiting period after initial occupancy, but you must have reasonably intended to live there initially. If you plan to buy another home using a VA loan, your remaining entitlement and DTI will be considered.

    70. Can I buy a home with a VA loan if I plan to PCS soon?

    Yes. Many buyers purchase homes near their current duty station and then move when PCS orders arrive. As long as you intend to live in the home initially, you can buy. Later, you may convert it to a rental or sell it, depending on your goals.

    71. How are VA interest rates determined?

    VA loans have competitive rates because the VA guaranty reduces risk for lenders. Rates are influenced by market conditions, your credit profile, loan term (30 vs. 15 years) and whether you pay discount points. VA rates are often comparable to or slightly better than conventional rates.

    72. Are VA rates lower than conventional rates?

    They often are. Because of the guaranty and lack of mortgage insurance, VA loans typically have rates equal to or slightly better than conventional loans. However, rates vary by lender and day-to-day market movements.

    73. Can I buy discount points on a VA loan?

    Yes. Discount points are optional fees you pay at closing to lower your interest rate. One point equals 1% of the loan amount. Buying points can make sense if you plan to keep the loan long enough to recoup the cost through lower monthly payments. Work with your lender to calculate the break-even point.

    74. What is an APR, and why is it higher than my rate?

    The Annual Percentage Rate (APR) reflects the total cost of borrowing, including your interest rate and certain fees. The APR is typically higher than the note rate because it factors in the funding fee and closing costs. Use APR to compare loan offers, but remember it doesn’t include all costs (like property taxes or homeowners insurance).

    75. Can I lock my VA loan interest rate?

    Yes. When you lock your rate, the lender guarantees that your rate won’t change for a certain period (often 30–60 days). Rate locks protect you from market volatility during the homebuying process. The lock period should extend through your expected closing date.

    76. How long can I lock my rate?

    Most lenders offer 30-, 45-, 60- and 90-day locks. Longer lock periods may cost more. Some lenders offer float-down options if rates drop before closing. Discuss timing with your lender.

    77. What factors affect my VA interest rate?

    Your rate depends on market conditions, your credit score, loan amount, term length, whether you pay points, and whether it’s your first or subsequent use of VA benefits. Lenders may also adjust pricing based on property type and occupancy (single-family vs. multi-unit).

    78. Should I choose a fixed-rate or adjustable-rate VA loan?

    Most borrowers prefer fixed-rate VA loans for stability. Adjustable-rate mortgages (ARMs) often start with lower rates but can adjust up or down after a specified period. ARMs may be suitable if you plan to sell or refinance before the adjustment period. Discuss options with your lender.

    79. Can I refinance my VA loan to get a lower rate?

    Yes. The VA offers the Interest Rate Reduction Refinance Loan (IRRRL), also known as a VA Streamline Refinance. It allows you to refinance to a lower rate with minimal paperwork and no appraisal in many cases. You can also do a VA cash-out refinance to tap equity or convert a non-VA loan to a VA loan.

    80. What if rates fall after I close?

    You can refinance using an IRRRL to take advantage of lower rates. You’ll need to consider closing costs and your remaining loan term to decide if refinancing makes sense. Some lenders offer float-down options before closing if rates drop during the lock period.

    Ready to use your VA benefit? Whatever your questions, concerns, or hesitations, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    🌐 Web: www.justcallkate.info

    Knowledge is power. Your clear path home — even if you’ve been told no before.


  • VA Loans: Property, Appraisal & Funding Fee (Questions 41-60)

    Part 3 of the 5-part series “VA Loans: 100 Questions Answered” by Kate Matties-Deiboldt, Sr. Mortgage Advisor serving Clarksville, Fort Campbell & Montgomery County.

    Overview

    This article covers property requirements, the appraisal process and the VA funding fee. Understanding these topics helps you select a home that meets VA guidelines in the Clarksville and Montgomery County market.

    Questions 41-60

    41. What types of properties can I purchase with a VA loan?

    You can buy most one- to four-unit primary residences, including detached homes, townhomes and certain condos. Condos must be in a VA-approved project. Multi-unit properties (up to four units) are allowed if you occupy one unit as your primary residence. Investment properties and vacation homes are not eligible.

    42. Can I buy a condo with a VA loan?

    Yes, but the condo development must be VA-approved. The VA maintains a list of approved projects. If the project isn’t approved, your lender can help request approval, though it can take time.

    43. Can I buy a manufactured or modular home with a VA loan?

    It’s possible, but the home must meet specific VA and lender guidelines—including being permanently affixed to a foundation and classified as real property. Not all lenders finance manufactured homes, so check availability.

    44. Can I buy a duplex, triplex or fourplex with a VA loan?

    Yes. The VA allows you to buy up to four residential units as long as you occupy one unit. Rental income from the other units may even help you qualify, though guidelines vary by lender.

    45. Can I buy land or a lot with a VA loan?

    The VA loan is generally for homes ready for immediate occupancy, so land-only purchases are not eligible. You may be able to include a lot purchase as part of a construction-to-permanent VA loan, but these are less common.

    46. Can I buy a farm with a VA loan?

    Sometimes. The VA will finance properties with acreage and even small farms, but the value of the residence must be the primary component. Income from farming or commercial activity may not be considered for qualification.

    47. What are the VA’s Minimum Property Requirements (MPRs)?

    MPRs are guidelines ensuring a home is safe, sound and sanitary. The property must have adequate heating, electrical and plumbing systems; a roof in good condition; no lead-based paint hazards; and sufficient space for living, sleeping, cooking and sanitation. The VA appraisal addresses these items.

    48. Is a home inspection required for VA loans?

    The VA does not require a home inspection, but it is highly recommended. An inspection is a thorough evaluation of the property’s condition, whereas the VA appraisal focuses on property value and MPRs. An inspection helps you uncover defects and negotiate repairs.

    49. What is a VA appraisal?

    The VA appraisal estimates the home’s value and ensures it meets MPRs. A VA-approved appraiser will review market data, inspect the property and report findings. The appraisal protects both the borrower and the lender by confirming the home is worth the purchase price and is in acceptable condition.

    50. What happens if the appraisal comes in lower than the purchase price?

    If the appraised value is below the agreed purchase price, you have a few options:

    • Renegotiate the price with the seller
    • Pay the difference out of pocket
    • Request a Reconsideration of Value (ROV) if you have data supporting a higher value
    • Cancel the contract if your purchase agreement includes an appraisal contingency

    51. What is a Tidewater Notice?

    In certain situations, when the appraiser expects the value to come in low, they may issue a Tidewater Notice, giving the buyer and seller an opportunity to provide additional comparable sales before the final report is submitted. This helps ensure the appraiser has the most accurate data.

    52. What is a Reconsideration of Value (ROV)?

    An ROV is a formal request to have a VA appraiser consider additional comparable sales that may support a higher value. Your lender can submit the ROV along with sales data that was not included in the original appraisal.

    53. Who pays for the VA appraisal?

    The buyer typically pays for the appraisal as part of closing costs. Appraisal fees vary by location and property type but generally range from $500 to $750.

    54. What is the VA funding fee?

    The VA funding fee is a one-time fee charged by the Department of Veterans Affairs to help fund the loan program. It replaces monthly mortgage insurance and helps keep the program self-sustaining. The fee is expressed as a percentage of the loan amount and varies based on factors like down payment, whether it’s your first or subsequent use, and your service category.

    55. How much is the VA funding fee?

    For most first-time VA buyers with no down payment, the funding fee is 2.15% of the loan amount. If you put down 5% or more, the fee drops to 1.5%, and if you put down 10% or more, it drops to 1.25%. For repeat users with no down payment, the fee is 3.3%. (These percentages can change; check current rates when applying.)

    56. Is the funding fee refundable?

    The funding fee is generally non-refundable. However, if you become eligible for VA disability compensation after closing and your effective date is prior to your closing date, you may be able to request a refund of the fee.

    57. Who is exempt from the funding fee?

    Borrowers receiving VA disability compensation (or who are entitled but not yet receiving compensation) are exempt. Certain surviving spouses and Purple Heart recipients (active-duty) may also be exempt.

    58. Can I finance the funding fee?

    Yes. Most borrowers roll the funding fee into their loan amount. Financing the fee increases your loan balance slightly but avoids out-of-pocket cost at closing.

    59. When is the funding fee paid?

    The fee is collected at closing. If it’s being financed, it’s included in the total loan amount; otherwise, it’s part of the funds you bring to the settlement table.

    60. Does paying the funding fee mean I pay more in monthly payments?

    Financing the funding fee increases your loan balance, which slightly increases your monthly payment. If you pay the fee upfront, your payment will be lower. Discuss your cash position and goals with your lender to decide which option makes sense.

    Ready to use your VA benefit? Whatever your questions, concerns, or hesitations, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    🌐 Web: www.justcallkate.info

    Knowledge is power. Your clear path home — even if you’ve been told no before.


  • VA Loans: Down Payment, Credit & Income (Questions 21-40)

    Part 2 of the 5-part series “VA Loans: 100 Questions Answered” by Kate Matties-Deiboldt, Sr. Mortgage Advisor serving Clarksville, Fort Campbell & Montgomery County.

    Overview

    We dive into financing specifics — down payment rules, credit requirements and how lenders assess income and residual income for VA loans. Understanding these guidelines helps you plan your Clarksville or Fort Campbell budget.

    Questions 21-40

    21. Do VA loans require a down payment?

    No. One of the biggest benefits of the VA loan is that qualified borrowers can finance 100% of the purchase price. That means you may not need any down payment, although you can choose to put money down if you wish.

    22. Is zero down really possible?

    Yes. Because the VA guarantees a portion of the loan, lenders are willing to finance up to the full purchase price. You’ll still need to budget for closing costs and prepaid items, but the down payment itself can be zero.

    23. Can I still make a down payment?

    Absolutely. Some buyers choose to make a down payment to reduce their loan amount, lower their monthly payment or reduce the VA funding fee. Putting at least 5% down can lower the funding fee percentage.

    24. Does a down payment eliminate the VA funding fee?

    No. While a down payment reduces the funding fee rate, only veterans receiving VA disability compensation are exempt from the funding fee. We’ll cover funding fee details in Part 3.

    25. Can seller concessions cover my closing costs?

    Yes. The VA allows sellers to pay certain closing costs and prepaids on your behalf. Seller concessions can include paying your funding fee, prepaid taxes and insurance, or even paying off debts. However, there is a limit: seller concessions cannot exceed 4% of the loan amount.

    26. What credit score is required for a VA loan?

    The VA itself doesn’t set a minimum credit score, but most lenders require a minimum score around 620. Some will consider scores in the 580–600 range with compensating factors, such as strong residual income or significant savings.

    27. Can I get a VA loan with no credit score?

    It’s possible. Borrowers with no traditional credit history can still qualify by demonstrating responsible payment history through non-traditional trade lines, such as rent, utilities or insurance payments. Lenders may require additional documentation.

    28. Does the VA look at my debt-to-income (DTI) ratio?

    Yes, but there is no hard cap. Most lenders prefer a DTI below 41%. If your DTI is higher, you may still qualify if you have strong residual income or other compensating factors.

    29. What is residual income, and why is it important?

    Residual income is the amount of money left over each month after paying major obligations (mortgage, debts, taxes, insurance). The VA sets residual income guidelines based on region and family size. Meeting the residual income requirement ensures you have enough cash flow for living expenses, making VA loans more affordable for borrowers.

    30. Does BAH (Basic Allowance for Housing) count as income?

    Yes. BAH is non-taxable income for active-duty service members. Lenders typically include BAH in your qualifying income. Because it’s tax-free, your effective income may be higher than it appears at first glance.

    31. Does BAS (Basic Allowance for Subsistence) count as income?

    Often yes. BAS is also tax-free and can be included in income calculations. Some lenders may apply a slight adjustment, so confirm with your lender.

    32. Can overtime and bonus income be used to qualify?

    Usually. Lenders can count overtime and bonus income if it is stable and likely to continue. You generally need to demonstrate a history of receiving this income for at least two years.

    33. Can self-employment income qualify for a VA loan?

    Yes, but you’ll need to provide additional documentation, such as two years of tax returns, profit and loss statements and possibly a letter from your CPA. Lenders want to see stable and predictable earnings.

    34. How is disability income treated in VA loan qualification?

    VA disability compensation is typically acceptable and may be favorably considered. Because it is non-taxable, it increases your effective income. You’ll need to document the amount and verify that it will continue.

    35. Does child support or alimony count as income?

    Yes, provided you can document it with court orders and proof of receipt. Lenders want to see that it has been received consistently and will continue for a certain period.

    36. Can I qualify for a VA loan while on PCS orders?

    Yes. Many military families buy homes while relocating. Your intent to occupy the property within a reasonable time frame (typically 60 days) is key. Lenders may also consider your housing allowance and other benefits in qualifying.

    37. How long after bankruptcy can I qualify for a VA loan?

    It depends on the type of bankruptcy. After a Chapter 7 discharge, there’s generally a two-year waiting period before using a VA loan. For Chapter 13, you may be able to obtain a VA loan after one year of making court-approved payments and with trustee approval.

    38. How long after foreclosure can I qualify?

    Typically, you must wait two years after foreclosure before obtaining a VA loan. Demonstrating re-established credit and stable income is important.

    39. Does my spouse’s credit score affect my VA loan?

    If your spouse will be on the loan, their credit will be considered. In community property states, spousal debts can affect the DTI even if the spouse is not a co-borrower. It’s best to run credit for both spouses early in the process.

    40. Can someone co-sign a VA loan if they aren’t my spouse or another eligible veteran?

    In most cases, no. A non-spouse co-borrower who isn’t an eligible veteran will require a joint loan, which can reduce or eliminate your VA guaranty. Some lenders do offer joint VA loans, but they involve more stringent guidelines and are not common.

    Ready to use your VA benefit? Whatever your questions, concerns, or hesitations, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    🌐 Web: www.justcallkate.info

    Knowledge is power. Your clear path home — even if you’ve been told no before.


  • VA Loans: Basics & Eligibility (Questions 1-20)

    Part 1 of the 5-part series “VA Loans: 100 Questions Answered” by Kate Matties-Deiboldt, Sr. Mortgage Advisor serving Clarksville, Fort Campbell & Montgomery County.

    Overview

    In this first article we cover what the VA loan is, who qualifies, how to get your Certificate of Eligibility, and other fundamentals — the top 20 eligibility questions for Clarksville and Fort Campbell buyers.

    Key takeaways:

    • A VA loan is a mortgage guaranteed by the U.S. Department of Veterans Affairs for eligible service members, veterans, and surviving spouses.
    • Your Certificate of Eligibility (COE) confirms you qualify — an approved VA lender can usually pull it electronically.
    • Zero-down financing, no monthly mortgage insurance, and a one-time funding fee make VA loans powerful at Fort Campbell and across Clarksville.
    • You can reuse your VA entitlement multiple times — even after a previous use, you may have remaining entitlement for a second home.
    • Have questions about your specific situation? Call (931) 980-9764 for a no-obligation review.

    Questions 1-20

    1. What is a VA loan?

    A VA loan is a mortgage guaranteed by the U.S. Department of Veterans Affairs. Instead of lending money directly, the VA provides a guaranty to approved lenders, allowing eligible borrowers to purchase a home with favorable terms—often with no down payment and competitive interest rates. The program is designed to help service members, veterans, National Guard members, Reservists and certain surviving spouses become homeowners.

    2. Who is eligible for a VA loan?

    Eligibility generally includes:

    • Active-duty service members
    • Veterans with sufficient service
    • National Guard and Reservists who meet service requirements
    • Surviving spouses of service members who died in the line of duty or as a result of service-related injuries (and who haven’t remarried)

    Each category has specific service length requirements. The easiest way to confirm is by obtaining a Certificate of Eligibility (COE).

    3. How do I get my Certificate of Eligibility (COE)?

    You can request a COE online through the VA’s eBenefits portal or by working with an approved VA lender (like me) who can often pull it electronically. You’ll need to supply your service details or DD-214. Once issued, the COE confirms to lenders that you qualify for the VA loan benefit.

    4. Do first-time homebuyers qualify for VA loans?

    Absolutely. Many VA borrowers are buying their first home. There is no requirement that you have previously owned a home; the VA program is designed to help first-time buyers as well as seasoned homeowners.

    5. Can I use my VA loan benefit more than once?

    Yes. Your VA entitlement is generally reusable. After paying off a VA loan or selling the property, you can restore your entitlement and use it again. In some cases you may even have enough entitlement remaining to own more than one VA-financed property at the same time.

    6. Can I have more than one VA loan at the same time?

    It is possible, depending on how much of your entitlement remains and the county loan limits. For example, if you still own a home with a VA loan but need to buy another home closer to Fort Campbell, you may be able to obtain a second VA loan using your remaining entitlement. A lender can calculate this for you.

    7. Do National Guard members qualify for VA loans?

    Yes. Guard members may be eligible after six years of service or after 90 days of active service during wartime. Those activated under Title 32 may also qualify. A COE will verify eligibility.

    8. Do Reservists qualify for VA loans?

    Yes. Reservists generally have the same service requirements as National Guard members—six years of service or certain periods of active duty. Make sure to document your service when requesting the COE.

    9. Do surviving spouses qualify for VA loans?

    Many do. An unremarried surviving spouse of a veteran who died in service or from a service-connected disability may be eligible. Spouses of veterans missing in action (MIA) or prisoners of war (POW) may also be eligible. The VA must issue a COE for the surviving spouse.

    10. Can I qualify if I’m currently on active duty overseas?

    Yes. Service members stationed overseas can still use their VA loan benefit. The key is that you must intend to occupy the property as your primary residence once you return. Lenders will require a valid power of attorney if someone else will sign documents on your behalf.

    11. Are there income or asset limits to qualify for a VA loan?

    No. The VA does not set specific income or asset caps. Instead, lenders review your residual income (the money left over each month after major expenses) to ensure the loan is affordable. This makes VA loans accessible to a wide range of buyers.

    12. How does my credit score impact VA eligibility?

    The VA doesn’t set a minimum credit score, but lenders do. Many VA-approved lenders look for a score around 620, though some will consider lower scores with compensating factors. A higher score generally helps you secure better terms.

    13. Can I use a VA loan to buy a second home or investment property?

    No. VA loans are intended for owner-occupied residences. You must certify that you intend to live in the property as your primary home. After meeting the occupancy requirement, you may later convert it to a rental, but you cannot buy a purely investment property using VA financing.

    14. Can I use a VA loan for a vacation home?

    No. The occupancy requirement means you must live in the home as your primary residence. Vacation homes, cabins and short-term rentals are not eligible under VA guidelines.

    15. Does the VA loan require mortgage insurance?

    No. Unlike FHA loans that charge a monthly mortgage insurance premium, VA loans do not have monthly mortgage insurance. Instead, most borrowers pay a one-time funding fee (discussed in Part 3). Removing monthly mortgage insurance can save you thousands over the life of the loan.

    16. Are VA loans available for manufactured homes or mobile homes?

    Sometimes. VA loans can finance manufactured homes, but the home must meet strict guidelines, be permanently affixed to a foundation and be classified as real property. Not all lenders offer this option, so check with your lender.

    17. Can I use a VA loan for new construction?

    Yes, but the process is more complex. You may finance construction with a VA loan if the builder is VA-approved and the plans meet VA specifications. Many borrowers finance the construction with a different loan and then use a VA loan for the permanent mortgage once the home is complete.

    18. How long does it take to close a VA loan?

    Closing times vary by lender, but a typical VA purchase can close in 30–45 days, similar to conventional or FHA loans. Having a COE and necessary documents ready can help streamline the process.

    19. What if I’ve already used my entitlement on a previous home?

    You may still have remaining entitlement to use on another home, or you can restore full entitlement by selling the first home and paying off the loan. In some cases, you can request a one-time restoration of entitlement without selling your home.

    20. What happens if I default on a VA loan?

    If you default, the VA guarantees a portion of the loan to the lender. However, defaulting can result in foreclosure and may impact your ability to obtain another VA loan. It’s important to contact your lender immediately if you have trouble making payments so they can explore options like loan modification.

    Ready to use your VA benefit? Whatever your questions, concerns, or hesitations, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    🌐 Web: www.justcallkate.info

    Knowledge is power. Your clear path home — even if you’ve been told no before.


  • Earnest Money, Down Payment, and Closing Costs: A Buyer’s Cheat Sheet for Clarksville TN

    Earnest Money, Down Payment, and Closing Costs: A Buyer’s Cheat Sheet for Clarksville TN

    Earnest money is a good-faith deposit submitted with your purchase offer; the down payment is the equity stake you bring to closing; and closing costs are the lender, title, and government fees required to execute the transaction. These three cash buckets are separate line items — each with different amounts, timing, and rules — yet first-time homebuyers in Clarksville routinely underestimate or confuse them.

    Clarksville’s median sale price was $327,495 in February 2026, up 5.7% per Redfin (2026). At that price, a buyer could owe anywhere from $3,000 to $65,000+ in upfront cash depending on loan type.

    TL;DR — Key Takeaways

    • Three separate buckets: Earnest money (typically 1–2% in TN), down payment (0–20%+), and closing costs (2–5% of loan amount) are all due at different times.
    • VA buyers at Fort Campbell can purchase with $0 down payment and no PMI.
    • USDA loans also require no down payment for eligible properties in designated rural areas of Tennessee.
    • THDA’s Great Choice Plus program can provide up to $15,000 in down payment and closing cost assistance.
    • Sellers can cover closing costs through seller concessions — up to 4% on VA loans, 6% on FHA/USDA, and 3–9% on conventional.
    • Earnest money is applied toward your down payment or closing costs at the table — it is not an extra expense, just early money.

    What Is Earnest Money — and What Happens to It?

    Earnest money is a cash deposit — typically due within 24–72 hours of contract acceptance — that signals your commitment to the purchase. Tennessee has no state law setting a required amount; it is negotiated between buyer and seller. In Clarksville, the market standard is roughly 1% of the purchase price, with competitive multiple-offer situations pushing to 1–2%, per the National Association of Realtors (2024). On a $327,000 home, that’s $3,270–$6,540.

    Funds go into an escrow account held by a title company or attorney — not the seller — protected by contract contingencies. If the deal closes, earnest money is credited toward your down payment or closing costs. If the sale falls through due to a failed inspection, financing, or appraisal issue, most Tennessee contracts allow you to recover the deposit.

    What Is a Down Payment — and How Much Do You Actually Need?

    The down payment is the portion of the home’s purchase price you pay at closing. Requirements vary significantly by loan type, and for many buyers near Fort Campbell and Clarksville, the requirement is zero.

    • VA Loans: $0 down payment required for eligible veterans and active-duty service members with full entitlement, per VA.gov (2025). No private mortgage insurance (PMI). This is the premier loan for Fort Campbell home buying.
    • USDA Loans: $0 down payment required for properties in eligible rural areas of Tennessee. Income and location eligibility apply.
    • FHA Loans: 3.5% down payment minimum with a 580+ credit score.
    • Conventional Loans: As low as 3% down via Fannie Mae or Freddie Mac programs, though putting down less than 20% triggers PMI.
    • THDA Great Choice: Tennessee’s state housing agency pairs FHA or USDA-backed loans with down payment assistance of up to $15,000 for qualifying buyers, per THDA (2026).

    Bankrate (2025) reports the median first-time buyer down payment was 9% in 2024 per NAR data — but VA entitlements, USDA eligibility, and THDA assistance in Middle Tennessee can dramatically reduce or eliminate that figure.

    What Are Closing Costs — and Who Pays Them?

    Closing costs are the lender fees, third-party service fees, prepaid expenses, and government charges required to execute a mortgage and transfer title. According to Bankrate (2025), mortgage closing costs typically range from 2% to 5% of the total loan amount. On a $327,000 Clarksville purchase, that’s roughly $6,540–$16,350.

    Common line items: loan origination, appraisal, title search, title insurance, attorney/settlement fee, recording fees, homeowner’s insurance prepaid, property tax escrow, and daily interest prepaid. VA buyers pay a Funding Fee (2.15% for first-time use with $0 down, rollable into the loan) but owe no PMI.

    Side-by-Side: Earnest Money vs. Down Payment vs. Closing Costs

    Feature Earnest Money Down Payment Closing Costs
    Typical Amount (Clarksville) 1–2% (~$3,300–$6,600) 0–20%+ ($0–$65,000+) 2–5% of loan (~$6,500–$16,400)
    When Due Within 24–72 hours of accepted offer At closing At closing
    Who Holds It Neutral escrow (title company or attorney) Applied directly at closing Distributed to lender, title co., government
    Refundable? Yes, if contingencies are met and deal falls through for covered reason N/A Partially — some prepaids may be refunded
    Applied to Purchase? Yes — credited toward down payment or closing costs Yes — reduces loan principal Yes — pays required fees
    Can Seller Cover It? No No Yes — up to 4% (VA), 6% (FHA/USDA), 3–9% (conventional)

    How Buyers Should Budget Cash to Close in 5 Steps

    1. Identify your loan type first. VA loans Clarksville TN buyers qualify for can eliminate the down payment entirely. USDA loans work similarly for rural-eligible properties. FHA and conventional require at least 3–3.5% down.
    2. Estimate your earnest money range. For most Montgomery County TN homes near the current median of $327,000–$340,000, budget 1–2%: roughly $3,300–$6,800. This is not an added expense — it comes back to you at closing as a credit.
    3. Calculate your down payment obligation. VA entitlement = $0. FHA buyers on a $327,000 purchase need about $11,445 (3.5%). Check THDA first-time buyer programs before assuming you need the full amount.
    4. Get a Loan Estimate and review closing costs line by line. Your lender must provide a standardized Loan Estimate within three business days of application. On a $327,000 Clarksville purchase, total closing costs typically land between $6,500 and $13,000.
    5. Negotiate seller concessions to reduce cash at closing. Sellers can contribute up to 4% on VA loans, 6% on FHA and USDA, and 3–9% on conventional. In the current Clarksville market with over 2,000 active listings, concession requests are common.

    FAQ — Earnest Money, Down Payment & Closing Costs in Clarksville TN

    How much earnest money is normal in Clarksville, TN?

    In Clarksville and across Middle Tennessee, the typical earnest money deposit is 1% of the purchase price, with 1–2% common on competitive listings. On the current median Clarksville price of approximately $327,000, that’s roughly $3,270–$6,540. Your earnest money is credited toward your down payment or closing costs when you close.

    Can VA buyers waive the down payment completely in Clarksville?

    Yes. Veterans, active-duty service members, and surviving spouses with full VA entitlement can purchase a home in Clarksville, Fort Campbell, or anywhere in Tennessee with zero down payment, per VA.gov (2025). No private mortgage insurance is required.

    What closing costs can sellers cover in a Clarksville transaction?

    Sellers can contribute to buyer closing costs through concessions: up to 4% on VA loans, 6% on FHA and USDA loans, and 3–9% on conventional loans depending on down payment. In the current Clarksville market, requesting seller concessions is a practical strategy for first-time buyers.

    Can gift funds be used for the earnest money deposit?

    It depends on loan type and lender overlays. FHA loans allow gift funds from an approved donor for the down payment and closing costs, but many lenders require the earnest money check to come from the buyer’s own account. Confirm with your Clarksville TN mortgage lender before writing the check.

    Do USDA loans require a down payment for Tennessee homes?

    No. USDA Rural Development loans require no down payment for eligible borrowers purchasing in designated rural areas of Tennessee, per USDA Rural Development (2026). Income limits apply by household size and county.

    Frequently Asked Questions About Earnest Money, Down Payment, and Closing Costs in Clarksville, TN

    1. What is earnest money when buying a home in Clarksville, TN?

    Earnest money is a good-faith deposit submitted with your purchase offer to show the seller you are serious about buying the home. It is typically held by the title company or brokerage and credited toward your closing costs or down payment at closing.

    2. How much earnest money do I need in Clarksville, Tennessee?

    Most Clarksville buyers deposit between 1% and 2% of the purchase price, although the exact amount is negotiable. On a $300,000 home, that typically ranges from $3,000 to $6,000.

    3. Is earnest money the same as a down payment?

    No. Earnest money is a deposit made when your offer is accepted. A down payment is the amount you contribute toward the home’s purchase price at closing.

    4. Do I lose my earnest money if the deal falls through?

    Not necessarily. If your purchase contract includes contingencies such as financing, appraisal, or inspection contingencies and you cancel within those terms, your earnest money is usually refundable.

    5. How much down payment do first-time homebuyers need in Clarksville?

    Many first-time buyers put down between 0% and 5%, depending on the loan program. VA and USDA loans may require no down payment, while FHA loans generally require 3.5% down.

    6. Can I buy a home in Clarksville with no down payment?

    Yes. Qualified buyers may use VA loans or USDA loans, both of which can offer 100% financing with no down payment required.

    7. What is the minimum down payment for an FHA loan?

    The minimum FHA down payment is typically 3.5% of the purchase price when the borrower meets FHA credit requirements.

    8. What are closing costs when buying a home?

    Closing costs are the fees associated with obtaining a mortgage and transferring ownership of a property. They may include lender fees, title fees, recording fees, prepaid taxes, homeowners insurance, and other settlement expenses.

    9. How much are closing costs in Clarksville, TN?

    Most Clarksville buyers can expect closing costs to range from approximately 2% to 5% of the loan amount, depending on the loan type, property taxes, insurance premiums, and lender fees.

    10. Are closing costs and prepaids the same thing?

    No. Closing costs are fees associated with the transaction itself. Prepaids are future expenses collected at closing, such as homeowners insurance, property taxes, and prepaid mortgage interest.

    11. Can the seller pay my closing costs?

    Yes. Seller concessions are common and can help reduce the amount of cash needed at closing. The maximum allowable concession depends on the loan program.

    12. What is included in prepaid expenses?

    Prepaid expenses typically include homeowners insurance, prepaid interest, and initial escrow deposits for property taxes and insurance.

    13. How much cash do I need to buy a home in Clarksville?

    The amount varies based on the purchase price, loan type, down payment, closing costs, and seller concessions. Some buyers can purchase a home with little to no money out of pocket, while others may need several thousand dollars.

    14. Can gift funds be used for a down payment?

    Yes. Many loan programs allow qualified gift funds from family members and, in some cases, approved assistance programs to be used for down payment and closing costs.

    15. What happens to my earnest money at closing?

    Your earnest money deposit is typically credited toward your required funds at closing, reducing the amount you need to bring to the settlement table.

    16. Can earnest money be used for closing costs?

    Yes. Earnest money is generally applied toward your total cash-to-close amount, which may include closing costs, prepaid expenses, and down payment requirements.

    17. What is cash to close?

    Cash to close is the total amount of money a buyer must bring to closing after accounting for the down payment, closing costs, prepaid expenses, earnest money deposits, lender credits, and seller concessions.

    18. Are there down payment assistance programs available in Tennessee?

    Yes. Tennessee offers several down payment assistance programs for eligible buyers. Availability and qualifications vary based on income, credit profile, location, and loan program.

    19. Do VA buyers have closing costs?

    Yes. While VA loans offer no down payment for eligible borrowers, buyers are still responsible for closing costs, prepaid expenses, and any applicable VA funding fee unless exempt.

    20. What is the best way to estimate my cash needed to buy a home in Clarksville?

    The most accurate method is to obtain a personalized mortgage consultation and loan estimate. Every transaction is different, and factors such as taxes, insurance, seller concessions, and loan type can significantly impact the final amount needed.

    Featured Snippet Answer

    How much money do I need to buy a home in Clarksville, TN?

    The amount of money needed to buy a home in Clarksville depends on the loan program, down payment, closing costs, prepaid expenses, and any seller concessions. Some buyers using VA or USDA financing may qualify with little or no down payment, while others may need several thousand dollars for closing costs and prepaid expenses. A personalized mortgage consultation provides the most accurate estimate of your total cash-to-close.

    Kate Deiboldt | Sr. Mortgage Advisor | NMLS #18487
    VanDyk Mortgage Corporation | NMLS #3035
    📞 (931) 980-9764
    🌐 www.justcallkate.info

    Serving homebuyers throughout Clarksville, Fort Campbell, Montgomery County, and Middle Tennessee. Knowledge is power.

    Frequently Asked Questions About Earnest Money, Down Payment, and Closing Costs in Clarksville, TN

    1. What is earnest money when buying a home in Clarksville, TN?

    Earnest money is a good-faith deposit submitted with your purchase offer to show the seller you are serious about buying the home. It is typically held by the title company or brokerage and credited toward your closing costs or down payment at closing.

    2. How much earnest money do I need in Clarksville, Tennessee?

    Most Clarksville buyers deposit between 1% and 2% of the purchase price, although the exact amount is negotiable. On a $300,000 home, that typically ranges from $3,000 to $6,000.

    3. Is earnest money the same as a down payment?

    No. Earnest money is a deposit made when your offer is accepted. A down payment is the amount you contribute toward the home’s purchase price at closing.

    4. Do I lose my earnest money if the deal falls through?

    Not necessarily. If your purchase contract includes contingencies such as financing, appraisal, or inspection contingencies and you cancel within those terms, your earnest money is usually refundable.

    5. How much down payment do first-time homebuyers need in Clarksville?

    Many first-time buyers put down between 0% and 5%, depending on the loan program. VA and USDA loans may require no down payment, while FHA loans generally require 3.5% down.

    6. Can I buy a home in Clarksville with no down payment?

    Yes. Qualified buyers may use VA loans or USDA loans, both of which can offer 100% financing with no down payment required.

    7. What is the minimum down payment for an FHA loan?

    The minimum FHA down payment is typically 3.5% of the purchase price when the borrower meets FHA credit requirements.

    8. What are closing costs when buying a home?

    Closing costs are the fees associated with obtaining a mortgage and transferring ownership of a property. They may include lender fees, title fees, recording fees, prepaid taxes, homeowners insurance, and other settlement expenses.

    9. How much are closing costs in Clarksville, TN?

    Most Clarksville buyers can expect closing costs to range from approximately 2% to 5% of the loan amount, depending on the loan type, property taxes, insurance premiums, and lender fees.

    10. Are closing costs and prepaids the same thing?

    No. Closing costs are fees associated with the transaction itself. Prepaids are future expenses collected at closing, such as homeowners insurance, property taxes, and prepaid mortgage interest.

    11. Can the seller pay my closing costs?

    Yes. Seller concessions are common and can help reduce the amount of cash needed at closing. The maximum allowable concession depends on the loan program.

    12. What is included in prepaid expenses?

    Prepaid expenses typically include homeowners insurance, prepaid interest, and initial escrow deposits for property taxes and insurance.

    13. How much cash do I need to buy a home in Clarksville?

    The amount varies based on the purchase price, loan type, down payment, closing costs, and seller concessions. Some buyers can purchase a home with little to no money out of pocket, while others may need several thousand dollars.

    14. Can gift funds be used for a down payment?

    Yes. Many loan programs allow qualified gift funds from family members and, in some cases, approved assistance programs to be used for down payment and closing costs.

    15. What happens to my earnest money at closing?

    Your earnest money deposit is typically credited toward your required funds at closing, reducing the amount you need to bring to the settlement table.

    16. Can earnest money be used for closing costs?

    Yes. Earnest money is generally applied toward your total cash-to-close amount, which may include closing costs, prepaid expenses, and down payment requirements.

    17. What is cash to close?

    Cash to close is the total amount of money a buyer must bring to closing after accounting for the down payment, closing costs, prepaid expenses, earnest money deposits, lender credits, and seller concessions.

    18. Are there down payment assistance programs available in Tennessee?

    Yes. Tennessee offers several down payment assistance programs for eligible buyers. Availability and qualifications vary based on income, credit profile, location, and loan program.

    19. Do VA buyers have closing costs?

    Yes. While VA loans offer no down payment for eligible borrowers, buyers are still responsible for closing costs, prepaid expenses, and any applicable VA funding fee unless exempt.

    20. What is the best way to estimate my cash needed to buy a home in Clarksville?

    The most accurate method is to obtain a personalized mortgage consultation and loan estimate. Every transaction is different, and factors such as taxes, insurance, seller concessions, and loan type can significantly impact the final amount needed.

    Featured Snippet Answer

    How much money do I need to buy a home in Clarksville, TN?

    The amount of money needed to buy a home in Clarksville depends on the loan program, down payment, closing costs, prepaid expenses, and any seller concessions. Some buyers using VA or USDA financing may qualify with little or no down payment, while others may need several thousand dollars for closing costs and prepaid expenses. A personalized mortgage consultation provides the most accurate estimate of your total cash-to-close.

    Kate Deiboldt | Sr. Mortgage Advisor | NMLS #18487
    VanDyk Mortgage Corporation | NMLS #3035
    📞 (931) 980-9764
    🌐 www.justcallkate.info

    Serving homebuyers throughout Clarksville, Fort Campbell, Montgomery County, and Middle Tennessee. Knowledge is power.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

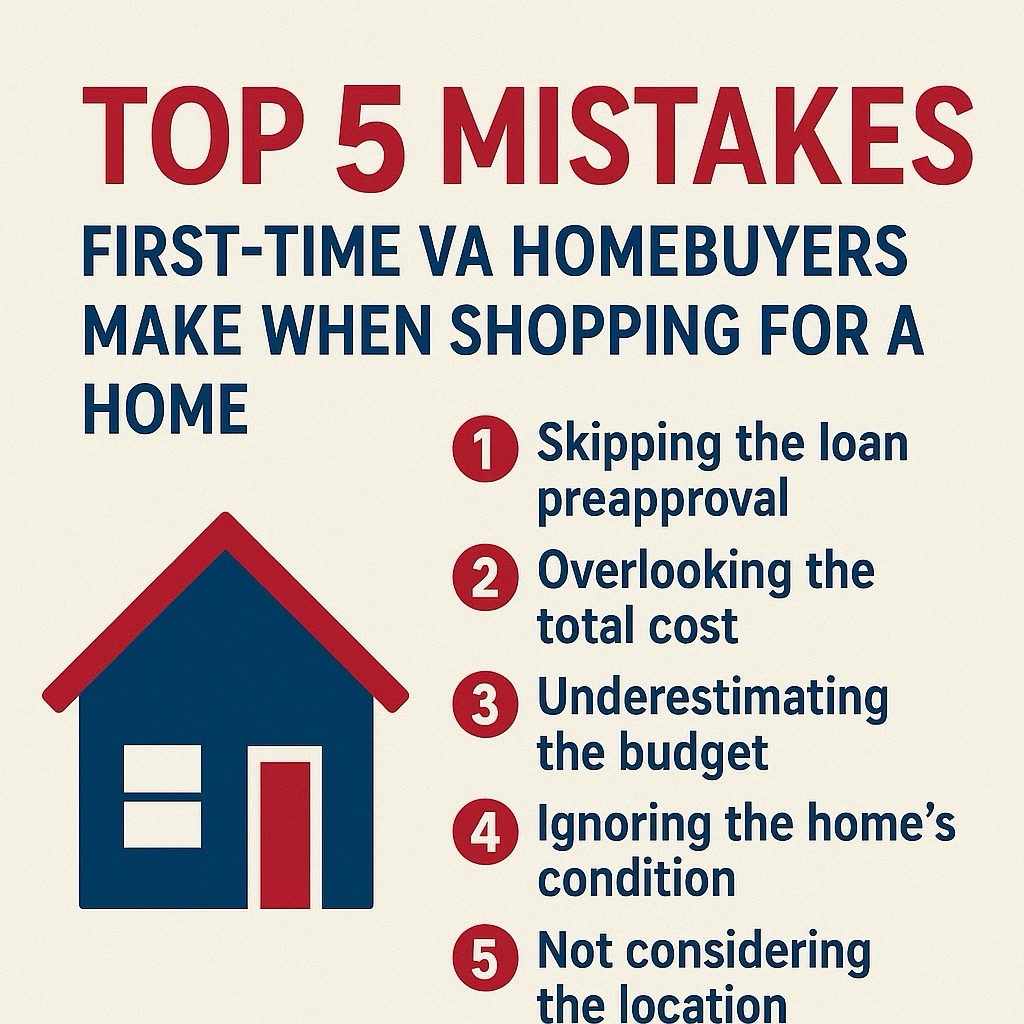
  • Don’t Buy a Car Before Closing — A Clarksville Buyer’s Guide

    Don’t Buy a Car Before Closing — A Clarksville Buyer’s Guide

    Buying a car — or opening any new credit account — before your mortgage closes can kill your loan approval, even after you’ve been pre-approved. Lenders run a credit refresh within days of your closing date to verify nothing has changed since underwriting. If a new auto loan, credit card, or financed appliance shows up, your debt-to-income ratio (DTI) can spike above the allowable ceiling and your file gets sent back to underwriting — or denied outright.

    For buyers pursuing mortgage pre-approval in Clarksville, VA loans at Fort Campbell, or any home purchase across Montgomery County and Middle Tennessee, this is not a suggestion — it is a hard underwriting requirement. The average new-car payment hit $767/month in Q4 2025, per Experian’s State of the Automotive Finance Market (2026). Americans now carry $1.69 trillion in total auto loan debt, per the NY Fed Q1 2026 Household Debt Report.

    TL;DR — Key Takeaways

    • Never take on new debt between pre-approval and closing — lenders re-pull credit before closing and any new liability can derail your loan.
    • A $767/month car payment (2025 national average per Experian) can push a typical Clarksville buyer’s DTI over the 41–45% limit.
    • Credit refresh is a real lender process — a soft or hard inquiry 1–7 days before closing that catches new debt you didn’t have at underwriting.
    • The don’t-list goes beyond cars — new credit cards, co-signing, balance transfers, and store financing all count against your DTI.
    • If you accidentally bought a car, call your lender immediately — there is a recovery path, but speed is everything.
    • Fort Campbell VA loan buyers face residual income tests on top of DTI guidelines, making any new debt even more dangerous.

    What Is a Credit Refresh — and Why Does It Happen Before Closing?

    A credit refresh is a second credit inquiry your mortgage lender performs within days of your scheduled closing — typically 1–7 business days out. A credit refresh is the lender’s final verification that your credit profile, open accounts, and debt obligations match what was underwritten when your loan was approved. Under Fannie Mae guidelines, if a newly discovered debt causes your DTI to increase beyond allowable tolerances, the loan file must be re-underwritten.

    A debt-to-income (DTI) ratio is the percentage of your gross monthly income consumed by recurring monthly debt payments, including your new mortgage PITI. Conventional loans cap back-end DTI at 43–45%; VA loans carry a suggested threshold of 41%, with residual income requirements above that level.

    The Real Cost: How a $767 Car Payment Can Disqualify a Clarksville Buyer

    Here is the math for a realistic Fort Campbell home buying scenario. Clarksville’s median home sale price was approximately $327,495 as of February 2026, per Redfin’s Clarksville housing market data (2026). Assume a military buyer purchases at $320,000 with a VA loan at 6.5%, zero down. Their monthly PITI comes to roughly $2,200/month. Assume gross income of $5,800/month:

    • Before the car: PITI $2,200 + student loan $150 = $2,350 DTI = 40.5% — just inside VA’s 41% scrutiny threshold. Approved.
    • After financing a truck at $767/month: PITI $2,200 + student loan $150 + car $767 = $3,117 DTI = 53.7% — denied under every VA lender overlay and conventional DTI cap.

    Safe Actions vs. Risky Actions During Your Loan Process

    SAFE — Do These During Your Loan RISKY — Avoid Until After Keys Are In Hand
    Pay existing monthly obligations on time Finance a new or used vehicle
    Keep credit card balances stable or pay them down Open a new credit card or retail store card
    Stay in your current job at the same pay structure Change jobs, go 1099/self-employed, or accept unpaid leave
    Keep savings and checking balances steady Make large unexplained cash deposits or withdrawals
    Ask your lender before any financial decision Co-sign on someone else’s auto loan, student loan, or card
    Respond to lender document requests within 24 hours Finance furniture, appliances, or electronics on store plans
    Communicate address, phone, or employer name changes Do a 0% promotional balance transfer to a new credit card

    Buyer’s Pre-Closing Don’t-List: 10 Steps to Protect Your Loan

    1. Freeze all credit applications immediately after pre-approval. Stop applying for any new credit the moment your lender issues a pre-approval letter.
    2. Do not walk into a car dealership — not even to look. Dealers routinely run credit without explicit borrower consent.
    3. Call your lender before co-signing anything. Co-signing makes that full monthly payment part of your DTI, regardless of who pays.
    4. Skip the 0% balance transfer offer. Opening a new card creates a hard inquiry and drops your average account age.
    5. Do not change your job or income structure. Switching from W-2 to 1099 or taking a pay cut requires re-verification of income.
    6. Keep bank balances consistent and documentable. Large unexplained deposits or withdrawals require letters of explanation.
    7. Do not finance appliances or furniture. Store financing creates a new tradeline on your credit re-pull.
    8. Avoid increasing revolving balances on existing cards. Rising balances can lower your score and trigger underwriting questions.
    9. Respond to every lender request within 24 hours. In Clarksville’s market, a missed date can mean losing the property.
    10. Review your Closing Disclosure 3 business days before closing. Confirm your rate, payment, and costs match your Loan Estimate.

    FAQ — Credit, Cars, and Protecting Your Clarksville Home Purchase

    When does the lender pull my credit again before closing?

    Most lenders conduct a credit re-pull between 1 and 7 business days before your scheduled closing. For VA loans in Clarksville, TN and Fort Campbell purchases, the lender must certify no material changes have occurred — making the re-pull a regulatory requirement, not just best practice.

    Can I co-sign on a car loan for a family member while my mortgage is in process?

    No — not without your lender’s sign-off. Co-signing makes you legally responsible for that debt. The full monthly payment is included in your back-end DTI regardless of who actually pays. Wait until after closing.

    What about a 0% balance transfer to a new credit card?

    A 0% balance transfer requires opening a new card — a new tradeline and hard inquiry your lender will see. Opening a new account lowers your average account age and can shift credit utilization, potentially dropping your score 10–20 points.

    Can I change jobs between pre-approval and closing?

    It depends on the type of change, and you must tell your lender immediately. A lateral move to a comparable salaried role is often workable. Switching from W-2 to self-employed, taking a pay cut, or going commission-only creates problems. Fort Campbell VA buyers must disclose any PCS order change, rank change, or transition from active duty to reserve status immediately.

    I accidentally financed a car before closing — is there any recovery path?

    Act immediately: call your loan officer the same day and disclose the purchase. Recovery depends on how much the new payment affects your DTI. Options: pay off the car in full before closing, refinance to a longer term to lower the monthly payment, or negotiate a closing date extension. Whatever you do, transparency with your lender is non-negotiable — concealing a new liability on a mortgage application is mortgage fraud.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
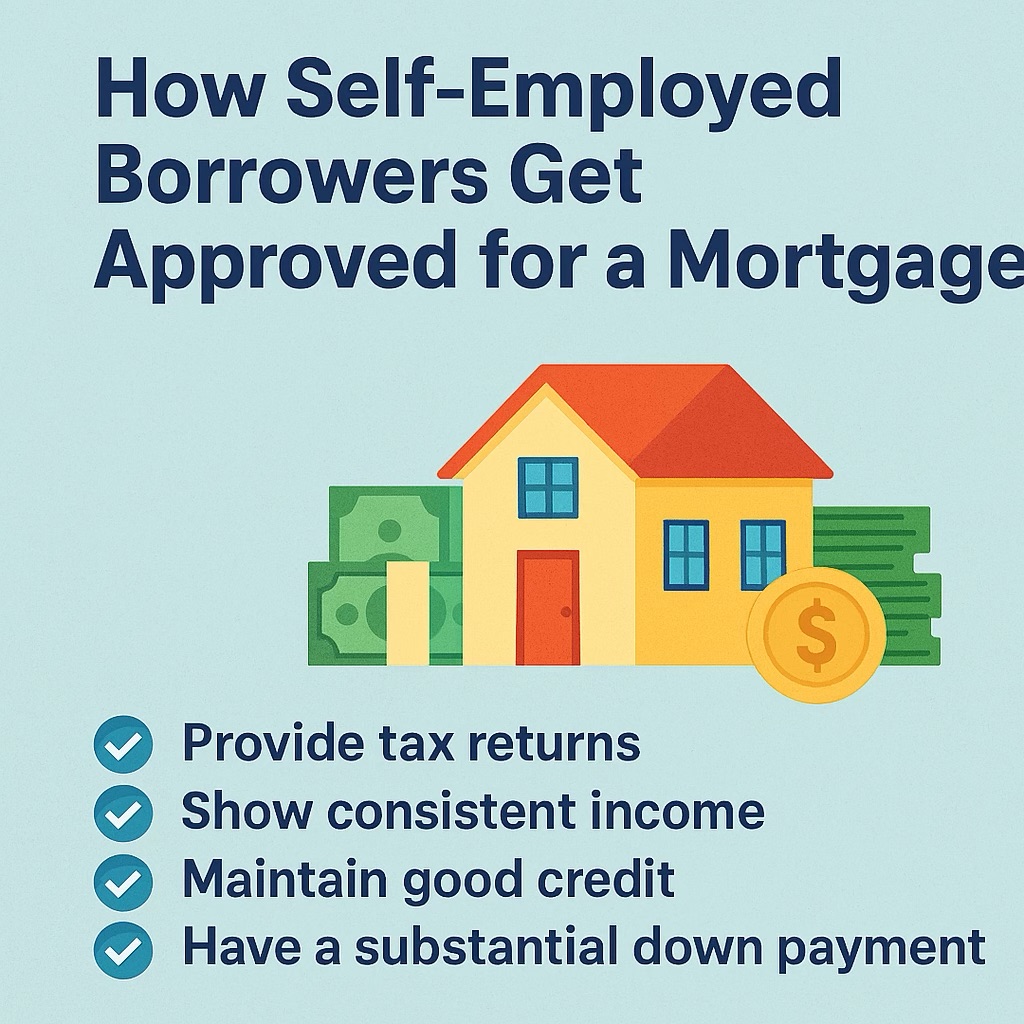
  • Can you reuse your VA Loan Eligibility? YES!

    Can You Use a VA Loan More Than Once? Entitlement & Restoration Explained

    Yes—you can use a VA loan more than once as long as you have enough VA entitlement available (or you restore entitlement from a prior VA loan). That can look like selling a VA-financed home and using VA again, or (in some cases) using remaining entitlement for a new primary residence.

    If you’re relocating to Fort Campbell or moving within Clarksville/Montgomery County, the key is knowing how entitlement gets tied up—and how to restore it.

    TL;DR Key Takeaways

    • You can reuse your VA loan benefit; it’s not a one-time coupon.
    • VA entitlement is the guarantee amount the VA provides to your lender.
    • Entitlement restoration is the process of getting used entitlement back so you can use VA again.
    • A “one-time restoration” may be available if your prior VA loan is paid off but you still own the home (once only).
    • Using VA again can mean a new purchase, a PCS move, or buying in another part of Middle Tennessee.

    1) What “VA entitlement” actually means (in plain English)

    VA entitlement is the dollar amount of guarantee the VA makes available to a lender on an eligible Veteran’s loan. Think of entitlement as backing—not cash—and part of it is allocated to each VA loan.

    Remaining entitlement is the portion that is not currently tied to a VA loan. If you still have enough remaining entitlement, it may be possible to buy another primary residence—even while you still own a VA-financed home.

    A Certificate of Eligibility (COE) is the VA document that shows your entitlement and eligibility status. Your lender uses it to confirm what you can do next.

    2) The short answer: yes, you can use VA more than once

    Around Montgomery County and Fort Campbell, repeat VA use usually fits one of these:

    • Move-up buyer: Buy in Clarksville, sell later, and use VA again.
    • PCS / relocation: Orders or commute changes trigger a new primary residence near Fort Campbell or toward Nashville.

    The rules that matter are (1) occupancy (VA is for a primary residence in most cases), (2) how much entitlement is currently in use, and (3) whether you can restore entitlement from the prior loan.

    3) How entitlement gets restored (the most common paths)

    Entitlement restoration is how you get back entitlement you used on a prior VA loan so you can use the benefit again. The VA describes restoration of previously used entitlement as possible if the prior VA loan is paid in full and the property is disposed/sold, or if an eligible Veteran transferee assumes the loan and substitutes entitlement in the required amount.

    Here are the practical paths I walk Clarksville buyers through:

    1. Sell the home + pay off the VA loan: This is the cleanest path and typically restores entitlement tied to that property.
    2. Eligible Veteran assumption + substitution of entitlement: In some cases, another eligible Veteran can assume and substitute their entitlement (this is less common, but it’s real).
    3. Pay off the VA loan but keep the home: This is where “one-time restoration” can come into play (details next).

    If you’re unsure which category you’re in, start with your COE and a quick review of your current mortgage statement—then we can map the next step.

    4) The “one-time restoration” option (and the catch)

    If your prior VA loan has been paid off in full but you still own the home, the VA allows a one-time restoration of eligibility in many cases. The key word is “one-time.” If you use the one-time restoration, future restorations typically require disposal (selling) of property obtained with a VA loan.

    This comes up a lot for military relocation in Clarksville: a service member wants to keep the first home as a rental but buy a new primary residence closer to Fort Campbell gates, or in another market.

    For documentation and the VA’s own language, see VA Form 26-1880 (PDF, 2026) and the VA Lender’s Handbook chapter on entitlement and restoration in VA M26-7 Chapter 2 (PDF, 2026).

    5) Can you have two VA loans at the same time?

    Sometimes, yes—if you have enough remaining entitlement and you meet occupancy and qualification guidelines. This is most common when someone buys a starter home in Clarksville TN, then later needs a different primary residence due to PCS, family size, or commute changes toward Nashville.

    What I look at with you is your COE (remaining entitlement), the new price range, and a payment/cash-to-close plan that fits your timeline.

    [INTERNAL LINK: VA Loans 101: A Complete Guide for Fort Campbell Service Members]

    6) A simple “next-step checklist” for repeat VA use (Clarksville-friendly)

    A VA reuse plan is a step-by-step decision path that helps you choose between restoring entitlement, using remaining entitlement, or switching loan types. Here’s the order I recommend:

    1. Pull your COE and confirm entitlement status.
    2. List your current property: Will you sell it, rent it, or keep it as a second home?
    3. Confirm your target move timeline (PCS dates matter).
    4. Run payment scenarios with taxes/insurance.
    5. Pick the cleanest path: restore, use remaining entitlement, or consider conventional/FHA if it’s better.

    For rate context, see Freddie Mac PMMS (2026). Your price depends on credit, occupancy, and the property.

    [INTERNAL LINK: BAH vs. Mortgage Payment: How to Use Your Housing Allowance to Buy at Fort Campbell]

    [INTERNAL LINK: The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)]


    Frequently Asked Questions

    1) How many times can you use a VA loan in your lifetime?

    You can use the VA loan benefit again if you have remaining entitlement or you restore it from a prior VA loan. Many Clarksville and Fort Campbell buyers restore by selling and paying off the previous VA loan.

    2) What does it mean when my entitlement is “tied up”?

    When you use a VA loan, part of your entitlement is allocated to that loan until it’s restored. Two VA-eligible buyers can have different buying power depending on whether they still have an active VA loan.

    3) How do I restore entitlement after I sell my home?

    Most commonly, entitlement is restored after the VA loan is paid in full and the property has been sold. Your payoff/closing documents support the update, and your COE reflects the restoration.

    4) Can I restore entitlement if I paid off the VA loan but kept the home?

    Possibly. The VA allows a one-time-only restoration in many cases when your prior VA loan is paid in full but you still own the home. It can help you keep a Clarksville home as a rental while buying a new primary residence.

    5) Can I have two VA loans at the same time?

    Sometimes, yes. If you have enough remaining entitlement and you meet VA occupancy and lender qualification requirements, you may be able to buy a new primary residence while you still own another home with a VA loan. PCS moves tied to Fort Campbell are a common reason this comes up.

    6) Does using a VA loan again change the funding fee?

    It can. Subsequent use may carry a higher VA funding fee than first-time use (unless you’re exempt). We’ll price it out so you can compare VA vs. other options.

    7) Do I need a new Certificate of Eligibility (COE) for my next VA loan?

    Often, yes—you’ll want an updated COE that reflects prior VA loans, restoration, and remaining entitlement. Getting the right COE early helps your Clarksville pre-approval go smoothly.

    8) If I’m PCSing to Fort Campbell, do I have to sell my current home to use VA again?

    Not always. If you have remaining entitlement, you may be able to buy again without selling. If not, you may need to restore by selling and paying off the prior VA loan.

    9) Can I use a VA loan for an investment property or second home?

    Usually, no—VA loans are intended for a primary residence, and you must certify intent to occupy. Many buyers later convert a prior VA home to a rental after moving.

    10) What’s the fastest way to know if I can use VA again in Clarksville?

    Get your COE, tell me whether you plan to sell or keep your current home, and we’ll run a quick scenario for Clarksville TN homes.

    Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about using a VA loan more than once, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist


  • The Death of the Starter Home? What Today’s Homebuyers Need to Know

    For generations, the “starter home” was a major milestone.

    You bought a modest home, built equity, gained financial stability, and eventually moved up to your dream home. It was a proven path to homeownership and wealth-building.

    Today, many buyers are wondering if that path still exists.

    Between rising home prices, higher interest rates, inflation, and limited housing inventory, finding an affordable first home has become more challenging than ever. Many younger buyers are delaying homeownership, living with family longer, renting for additional years, or exploring alternative housing options such as tiny homes, manufactured homes, and RV living.

    But does that mean the starter home is dead?

    Not exactly.

    Why Starter Homes Are Disappearing

    Several factors have combined to make affordable homes harder to find:

    1. Home Prices Have Outpaced Incomes

    While wages have increased over the past decade, home prices in many markets have increased much faster. This means buyers need larger down payments and higher incomes to qualify for the same homes their parents may have purchased years ago.

    2. Inventory Remains Limited

    Many homeowners currently have mortgage rates between 2% and 4%. As a result, they’re reluctant to sell and take on a new mortgage at today’s higher rates. Fewer homes for sale means more competition for entry-level properties.

    3. Construction Costs Have Increased

    Builders face higher costs for labor, materials, land, and regulations. As a result, many builders focus on larger, more expensive homes because they provide better profit margins than smaller starter homes.

    4. Investors Compete for Affordable Homes

    Many of the homes that would traditionally appeal to first-time buyers are also attractive to investors looking for rental properties, creating additional competition.

    What Is Replacing the Traditional Starter Home?

    The definition of a starter home is changing.

    Today’s first-time buyers are finding success through:

    • Townhomes
    • Condominiums
    • Smaller single-family homes
    • Homes farther from city centers
    • Manufactured homes
    • Multi-generational housing arrangements
    • House hacking opportunities where part of the property generates income

    The first home may not look like the traditional starter home of previous generations, but it can still serve the same purpose: helping build equity and financial stability.

    The Good News: Homeownership Is Still Possible

    One of the biggest myths I hear is:

    “I need 20% down.”

    In reality, many buyers qualify with significantly less.

    Depending on the program, options may include:

    • VA Home Loans with no down payment for eligible veterans and active-duty military members
    • FHA financing with as little as 3.5% down
    • Conventional programs with as little as 3% down
    • Down payment assistance programs for qualified buyers

    Many buyers who assume they are years away from purchasing a home discover they are much closer than they think.

    Focus on the First Home, Not the Forever Home

    The biggest mistake I see first-time buyers make is believing their first home must be perfect.

    Your first home doesn’t need:

    • Every item on your wish list
    • A dream kitchen
    • A perfect location
    • Enough space for the next 20 years

    It simply needs to be a stepping stone.

    Homeownership has always been a journey, not a single transaction.

    What This Means for Fort Campbell and Clarksville Buyers

    Here in the Clarksville and Fort Campbell area, we continue to see opportunities that are difficult to find in many larger metropolitan markets.

    While affordability challenges exist everywhere, our market still offers many homes that can work for first-time buyers, military families, and those relocating to Middle Tennessee.

    The key is understanding your options and creating a strategy.

    You may be closer to homeownership than you think.

    Let’s Create a Plan

    If you’ve been told “no,” don’t assume that’s the end of the story.

    Sometimes the answer is simply “not yet.”

    A conversation today could help you understand:

    • How much home you can afford
    • Which loan programs fit your situation
    • Whether down payment assistance is available
    • What steps can improve your approval odds
    • How long it may take to reach your goals

    Knowledge is power.

    Kate Deiboldt
    Sr. Mortgage Advisor | NMLS #18487
    VanDyk Mortgage Corporation | NMLS #3035
    (931) 980-9764
    http://www.JustCallKate.info

    Equal Housing Lender

  • BAH vs. Mortgage Payment: How to Use Your Housing Allowance to buy at Ft Campbell

    BAH vs. Mortgage Payment: How to Use Your Housing Allowance to Buy at Fort Campbell

    If you’re moving to Fort Campbell and you get BAH, you can often use that monthly allowance to comfortably cover a mortgage payment (plus taxes and insurance) instead of paying rent. The key is understanding what counts as “the payment,” how lenders qualify your income, and how to build a realistic budget for Clarksville and the Fort Campbell area.

    TL;DR — Key takeaways

    • BAH is taxable-free income, and in most cases it can be counted toward qualifying for a mortgage.
    • Your mortgage payment is more than principal + interest—budget for taxes, insurance, HOA, and (if needed) mortgage insurance.
    • Pre-approval is your “budget test”: it shows what payment you qualify for, not just a top-line price.
    • Clarksville and Montgomery County have many VA-friendly neighborhoods, but property taxes, insurance, and HOA fees vary widely.
    • Plan for PCS timing: a rate lock, closing date, and possession strategy can reduce stress during a Fort Campbell move.

    BAH is Basic Allowance for Housing—a monthly allowance meant to offset housing costs for eligible service members.

    PITI is principal, interest, taxes, and insurance—the full “all-in” mortgage payment most lenders underwrite to.

    DTI is debt-to-income ratio—your monthly debt payments divided by your monthly gross income.

    1) BAH vs. a mortgage payment: compare the right numbers

    When people say “my BAH covers my mortgage,” they usually mean it covers PITI (plus any HOA dues). In Clarksville and Middle Tennessee, that full payment can be very different from “principal + interest” alone.

    • Principal + interest
    • Property taxes
    • Homeowners insurance
    • HOA dues (separate, but real)

    Compare rent to PITI + HOA so your BAH plan is based on the true monthly cost.

    2) Can BAH be used to qualify for a mortgage?

    Often, yes. Many lenders can count BAH as qualifying income when it’s stable and documented—typically through your Leave and Earnings Statement (LES). Because BAH is tax-free, it can support real-world affordability even when your base pay alone looks tight.

    • Current pay (base + allowances) and active-duty status
    • When BAH starts (or changes) with a PCS to Fort Campbell
    • Any known changes due to rank or dependency status

    The fastest way to avoid guessing is a payment-based pre-approval for a Clarksville-area purchase.

    3) The “BAH-to-payment” budget method (simple and realistic)

    Here’s a buyer-friendly way to run the math before you fall in love with a house near Fort Campbell:

    1. Start with your monthly BAH.
    2. Subtract a cushion for maintenance and “life happens” expenses (many buyers choose 5–10%).
    3. Use what remains as your target all-in payment (PITI + HOA).

    This method matters because even if a lender approves a higher payment, you may not want your housing cost to consume your entire allowance—especially if you’re also paying childcare, car loans, or credit cards.

    4) VA loan advantages that pair well with BAH

    For many Fort Campbell buyers, a VA loan is the most BAH-friendly option because it can offer:

    • Zero down payment for eligible borrowers
    • No monthly mortgage insurance (unlike many low-down-payment conventional or FHA options)
    • Flexible credit guidelines compared to some other programs

    If you want a deeper VA overview, see: [INTERNAL LINK: VA Loans 101: A Complete Guide for Fort Campbell Service Members]. If you’re wondering about VA costs, [INTERNAL LINK: The VA Funding Fee Explained (and When It’s Waived)] is a helpful next read.

    For official VA benefit details, the VA’s home loan page is a good starting point: VA.gov Home Loans (2026).

    5) Clarksville-area costs that can make (or break) the plan

    Two homes with the same price in Montgomery County can have very different monthly payments. The “gotchas” I see most often around Clarksville and the Nashville commuter ring are:

    • HOA dues in newer subdivisions
    • Homeowners insurance that varies by property features and claims history
    • Property tax differences depending on jurisdiction and assessed value

    Before you choose a target price, ask for a payment quote that includes a tax/insurance estimate. It’s the fastest way to see whether your BAH plan works in real life.

    6) PCS timing: align pre-approval, rate lock, and closing

    If you’re relocating to Fort Campbell and shopping in Clarksville, a simple timeline keeps the move smoother:

    • Pre-approval before serious shopping
    • Offer terms that match your report date and moving plan
    • Rate lock plan so you know your options if closing shifts

    Start here: [INTERNAL LINK: The Step-by-Step Mortgage Pre-Approval Process (Clarksville Edition)].

    Quick reference: BAH-to-mortgage checklist

    Step What to do Why it matters
    1 Get a full payment quote (PITI + HOA) Avoid “principal-only” sticker shock
    2 Use LES to document BAH and other pay Makes qualifying smoother
    3 Decide your “comfortable” payment (not just max) Protects cash flow during PCS
    4 Plan inspections + appraisal timeline Reduces closing delays

    Frequently Asked Questions

    1) Can my BAH be counted as income for a mortgage?

    Often, yes. Many lenders can count BAH as qualifying income when it’s stable and documented (usually via your LES). The lender will verify your overall compensation and confirm whether anything changes with your PCS or dependency status.

    2) Is BAH taxable, and does that help me qualify?

    BAH is generally a tax-free housing allowance, which can make your take-home pay stronger than the same amount of taxable income. Underwriting is still based on documented income and debts, but the tax-free nature can support real-life affordability.

    3) What mortgage payment should I compare to my BAH?

    Compare your BAH to the all-in payment: principal, interest, property taxes, and homeowners insurance (PITI), plus any HOA dues. In Clarksville and Montgomery County, taxes and insurance can shift your monthly cost more than buyers expect.

    4) Do VA loans have mortgage insurance?

    No monthly mortgage insurance is required on VA loans. There may be a VA funding fee depending on eligibility and down payment, but many Fort Campbell buyers like VA financing because the payment can be lower than other low-down options.

    5) Can I buy a home near Fort Campbell with zero down?

    If you’re eligible for a VA loan, zero down may be possible. A zero-down plan can work well with BAH, but you still need to budget for closing costs, prepaid items, and moving expenses during a PCS to Clarksville.

    6) What if my BAH changes after I close?

    If your allowance changes due to rank, dependency status, or a move, your mortgage payment doesn’t automatically change—your budget does. That’s why it’s smart to leave a cushion instead of committing your entire BAH to housing.

    7) Can my spouse’s income be used with my BAH?

    Yes, if your spouse will be on the loan and has stable, documentable income. Combining incomes can increase qualifying power, but your debts matter too. Your debt-to-income ratio (DTI) is still a major factor in approval.

    8) Should I get pre-approved before house hunting in Clarksville?

    Yes. Pre-approval shows what you qualify for and helps you shop by payment, not just price. In competitive situations—especially for homes for sale near Fort Campbell—a strong pre-approval can make your offer cleaner and faster.

    9) What documents should I have ready as an active-duty buyer?

    Most buyers should expect to provide an LES, recent pay history, bank statements, and ID, plus any documentation for debts or child support. A lender may also ask for PCS orders when timing or duty station changes are part of the file.

    10) What’s the fastest way to know if my BAH plan works?

    Ask for a payment-based pre-approval and a fee worksheet that includes taxes and insurance estimates. That lets you quickly see the gap between your BAH and the true monthly cost for a specific Clarksville or Montgomery County home.


    Written by Kate Matties-Deiboldt, NMLS #18487 — VanDyk Mortgage. I’m a Clarksville TN mortgage lender and Fort Campbell VA loan specialist, and I help buyers build a plan that fits their life—not just a number on paper.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about BAH vs. mortgage payments, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

  • Down Payment Myths: Why You Probably Don’t Need 20% in Middle Tennessee

    Down Payment Myths: Why You Probably Don’t Need 20% in Middle Tennessee

    If you’re shopping for a home in Clarksville or around Fort Campbell, you probably keep hearing “You need 20% down.” You usually don’t — most buyers use a smaller down payment by pairing the right loan program with a realistic cash-to-close plan, and start building equity in a Montgomery County home sooner.

    • 20% down is a myth for many buyers. Conventional loans can go as low as 3% down, FHA as low as 3.5% down, and VA often allows 0% down for eligible borrowers.
    • Smaller down = different tradeoffs. You may pay mortgage insurance (PMI/MIP) or a VA funding fee—but you keep more cash on hand.
    • Cash-to-close ≠ down payment. Closing costs and prepaid items can matter just as much.
    • Local strategy matters. The strongest plan in the Clarksville housing market is one you can sustain month-to-month — not one that empties savings.
    • You can combine help. Gift funds and assistance programs can cover part or all of the down payment with documentation.

    The myth: “You must put 20% down”

    A down payment is the portion of the purchase price you pay upfront — your initial equity on day one. The 20% rule exists only to avoid mortgage insurance on most conventional loans; it’s a strategy, not a requirement. Freddie Mac (2025) notes the typical buyer puts down 5–20%, and some programs allow as little as 3%.

    Cash-to-close is the total amount you bring to closing — down payment plus closing costs, prepaid taxes/insurance, and reserves. Many first-time homebuyer Clarksville plans fail because buyers save the down payment but forget the rest.

    Reality check: what common loan programs really require

    A conventional loan is a mortgage not insured by the federal government. For qualified buyers, conventional programs can start at 3% down.

    An FHA loan is insured by the Federal Housing Administration. HUD allows a down payment as low as 3.5% (HUD (2026)).

    A VA loan is a benefit for eligible Veterans, active-duty service members, and some surviving spouses. VA.gov (2026) explains a VA-backed purchase loan often offers no down payment and no monthly PMI/MIP — why Fort Campbell VA loan questions come up constantly with military relocation Clarksville families.

    Why some people still push 20% (and when it makes sense)

    Here’s the fair point: 20% down can reduce your payment and may help you avoid PMI on a conventional loan. If you’re moving from Nashville to Clarksville with a big down payment from a home sale, 20% can be a smart, clean option.

    But in Middle Tennessee, where rents are not exactly cheap, waiting to save 20% can be expensive in its own way. The goal is not “the biggest down payment.” The goal is ownership with a payment you can comfortably afford while keeping a safety buffer.

    My rule of thumb for the Clarksville real estate market: if putting 20% down would drain your emergency fund, you’re probably trading one risk for another.

    What low-down-payment options change: PMI, MIP, and funding fees

    Mortgage insurance is protection for the lender when the down payment is small. Conventional uses PMI, FHA uses MIP (upfront + monthly), and VA generally has a one-time funding fee (unless exempt) but no monthly mortgage insurance.

    • Conventional 3–5% down: PMI until you reach enough equity.
    • FHA 3.5% down: MIP is structural to the loan.
    • VA 0% down: funding fee may apply, plus standard closing costs.

    For homes for sale near Fort Campbell, the real question isn’t which fee exists — it’s which loan puts you in the best long-term position. A Clarksville TN mortgage lender can run a side-by-side estimate.

    Local examples: how buyers in Montgomery County actually get to closing

    In Montgomery County TN homes, I see successful buyers using combinations like:

    • VA + seller concessions to reduce cash-to-close.
    • FHA + gift funds when family can help with part of the down payment.
    • Conventional 3% down + lender credits when the rate/credit tradeoff fits the budget.

    That last one is a big myth-buster: you can sometimes choose a slightly higher interest rate and receive lender credits to offset some closing costs. It’s not “free money”—it’s a trade—but it can help first-time homebuyer Clarksville buyers keep cash in reserve.

    Want the deeper math? See: [INTERNAL LINK: What Closing Costs Really Look Like in Clarksville TN] and [INTERNAL LINK: Seller Concessions & Lender Credits].

    A simple checklist to decide what down payment is right for you

    Use this quick decision list before you fixate on 20%:

    1. Pick a monthly payment range first (including taxes/insurance). Your payment is what you live with every month in Clarksville, not your down payment story.
    2. Set a safety buffer (emergency fund + moving costs). PCS moves to Fort Campbell and new-home setups always cost more than expected.
    3. Choose the loan program that fits your profile (VA, FHA, conventional). [INTERNAL LINK: Conventional vs. FHA vs. VA].
    4. Then choose a down payment amount that balances payment, cash-to-close, and your buffer.

    Bottom line: in the Clarksville housing market, the “best” down payment is the one that gets you into a home responsibly—with enough cash left to handle real life.


    Frequently Asked Questions

    Do I need 20% down to buy a house in Clarksville TN?

    No. Many buyers in Clarksville use lower down payment options. Conventional financing can start as low as 3% down, FHA can be as low as 3.5% down, and eligible VA borrowers often buy with 0% down. The right choice depends on your credit, income, and cash-to-close plan.

    What is the minimum down payment for an FHA loan?

    HUD states your down payment can be as low as 3.5% on an FHA loan (HUD (accessed 2026)). Your final requirement can vary by credit score and lender overlays, but 3.5% is the commonly referenced FHA minimum for qualified borrowers.

    Can I really buy a home near Fort Campbell with no money down?

    If you’re eligible for a VA loan and the purchase price isn’t above the appraised value, VA.gov explains a VA-backed purchase loan often offers no down payment (VA.gov (2026)). You still need to budget for closing costs and inspections.

    What’s the difference between down payment and cash-to-close?

    Down payment is the upfront equity you invest in the purchase price. Cash-to-close is the total you bring, including down payment, closing costs, prepaid taxes/insurance, and any required reserves. In Middle Tennessee, cash-to-close surprises are common, so plan for both numbers.

    Is a bigger down payment always better?

    Not always. A bigger down payment can lower your payment and reduce or eliminate PMI, but it can also drain savings. In Montgomery County, I’d rather see buyers keep an emergency fund and choose a sustainable payment than put every dollar into the down payment and feel house-poor.

    What is PMI and when do I have to pay it?

    PMI is private mortgage insurance and it’s commonly required on conventional loans when you put less than 20% down. It protects the lender, not you. The cost depends on credit score and down payment size, and it can usually be removed once you reach enough equity.

    What is MIP on an FHA loan?

    MIP is mortgage insurance premium on FHA loans. FHA loans typically include an upfront MIP amount and a monthly MIP component. It’s one reason FHA can be easier to qualify for with a smaller down payment, but you should compare FHA vs. conventional totals before deciding.

    Do VA loans have mortgage insurance?

    VA loans don’t require monthly PMI or MIP, which is a major advantage for Fort Campbell buyers. Many VA borrowers pay a one-time VA funding fee (unless exempt), plus normal closing costs. A side-by-side quote can show whether VA or conventional is cheaper over time.

    Can gift funds be used for a down payment in Tennessee?

    Often, yes. Many loan programs allow gift funds from acceptable donors if the gift is documented properly. The lender usually needs a gift letter and proof of transfer. If you’re buying in Clarksville or Nashville, plan early so the paper trail is clean before underwriting begins.

    How do I pick the right down payment amount for my situation?

    Start with your monthly comfort zone, then protect your cash reserves, then choose the loan program (VA/FHA/conventional) that fits. After that, pick a down payment that balances payment, cash-to-close, and your buffer. A mortgage pre-approval Clarksville review makes this decision much clearer.

    Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about [TOPIC], I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    Call or text: (931) 980-9764
    Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender | Fort Campbell VA loan specialist

    {

    “@context”: “https://schema.org”,

    “@graph”: [

    {

    “@type”: “Article”,

    “headline”: “Down Payment Myths: Why You Probably Don’t Need 20% in Middle Tennessee”,

    “author”: {

    “@type”: “Person”,

    “name”: “Kate Matties-Deiboldt”,

    “identifier”: “NMLS #18487”

    },

    “publisher”: {

    “@type”: “Organization”,

    “name”: “VanDyk Mortgage”

    },

    “datePublished”: “2026-06-06”,

    “about”: [

    “down payment”,

    “first-time homebuyer”,

    “Clarksville TN mortgage lender”,

    “Fort Campbell VA loan”

    ]

    },

    {

    “@type”: “FAQPage”,

    “mainEntity”: [

    {

    “@type”: “Question”,

    “name”: “Do I need 20% down to buy a house in Clarksville TN?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “No. Many buyers in Clarksville use lower down payment options.”

    }

    }

    ]

    },

    {

    “@type”: “LocalBusiness”,

    “name”: “VanDyk Mortgage — Kate Matties-Deiboldt (NMLS #18487)”,

    “telephone”: “+1-931-980-9764”,

    “email”: “Kate@JustCallKate.com”,

    “areaServed”: [“Clarksville”, “Fort Campbell”, “Montgomery County”, “Nashville”, “Middle Tennessee”]

    }

    ]

    }

  • Appraisal Came in Low? Here’s What to Do in Clarksville TN

    Appraisal Came in Low? Here’s What to Do in Clarksville TN

    When an appraisal comes in low, the licensed appraiser has valued the home below the agreed purchase price — and your mortgage will be based on the lower number, not the contract price. That shortfall must be resolved before closing. Buyers and sellers have five documented paths forward, and understanding them quickly can save the deal.

    According to CoreLogic data cited by AmeriSave (2024), 8.6% of appraisals came in below the contract price nationally. In Clarksville, the median sale-to-list ratio is 0.997, meaning homes sell right at list price on average — but 47.4% of sales still close below list, which is exactly where appraisal gaps emerge.

    TL;DR — Key Takeaways

    • A low appraisal is not a deal-killer — five options exist before anyone walks away.
    • CoreLogic (2024): 8.6% of appraisals nationally come in below contract price.
    • VA buyers near Fort Campbell have the Tidewater Initiative: 48 hours to submit supporting comps before the value is finalized.
    • A free ROV (Reconsideration of Value) is the fastest first move — file factual comps through your lender before spending money on a second appraisal.
    • Only 15% of buyers waived their appraisal contingency in January 2026 (NAR) — in today’s Clarksville housing market, keeping that protection is almost always the right call.

    Four Terms Every Clarksville Buyer Needs to Know

    An appraisal contingency is a clause in your purchase contract giving you the right to renegotiate or exit — with earnest money returned — if the appraised value falls below the contract price.

    An appraisal gap clause is a buyer-added provision stating you will pay a defined dollar amount above the appraised value — up to the contract price — if the appraisal falls short.

    An ROV, or Reconsideration of Value, is a formal written request — submitted through your lender — asking the appraiser to reconsider their conclusion based on comparable sales they may have missed. Fannie Mae updated its ROV policy in June 2025 to simplify documentation requirements.

    The VA Tidewater Initiative is a VA-specific early-warning process: when a VA appraiser believes the value will fall below the contract price, they pause and notify the lender, who then has two business days to submit additional comps.

    Your 5 Options When the Appraisal Comes in Low

    Option How It Works Pros Cons
    1. Renegotiate Price Buyer requests seller reduce price to appraised value. Cleanest solution; no extra cash needed. Seller may refuse.
    2. ROV / Tidewater Submit factual comps through lender (or invoke VA Tidewater 48-hr window). Free; no cash out-of-pocket; can fully close the gap. Not guaranteed; adds 1–2 weeks.
    3. Buyer Brings Cash (Full Gap) Buyer pays the entire difference at closing. Deal closes on original terms. Requires significant liquid reserves.
    4. Split the Gap Buyer and seller each cover a portion of the gap. Compromise keeps deal alive; common in Middle Tennessee. Seller must agree to reduce net proceeds.
    5. Walk Away Buyer invokes appraisal contingency and terminates contract. Full earnest money refund if contingency properly drafted. Buyer restarts search; seller loses time.

    How to Handle a Low Appraisal in 7 Steps

    1. Read the full appraisal report immediately. Check every comparable the appraiser used and look for factual errors — wrong square footage, missing rooms, or incorrect condition ratings are the fastest path to a correction.
    2. Determine your contingency status. Confirm whether your purchase contract includes an appraisal contingency and verify any gap clause limits you agreed to.
    3. Decide whether to pursue an ROV. An ROV works when you can identify two or more closed, arms-length sales within 90 days that the appraiser did not use. Submit through your lender — never contact the appraiser directly.
    4. Talk to your lender about the loan impact. Ask your Fort Campbell VA loan specialist or conventional lender exactly what the new loan amount and payment look like at the appraised value.
    5. Make a written counter-proposal to the seller. In the current Clarksville market, where inventory is growing, motivated sellers frequently prefer negotiating over re-listing.
    6. Order a second appraisal only as a last resort. A second appraisal typically costs $400–$600. Exhaust ROV options first.
    7. Make a go/no-go decision before your contingency deadline. ROV takes 5–10 business days; price negotiations take 2–5 days. Miss the deadline and you may lose the right to exit without forfeiting earnest money.

    Special Considerations for VA Loans Near Fort Campbell

    Military buyers using a VA loan near Fort Campbell face a key distinction: the VA Notice of Value (NOV) sets a hard ceiling. VA rules prohibit requiring a veteran to pay above the NOV. The VA Tidewater Initiative is the practical defense against a low NOV. Working with a Fort Campbell VA loan specialist who knows both the Tidewater timeline and the local Clarksville comp inventory is the most effective protection for PCS buyers.

    FAQ — Low Appraisals in Clarksville and Middle Tennessee

    How often do appraisals come in low in 2025–2026?

    Nationally, 8.6% of appraisals came in below contract price as of mid-2024, down from 10.7% the prior year. In Clarksville TN’s balanced market, low appraisals are less frequent than in hot bidding-war markets, but they do occur, especially on competitively priced homes near Fort Campbell.

    Does the VA appraisal work differently than a conventional appraisal?

    Yes. VA appraisals are assigned through the VA portal to a VA-approved fee appraiser. The resulting NOV is a hard ceiling. The VA Tidewater Initiative gives buyers and agents a 48-hour pre-finalization window to submit supporting comps. Conventional and FHA loans have no equivalent process.

    Can the buyer waive the appraisal contingency?

    Yes, but doing so transfers 100% of the gap risk to the buyer. Only 15% of buyers nationwide waived this contingency in January 2026. In Clarksville’s current inventory environment, waiving is rarely necessary. VA borrowers cannot be required to pay above the NOV.

    What is Tidewater on a VA appraisal?

    Tidewater is a VA-required early-warning step: when the VA appraiser suspects value will fall below contract price, they notify the lender before finalizing. All parties then have two business days to submit additional comps. It applies to all VA transactions, including every Fort Campbell purchase.

    Can the seller refuse to budge after a low appraisal?

    Yes. Sellers have no obligation to reduce price based on an appraisal. If a buyer holds an appraisal contingency, they can exit and recover earnest money. In Clarksville’s current market — where 47.4% of homes sell below list price — sellers who hold firm typically face a longer re-list.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
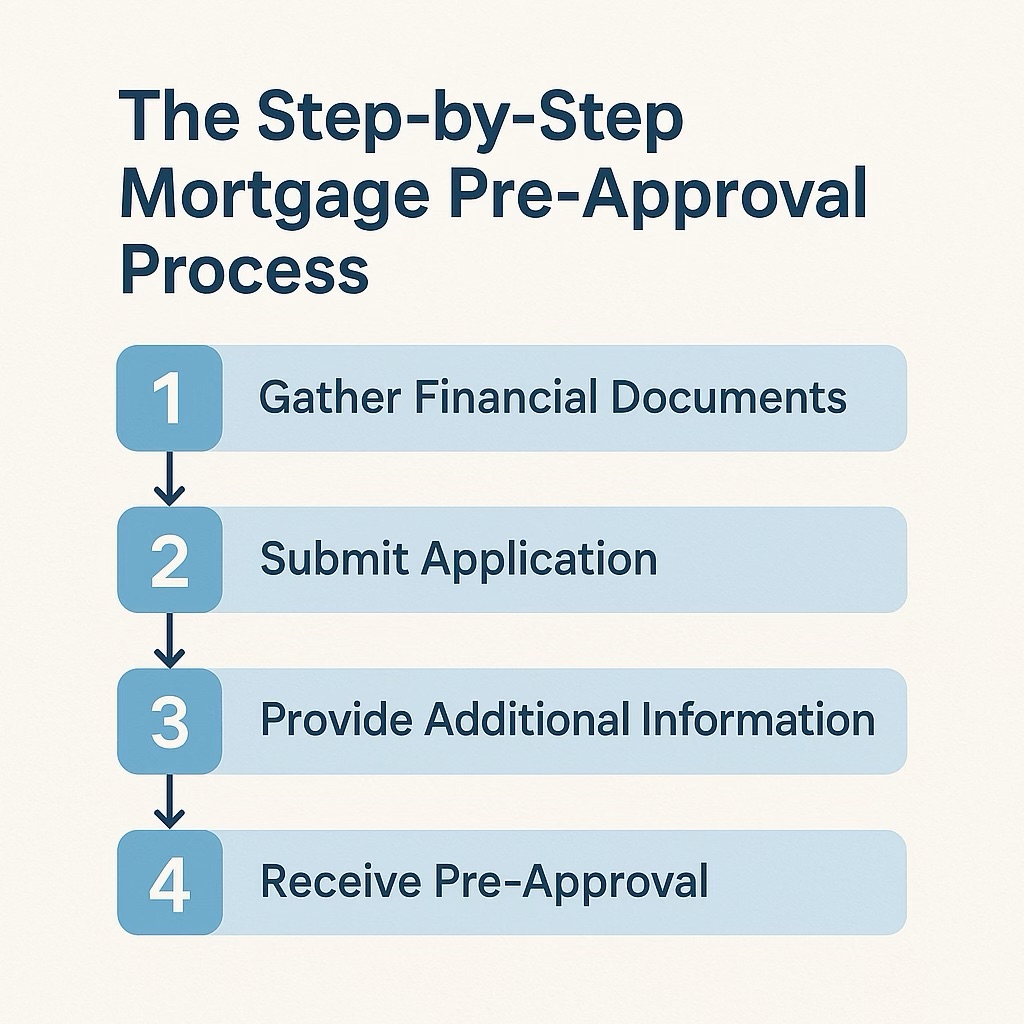
  • How Lenders Calculate Income for W-2 Borrowers (Overtime, Bonus, Commission)
  • Renting vs. Buying in Clarksville: The 2026 Break-Even Analysis

    Renting vs. Buying in Clarksville: The 2026 Break-Even Analysis

    If youre deciding whether to keep renting or buy a home in Clarksville, the break-even point usually comes down to three numbers: your monthly payment, how long youll stay, and your upfront cash-to-close. In 2026, higher rates mean buying can cost more month-to-monthbut owning may still win if you plan to stay long enough and you shop smart on closing costs.

    TL;DR Key takeaways

    • Break-even is a timeline, not a vibe: its the point where your total cost of owning becomes less than total cost of renting.
    • Rates matter twice: they raise your payment and slow down how fast you build equityso the stay long enough rule matters more in 2026.
    • Upfront cash can be negotiated: seller concessions and lender credits can shorten your break-even timeline.
    • Rent increases are real: steady rent growth can tip the math toward buying, even if your starting payment is higher.
    • The best answer is personal: your PCS timeline, savings, and credit score can change the result fast.

    What does break-even mean when youre comparing rent vs. buy?

    Break-even is the point in time when the total dollars youve spent on owning a home are equal to (or less than) the total dollars you would have spent renting. In plain English: its when buying stops being the more expensive option and starts being the better deal.

    Total cost is total cost. That means we count more than just the mortgage payment. We include upfront costs, ongoing costs, and what you get back when you sell.

    Equity is the portion of your home you truly own. Every principal payment increases equity, and (hopefully) price appreciation adds morebut selling costs reduce what you keep.

    The 2026 reality check: mortgage rates and affordability

    Mortgage rates are still a major factor in 2026. Freddie Macs weekly Primary Mortgage Market Survey (PMMS) showed the 30-year fixed-rate average was 6.48% as of June 4, 2026, which directly impacts monthly payments and the rent-vs-buy math.

    Affordability is also front-and-center. The National Association of REALTORSae explains that its Housing Affordability Index measures whether a typical family earns enough income to qualify for a mortgage on a typical home (NAR Housing Affordability Index (2026)). The point for you as a Clarksville buyer: your income and debts determine whether buying is comfortablenot just technically approved.

    And rents dont stand still. FRED tracks rent and owners equivalent rent measures inside the CPI, which helps explain why many renters feel increases over time even if they arent moving every year (FRED CPI Owners Equivalent Rent (updated May 2026)).

    The simple break-even formula (no finance degree required)

    Heres the clean way to think about it for Clarksville, Fort Campbell, and the Nashville commuter belt:

    • Renting cost Monthly rent renters insurance expected rent increases moving costs
    • Buying cost upfront cash-to-close monthly payment (PITI) maintenance HOA (if any) selling costs minus equity you build

    PITI is Principal, Interest, Taxes, and Insurance. Thats your all-in mortgage payment estimateand its what you should compare to rent, not just principal and interest.

    Opportunity cost is the return your money could have earned elsewhere. If you use savings for a down payment, that money cant sit in a high-yield account. Opportunity cost is real, but its often smaller than people fearespecially if buying stabilizes your housing costs in Montgomery County.

    A practical Clarksville break-even checklist (the numbers to gather)

    Gather these inputs for your Clarksville rent-vs-buy math; most take minutes to estimate.

    1. Your target monthly rent today (and what it typically increases each year)
    2. Your estimated purchase price for the neighborhoods youre actually considering
    3. Down payment amount (including whether youre using VA, FHA, USDA, or conventional)
    4. Interest rate estimate (based on your credit and the days market)
    5. Property taxes and homeowners insurance estimates
    6. HOA dues (if applicable)
    7. Maintenance budget (a conservative monthly number is better than a wish)
    8. Closing costs estimate (and whether you expect seller concessions)
    9. How long youll likely stay (2 years? 5 years? 7+?)
    10. Expected selling costs (agent fees, title fees, and potential repairs)

    If you want the shortcut: your likely stay timeline is usually the biggest lever for the rent-vs-buy decision in Middle Tennessee.

    Three scenarios that change the answer fast (especially near Fort Campbell)

    1) PCS timeline changes break-even. If you may move again in 2436 months, renting is often safer unless you plan to keep the home as a rental.

    2) Concessions shorten break-even. Seller credits or lender credits reduce cash-to-close, moving break-even earlier when guidelines and appraisal support it.

    3) Budget comfort matters. If a higher payment squeezes you, adjust price, loan type, or timing. [INTERNAL LINK: Debt-to-Income Ratio Explained]


    Frequently Asked Questions

    1) What is the break-even point for renting vs. buying?

    The break-even point is the time when your total cost of owning (upfront costs + monthly costs + selling costs minus equity) becomes equal to or less than the total cost of renting. Its measured in years, not feelings, and your timeline in Clarksville is a key input.

    2) Is buying still worth it in 2026 with rates in the 6% range?

    It can be, depending on how long youll stay and how you structure the deal. Higher rates raise payments, which can push break-even later, but negotiating seller concessions and choosing the right loan type can keep buying competitive in Montgomery County and Middle Tennessee.

    3) How long do I need to stay in a home for buying to make sense?

    Many buyers use a 5-year rule of thumb, but the right answer depends on your payment, upfront costs, and likely rent increases. If youre near Fort Campbell with a possible PCS, model shorter timelines (23 years) and a longer timeline (57 years).

    4) What costs do people forget when they compare rent to a mortgage payment?

    Commonly missed costs include property taxes, homeowners insurance, HOA dues, maintenance, and selling expenses. Also, a mortgage payment isnt the full picture; PITI is. A realistic Clarksville comparison needs the all-in payment plus a maintenance buffer.

    5) How do seller concessions affect the rent-vs-buy break-even?

    Seller concessions can reduce your cash-to-close by covering some closing costs, which lowers your upfront buying cost and often shortens the break-even timeline. Theyre powerful tools when the home appraises and the terms fit your loan guidelines.

    6) Does a bigger down payment always make buying a better deal?

    Not always. A larger down payment can lower your monthly payment and reduce interest paid, but it also ties up cash that could be used for reserves or repairs. Break-even is about total cost over time, so balance payment savings against flexibility and opportunity cost.

    7) What if renting is cheaper each monthshould I always keep renting?

    No. Monthly cost matters, but so does stability, lifestyle, and your plan. Rent can rise over time, while owning can stabilize your housing payment (except for taxes/insurance changes). The right Clarksville answer blends math with your timeline and comfort level.

    8) How does building equity actually work in the first few years?

    In the early years, more of your payment goes to interest than principal, so equity builds slower than many expect. Equity is your ownership stake, and it grows from principal paydown and any price appreciation. Selling costs reduce what you keep, which is why short timelines can be risky.

    9) If Im moving to Fort Campbell, should I rent first or buy right away?

    It depends on your orders timeline, how stable your assignment is, and whether youre comfortable owning during a future move. Some service members buy immediately with a VA loan; others rent first to learn the area. A quick break-even model plus your PCS risk helps decide.

    10) Can a lender help me run a real break-even analysis for Clarksville?

    Yes. A lender can build an all-in payment estimate with taxes, insurance, and loan options, then compare it to rent scenarios with realistic assumptions. My job is to be your clear guide through the mortgage processso you get a plan, not pressure, for Clarksville, Nashville commutes, and Montgomery County homes.


    About the author: Kate Matties-Deiboldt (NMLS #18487) is a mortgage lender with VanDyk Mortgage serving Clarksville, Fort Campbell, Montgomery County, Nashville, and Middle Tennessee. She helps first-time buyers, military families, and move-up buyers understand their options and make confident decisions.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about renting vs. buying in Clarksville, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    Call or text: (931) 980-9764
    Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender b7 Fort Campbell VA loan specialist

    {

    “@context”: “https://schema.org”,

    “@graph”: [

    {

    “@type”: “Article”,

    “headline”: “Renting vs. Buying in Clarksville: The 2026 Break-Even Analysis”,

    “datePublished”: “2026-06-05”,

    “dateModified”: “2026-06-05”,

    “author”: {

    “@type”: “Person”,

    “name”: “Kate Matties-Deiboldt”,

    “identifier”: “NMLS #18487”

    },

    “publisher”: {

    “@type”: “Organization”,

    “name”: “VanDyk Mortgage”

    },

    “about”: [

    “rent vs buy break-even”,

    “Clarksville TN homebuyer decision”,

    “Middle Tennessee housing costs”

    ]

    },

    {

    “@type”: “FAQPage”,

    “mainEntity”: [

    {

    “@type”: “Question”,

    “name”: “What is the break-even point for renting vs. buying?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “The break-even point is the time when your total cost of owning (upfront costs + monthly costs + selling costs minus equity) becomes equal to or less than the total cost of renting. Its measured in years, not feelings, and your timeline in Clarksville is a key input.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Is buying still worth it in 2026 with rates in the 6% range?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “It can be, depending on how long youll stay and how you structure the deal. Higher rates raise payments, which can push break-even later, but negotiating seller concessions and choosing the right loan type can keep buying competitive in Montgomery County and Middle Tennessee.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “How long do I need to stay in a home for buying to make sense?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Many buyers use a 5-year rule of thumb, but the right answer depends on your payment, upfront costs, and likely rent increases. If youre near Fort Campbell with a possible PCS, model shorter timelines (23 years) and a longer timeline (57 years).”

    }

    },

    {

    “@type”: “Question”,

    “name”: “What costs do people forget when they compare rent to a mortgage payment?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Commonly missed costs include property taxes, homeowners insurance, HOA dues, maintenance, and selling expenses. Also, a mortgage payment isnt the full picture; PITI is. A realistic Clarksville comparison needs the all-in payment plus a maintenance buffer.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “How do seller concessions affect the rent-vs-buy break-even?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Seller concessions can reduce your cash-to-close by covering some closing costs, which lowers your upfront buying cost and often shortens the break-even timeline. Theyre powerful tools when the home appraises and the terms fit your loan guidelines.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Does a bigger down payment always make buying a better deal?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Not always. A larger down payment can lower your monthly payment and reduce interest paid, but it also ties up cash that could be used for reserves or repairs. Break-even is about total cost over time, so balance payment savings against flexibility and opportunity cost.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “What if renting is cheaper each monthshould I always keep renting?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “No. Monthly cost matters, but so does stability, lifestyle, and your plan. Rent can rise over time, while owning can stabilize your housing payment (except for taxes/insurance changes). The right Clarksville answer blends math with your timeline and comfort level.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “How does building equity actually work in the first few years?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “In the early years, more of your payment goes to interest than principal, so equity builds slower than many expect. Equity is your ownership stake, and it grows from principal paydown and any price appreciation. Selling costs reduce what you keep, which is why short timelines can be risky.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “If Im moving to Fort Campbell, should I rent first or buy right away?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “It depends on your orders timeline, how stable your assignment is, and whether youre comfortable owning during a future move. Some service members buy immediately with a VA loan; others rent first to learn the area. A quick break-even model plus your PCS risk helps decide.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Can a lender help me run a real break-even analysis for Clarksville?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Yes. A lender can build an all-in payment estimate with taxes, insurance, and loan options, then compare it to rent scenarios with realistic assumptions. My job is to be your clear guide through the mortgage processso you get a plan, not pressure, for Clarksville, Nashville commutes, and Montgomery County homes.”

    }

    }

    ]

    },

    {

    “@type”: “BreadcrumbList”,

    “itemListElement”: [

    {

    “@type”: “ListItem”,

    “position”: 1,

    “name”: “Home”,

    “item”: “https://thedealdoctor.blog/”

    },

    {

    “@type”: “ListItem”,

    “position”: 2,

    “name”: “Homebuyer Education”,

    “item”: “https://thedealdoctor.blog/homebuyer-education/”

    },

    {

    “@type”: “ListItem”,

    “position”: 3,

    “name”: “Renting vs. Buying in Clarksville: The 2026 Break-Even Analysis”

    }

    ]

    },

    {

    “@type”: “LocalBusiness”,

    “name”: “VanDyk Mortgage Kate Matties-Deiboldt”,

    “telephone”: “+1-931-980-9764”,

    “email”: “Kate@JustCallKate.com”,

    “areaServed”: [

    “Clarksville”,

    “Fort Campbell”,

    “Montgomery County”,

    “Nashville”,

    “Middle Tennessee”

    ],

    “url”: “https://thedealdoctor.blog/”

    },

    {

    “@type”: “SpeakableSpecification”,

    “xpath”: [

    “/html/head/title”,

    “/html/body//h1”,

    “/html/body//div[@class=’key-takeaways’]”

    ]

    },

    {

    “@type”: “HowTo”,

    “name”: “How to estimate your rent vs. buy break-even timeline”,

    “step”: [

    {

    “@type”: “HowToStep”,

    “name”: “Collect your rent and purchase assumptions”,

    “text”: “Gather rent, expected rent increases, purchase price, down payment, estimated rate, taxes, insurance, HOA, maintenance, and closing-cost strategy.”

    },

    {

    “@type”: “HowToStep”,

    “name”: “Estimate your all-in monthly owning cost (PITI + other)”,

    “text”: “Compare your all-in owning estimate to rent, and include a maintenance buffer.”

    },

    {

    “@type”: “HowToStep”,

    “name”: “Model multiple stay-length scenarios”,

    “text”: “Run 2-year, 3-year, and 57-year scenarios (especially for Fort Campbell PCS risk) and compare total costs.”

    },

    {

    “@type”: “HowToStep”,

    “name”: “Stress-test for selling costs”,

    “text”: “Include typical selling costs and a conservative estimate for appreciation to avoid overly rosy results.”

    }

    ]

    }

    ]

    }

  • Down Payment Myths: Why You Probably Don’t Need 20% in Middle Tennessee

    Down Payment Myths: Why You Probably Don’t Need 20% in Middle Tennessee

    If you’re shopping for a home in Clarksville or around Fort Campbell, you probably keep hearing “You need 20% down.” You usually don’t — most buyers use a smaller down payment by pairing the right loan program with a realistic cash-to-close plan, and start building equity in a Montgomery County home sooner.

    • 20% down is a myth for many buyers. Conventional loans can go as low as 3% down, FHA as low as 3.5% down, and VA often allows 0% down for eligible borrowers.
    • Smaller down = different tradeoffs. You may pay mortgage insurance (PMI/MIP) or a VA funding fee—but you keep more cash on hand.
    • Cash-to-close ≠ down payment. Closing costs and prepaid items can matter just as much.
    • Local strategy matters. The strongest plan in the Clarksville housing market is one you can sustain month-to-month — not one that empties savings.
    • You can combine help. Gift funds and assistance programs can cover part or all of the down payment with documentation.

    The myth: “You must put 20% down”

    A down payment is the portion of the purchase price you pay upfront — your initial equity on day one. The 20% rule exists only to avoid mortgage insurance on most conventional loans; it’s a strategy, not a requirement. Freddie Mac (2025) notes the typical buyer puts down 5–20%, and some programs allow as little as 3%.

    Cash-to-close is the total amount you bring to closing — down payment plus closing costs, prepaid taxes/insurance, and reserves. Many first-time homebuyer Clarksville plans fail because buyers save the down payment but forget the rest.

    Reality check: what common loan programs really require

    A conventional loan is a mortgage not insured by the federal government. For qualified buyers, conventional programs can start at 3% down.

    An FHA loan is insured by the Federal Housing Administration. HUD allows a down payment as low as 3.5% (HUD (2026)).

    A VA loan is a benefit for eligible Veterans, active-duty service members, and some surviving spouses. VA.gov (2026) explains a VA-backed purchase loan often offers no down payment and no monthly PMI/MIP — why Fort Campbell VA loan questions come up constantly with military relocation Clarksville families.

    Why some people still push 20% (and when it makes sense)

    Here’s the fair point: 20% down can reduce your payment and may help you avoid PMI on a conventional loan. If you’re moving from Nashville to Clarksville with a big down payment from a home sale, 20% can be a smart, clean option.

    But in Middle Tennessee, where rents are not exactly cheap, waiting to save 20% can be expensive in its own way. The goal is not “the biggest down payment.” The goal is ownership with a payment you can comfortably afford while keeping a safety buffer.

    My rule of thumb for the Clarksville real estate market: if putting 20% down would drain your emergency fund, you’re probably trading one risk for another.

    What low-down-payment options change: PMI, MIP, and funding fees

    Mortgage insurance is protection for the lender when the down payment is small. Conventional uses PMI, FHA uses MIP (upfront + monthly), and VA generally has a one-time funding fee (unless exempt) but no monthly mortgage insurance.

    • Conventional 3–5% down: PMI until you reach enough equity.
    • FHA 3.5% down: MIP is structural to the loan.
    • VA 0% down: funding fee may apply, plus standard closing costs.

    For homes for sale near Fort Campbell, the real question isn’t which fee exists — it’s which loan puts you in the best long-term position. A Clarksville TN mortgage lender can run a side-by-side estimate.

    Local examples: how buyers in Montgomery County actually get to closing

    In Montgomery County TN homes, I see successful buyers using combinations like:

    • VA + seller concessions to reduce cash-to-close.
    • FHA + gift funds when family can help with part of the down payment.
    • Conventional 3% down + lender credits when the rate/credit tradeoff fits the budget.

    That last one is a big myth-buster: you can sometimes choose a slightly higher interest rate and receive lender credits to offset some closing costs. It’s not “free money”—it’s a trade—but it can help first-time homebuyer Clarksville buyers keep cash in reserve.

    Want the deeper math? See: [INTERNAL LINK: What Closing Costs Really Look Like in Clarksville TN] and [INTERNAL LINK: Seller Concessions & Lender Credits].

    A simple checklist to decide what down payment is right for you

    Use this quick decision list before you fixate on 20%:

    1. Pick a monthly payment range first (including taxes/insurance). Your payment is what you live with every month in Clarksville, not your down payment story.
    2. Set a safety buffer (emergency fund + moving costs). PCS moves to Fort Campbell and new-home setups always cost more than expected.
    3. Choose the loan program that fits your profile (VA, FHA, conventional). [INTERNAL LINK: Conventional vs. FHA vs. VA].
    4. Then choose a down payment amount that balances payment, cash-to-close, and your buffer.

    Bottom line: in the Clarksville housing market, the “best” down payment is the one that gets you into a home responsibly—with enough cash left to handle real life.


    Frequently Asked Questions

    Do I need 20% down to buy a house in Clarksville TN?

    No. Many buyers in Clarksville use lower down payment options. Conventional financing can start as low as 3% down, FHA can be as low as 3.5% down, and eligible VA borrowers often buy with 0% down. The right choice depends on your credit, income, and cash-to-close plan.

    What is the minimum down payment for an FHA loan?

    HUD states your down payment can be as low as 3.5% on an FHA loan (HUD (accessed 2026)). Your final requirement can vary by credit score and lender overlays, but 3.5% is the commonly referenced FHA minimum for qualified borrowers.

    Can I really buy a home near Fort Campbell with no money down?

    If you’re eligible for a VA loan and the purchase price isn’t above the appraised value, VA.gov explains a VA-backed purchase loan often offers no down payment (VA.gov (2026)). You still need to budget for closing costs and inspections.

    What’s the difference between down payment and cash-to-close?

    Down payment is the upfront equity you invest in the purchase price. Cash-to-close is the total you bring, including down payment, closing costs, prepaid taxes/insurance, and any required reserves. In Middle Tennessee, cash-to-close surprises are common, so plan for both numbers.

    Is a bigger down payment always better?

    Not always. A bigger down payment can lower your payment and reduce or eliminate PMI, but it can also drain savings. In Montgomery County, I’d rather see buyers keep an emergency fund and choose a sustainable payment than put every dollar into the down payment and feel house-poor.

    What is PMI and when do I have to pay it?

    PMI is private mortgage insurance and it’s commonly required on conventional loans when you put less than 20% down. It protects the lender, not you. The cost depends on credit score and down payment size, and it can usually be removed once you reach enough equity.

    What is MIP on an FHA loan?

    MIP is mortgage insurance premium on FHA loans. FHA loans typically include an upfront MIP amount and a monthly MIP component. It’s one reason FHA can be easier to qualify for with a smaller down payment, but you should compare FHA vs. conventional totals before deciding.

    Do VA loans have mortgage insurance?

    VA loans don’t require monthly PMI or MIP, which is a major advantage for Fort Campbell buyers. Many VA borrowers pay a one-time VA funding fee (unless exempt), plus normal closing costs. A side-by-side quote can show whether VA or conventional is cheaper over time.

    Can gift funds be used for a down payment in Tennessee?

    Often, yes. Many loan programs allow gift funds from acceptable donors if the gift is documented properly. The lender usually needs a gift letter and proof of transfer. If you’re buying in Clarksville or Nashville, plan early so the paper trail is clean before underwriting begins.

    How do I pick the right down payment amount for my situation?

    Start with your monthly comfort zone, then protect your cash reserves, then choose the loan program (VA/FHA/conventional) that fits. After that, pick a down payment that balances payment, cash-to-close, and your buffer. A mortgage pre-approval Clarksville review makes this decision much clearer.

    Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about [TOPIC], I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    Call or text: (931) 980-9764
    Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender | Fort Campbell VA loan specialist

    {

    “@context”: “https://schema.org”,

    “@graph”: [

    {

    “@type”: “Article”,

    “headline”: “Down Payment Myths: Why You Probably Don’t Need 20% in Middle Tennessee”,

    “author”: {

    “@type”: “Person”,

    “name”: “Kate Matties-Deiboldt”,

    “identifier”: “NMLS #18487”

    },

    “publisher”: {

    “@type”: “Organization”,

    “name”: “VanDyk Mortgage”

    },

    “datePublished”: “2026-06-06”,

    “about”: [

    “down payment”,

    “first-time homebuyer”,

    “Clarksville TN mortgage lender”,

    “Fort Campbell VA loan”

    ]

    },

    {

    “@type”: “FAQPage”,

    “mainEntity”: [

    {

    “@type”: “Question”,

    “name”: “Do I need 20% down to buy a house in Clarksville TN?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “No. Many buyers in Clarksville use lower down payment options.”

    }

    }

    ]

    },

    {

    “@type”: “LocalBusiness”,

    “name”: “VanDyk Mortgage — Kate Matties-Deiboldt (NMLS #18487)”,

    “telephone”: “+1-931-980-9764”,

    “email”: “Kate@JustCallKate.com”,

    “areaServed”: [“Clarksville”, “Fort Campbell”, “Montgomery County”, “Nashville”, “Middle Tennessee”]

    }

    ]

    }

  • VA Loans 101: A Complete Guide for Fort Campbell Service Members

    VA Loans 101: A Complete Guide for Fort Campbell Service Members

    If you’re stationed at Fort Campbell and want to buy in Clarksville or Montgomery County, a VA loan can be a strong option: $0 down is possible in many cases and there’s no monthly mortgage insurance. The key is qualifying cleanly and budgeting for the real cash-to-close items so your PCS move stays stress-free.

    A VA loan is a mortgage backed by the U.S. Department of Veterans Affairs that’s designed to help eligible service members, Veterans, and some surviving spouses buy or refinance a primary residence. A VA funding fee is a one-time charge that helps keep the program running and can usually be financed into the loan. Residual income is a VA guideline that looks at your remaining monthly income after major debts—an extra safety check that’s especially helpful for military families managing PCS costs.

    • VA loans are built for primary homes—great for buying near Fort Campbell, not for investment properties.
    • Many buyers can do $0 down, but you still need cash for appraisal/inspections and any negotiated costs.
    • The VA funding fee is usually 2.15% for first-time use with less than 5% down (VA.gov chart effective April 7, 2023).
    • Rates change weekly; as of June 4, 2026, Freddie Mac’s PMMS average 30-year fixed rate was 6.48%.
    • Start with a strong Certificate of Eligibility (COE) and a real pre-approval before touring homes in Clarksville TN.

    Who a VA loan is for (and what it can buy)

    A VA loan is meant for a primary residence—where you’ll live most of the year. That’s perfect for military relocation Clarksville moves and families who want homes for sale near Fort Campbell, but it means you generally can’t use a VA loan to buy a pure rental property.

    In Middle Tennessee, I often see VA buyers purchasing single-family homes, townhomes, and some approved condos. You can also use a VA loan to refinance an existing mortgage, including a streamline refinance (IRRRL) when it makes sense.

    Eligibility basics: COE, entitlement, and occupancy

    A Certificate of Eligibility (COE) is the VA document that confirms you’re eligible for the benefit and shows available entitlement. Don’t let the acronyms intimidate you—this is one of the first things we verify during mortgage pre-approval Clarksville planning.

    Occupancy matters: typically you must intend to move in soon after closing. For many Fort Campbell families, that lines up naturally with PCS timing, school schedules, and lease end dates.

    Down payment, closing costs, and the VA funding fee (what to budget)

    $0 down is possible, but budget for earnest money, inspection, and appraisal-related costs. In the Clarksville housing market, seller concessions can sometimes help with allowable closing costs—especially if a home has been sitting.

    Then there’s the VA funding fee. According to VA.gov (effective April 7, 2023), first-time VA loan use with less than 5% down has a 2.15% funding fee, while subsequent use with less than 5% down is 3.3%. Some borrowers are exempt (for example, certain service-connected disability scenarios) as outlined by VA.gov.

    Good news for planning: the funding fee can usually be financed into the loan amount instead of paid out of pocket at closing. Also, VA News notes that borrowers can deduct funding fees starting in 2026 (VA News (2026))—talk with a tax professional about your situation.

    How VA loans qualify you: credit, DTI, and residual income

    Most people know credit score matters, but VA underwriting is more holistic than a single number. Debt-to-income (DTI) is your monthly debt payments divided by your gross monthly income, and it helps lenders measure affordability. VA guidelines also emphasize residual income, which is the money you have left each month after major obligations. That matters for active-duty households who may be juggling childcare, car payments, and the costs of setting up a new home in Montgomery County.

    Rates and payment planning for 2026 buyers

    Mortgage rates can shift quickly. For context, the 30-year fixed-rate mortgage averaged 6.48% as of June 4, 2026 per Freddie Mac PMMS (2026), and the same 6.48% observation is posted on FRED (2026). Your personal rate depends on credit, loan details, and the day you lock.

    A step-by-step VA loan game plan for Fort Campbell buyers

    1. Confirm eligibility: COE + a quick benefit review.
    2. Build a real budget: target payment, cash to close, and a repair/PCS buffer.
    3. Get fully pre-approved: not just pre-qualified—income, assets, and credit reviewed.
    4. Shop with strategy: prioritize homes that fit VA appraisal and condition standards.
    5. Negotiate smart: consider seller concessions and closing timelines that match your move.
    6. Lock and close: lock rate, finalize insurance, and plan your move-in date.

    Related reading: [INTERNAL LINK: VA loan myths] · [INTERNAL LINK: Home inspection basics] · [INTERNAL LINK: How to get pre-approved]

    VA Loan FAQs (Fort Campbell + Clarksville)

    1) Do VA loans require a down payment?

    Often, no. Many eligible buyers can purchase with $0 down, which is why VA loans are popular for Fort Campbell service members relocating to Clarksville. You still need to plan for inspections, appraisal-related costs, and any cash needed if the appraisal comes in low or you choose to pay points.

    2) What is the VA funding fee, and how much is it?

    The VA funding fee is a one-time fee that helps fund the program. VA.gov’s chart (effective April 7, 2023) shows 2.15% for first-time use with less than 5% down and 3.3% for subsequent use with less than 5% down. Some borrowers are exempt, such as certain disability situations.

    3) Can I roll the funding fee into my loan?

    In many cases, yes. Financing the funding fee can reduce your upfront cash to close, which helps if you’re managing PCS expenses or setting up a new household in Montgomery County. We’ll run the numbers both ways so you understand the long-term cost versus the short-term cash benefit.

    4) Are VA loan interest rates always lower?

    Not always, but VA loans can be very competitive. Rates move daily and depend on your credit profile, loan size, and lock timing. For general context, Freddie Mac’s PMMS reported an average 30-year fixed rate of 6.48% as of June 4, 2026—your actual offer may differ.

    5) What credit score do I need for a VA loan?

    The VA doesn’t set a single minimum score, but lenders do. The best approach is to start with a pre-approval so we can see your full picture—score, history, and debts—and build a plan. If you’re buying in Clarksville, small credit tweaks can meaningfully improve payment options.

    6) What is residual income and why does the VA care?

    Residual income is the money you have left each month after major obligations like housing, taxes, and recurring debts. The VA uses it as a safety check to help ensure you can still handle everyday life costs. It’s especially helpful for Fort Campbell families balancing childcare and transportation.

    7) Can I use a VA loan to buy a condo in Nashville or Middle Tennessee?

    Sometimes. The condo must meet VA approval requirements, and it still must be your primary residence. If you’re considering Nashville now but may later move closer to Fort Campbell, we’ll talk through occupancy plans and the best way to use your benefit without creating problems later.

    8) What’s the VA appraisal, and can it affect my offer?

    The VA appraisal checks value and also flags certain property condition issues. In a competitive Clarksville real estate market, this can influence what homes are realistic choices and how you negotiate repairs. A strong pre-approval and a smart offer strategy help keep the deal on track.

    9) Can a seller pay my closing costs on a VA loan?

    Yes, within VA rules and based on negotiation. Seller concessions can be helpful in the Clarksville housing market when the numbers are tight. The key is structuring the contract correctly so you’re not surprised late in the process and so your cash-to-close matches your plan.

    10) How do I start a VA loan pre-approval if I’m active duty at Fort Campbell?

    Start with a quick call to review eligibility, COE status, income, and your target payment. Then we’ll collect pay, LES, and basic documents and issue a real pre-approval you can shop with in Montgomery County or Clarksville. If you’re on a tight PCS timeline, we’ll build a closing plan from day one.

    By Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about VA loans in Clarksville and Fort Campbell, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

    {

    “@context”: “https://schema.org”,

    “@graph”: [

    {

    “@type”: “Article”,

    “headline”: “VA Loans 101: A Complete Guide for Fort Campbell Service Members”,

    “description”: “A practical VA loan guide for Fort Campbell service members buying in Clarksville and Montgomery County, including funding fees, eligibility, and FAQs.”,

    “author”: {

    “@type”: “Person”,

    “name”: “Kate Matties-Deiboldt”,

    “identifier”: “NMLS #18487”

    },

    “publisher”: {

    “@type”: “Organization”,

    “name”: “VanDyk Mortgage”

    },

    “datePublished”: “2026-06-08”,

    “dateModified”: “2026-06-08”,

    “about”: [

    “VA loan”,

    “Fort Campbell”,

    “Clarksville TN”,

    “Montgomery County TN”,

    “Middle Tennessee”

    ],

    “mainEntityOfPage”: {

    “@type”: “WebPage”,

    “@id”: “https://thedealdoctor.blog/va-loans-101-fort-campbell/”

    }

    },

    {

    “@type”: “FAQPage”,

    “mainEntity”: [

    {

    “@type”: “Question”,

    “name”: “Do VA loans require a down payment?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “Often, no. Many eligible buyers can purchase with $0 down, which is why VA loans are popular for Fort Campbell service members relocating to Clarksville. You still need to plan for inspections, appraisal-related costs, and any cash needed if the appraisal comes in low or you choose to pay points.” }

    },

    {

    “@type”: “Question”,

    “name”: “What is the VA funding fee, and how much is it?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “The VA funding fee is a one-time fee that helps fund the program. VA.gov’s chart (effective April 7, 2023) shows 2.15% for first-time use with less than 5% down and 3.3% for subsequent use with less than 5% down. Some borrowers are exempt, such as certain disability situations.” }

    },

    {

    “@type”: “Question”,

    “name”: “Can I roll the funding fee into my loan?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “In many cases, yes. Financing the funding fee can reduce your upfront cash to close, which helps if you’re managing PCS expenses or setting up a new household in Montgomery County. We’ll run the numbers both ways so you understand the long-term cost versus the short-term cash benefit.” }

    },

    {

    “@type”: “Question”,

    “name”: “Are VA loan interest rates always lower?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “Not always, but VA loans can be very competitive. Rates move daily and depend on your credit profile, loan size, and lock timing. For general context, Freddie Mac’s PMMS reported an average 30-year fixed rate of 6.48% as of June 4, 2026—your actual offer may differ.” }

    },

    {

    “@type”: “Question”,

    “name”: “What credit score do I need for a VA loan?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “The VA doesn’t set a single minimum score, but lenders do. The best approach is to start with a pre-approval so we can see your full picture—score, history, and debts—and build a plan. If you’re buying in Clarksville, small credit tweaks can meaningfully improve payment options.” }

    },

    {

    “@type”: “Question”,

    “name”: “What is residual income and why does the VA care?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “Residual income is the money you have left each month after major obligations like housing, taxes, and recurring debts. The VA uses it as a safety check to help ensure you can still handle everyday life costs. It’s especially helpful for Fort Campbell families balancing childcare and transportation.” }

    },

    {

    “@type”: “Question”,

    “name”: “Can I use a VA loan to buy a condo in Nashville or Middle Tennessee?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “Sometimes. The condo must meet VA approval requirements, and it still must be your primary residence. If you’re considering Nashville now but may later move closer to Fort Campbell, we’ll talk through occupancy plans and the best way to use your benefit without creating problems later.” }

    },

    {

    “@type”: “Question”,

    “name”: “What’s the VA appraisal, and can it affect my offer?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “The VA appraisal checks value and also flags certain property condition issues. In a competitive Clarksville real estate market, this can influence what homes are realistic choices and how you negotiate repairs. A strong pre-approval and a smart offer strategy help keep the deal on track.” }

    },

    {

    “@type”: “Question”,

    “name”: “Can a seller pay my closing costs on a VA loan?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “Yes, within VA rules and based on negotiation. Seller concessions can be helpful in the Clarksville housing market when the numbers are tight. The key is structuring the contract correctly so you’re not surprised late in the process and so your cash-to-close matches your plan.” }

    },

    {

    “@type”: “Question”,

    “name”: “How do I start a VA loan pre-approval if I’m active duty at Fort Campbell?”,

    “acceptedAnswer”: { “@type”: “Answer”, “text”: “Start with a quick call to review eligibility, COE status, income, and your target payment. Then we’ll collect pay, LES, and basic documents and issue a real pre-approval you can shop with in Montgomery County or Clarksville. If you’re on a tight PCS timeline, we’ll build a closing plan from day one.” }

    }

    ]

    },

    {

    “@type”: “BreadcrumbList”,

    “itemListElement”: [

    { “@type”: “ListItem”, “position”: 1, “name”: “Home”, “item”: “https://thedealdoctor.blog/” },

    { “@type”: “ListItem”, “position”: 2, “name”: “Homebuying”, “item”: “https://thedealdoctor.blog/category/homebuying/” },

    { “@type”: “ListItem”, “position”: 3, “name”: “VA Loans 101: A Complete Guide for Fort Campbell Service Members”, “item”: “https://thedealdoctor.blog/va-loans-101-fort-campbell/” }

    ]

    },

    {

    “@type”: “LocalBusiness”,

    “name”: “VanDyk Mortgage — Kate Matties-Deiboldt (NMLS #18487)”,

    “email”: “Kate@JustCallKate.com”,

    “telephone”: “+1-931-980-9764”,

    “areaServed”: [“Clarksville”, “Fort Campbell”, “Montgomery County”, “Nashville”, “Middle Tennessee”],

    “url”: “https://thedealdoctor.blog/”,

    “sameAs”: []

    },

    {

    “@type”: “SpeakableSpecification”,

    “xpath”: [

    “/html/head/title”,

    “//article/h1”,

    “//ul[contains(@class,’key-takeaways’)]”

    ]

    },

    {

    “@type”: “HowTo”,

    “name”: “How to get a VA loan near Fort Campbell”,

    “step”: [

    { “@type”: “HowToStep”, “name”: “Confirm eligibility”, “text”: “Pull your COE and review entitlement.” },

    { “@type”: “HowToStep”, “name”: “Set budget”, “text”: “Decide a target payment and cash-to-close plan.” },

    { “@type”: “HowToStep”, “name”: “Get pre-approved”, “text”: “Verify income, assets, and credit for a true pre-approval.” },

    { “@type”: “HowToStep”, “name”: “Shop and negotiate”, “text”: “Choose homes that fit VA appraisal/condition standards and negotiate smart concessions.” },

    { “@type”: “HowToStep”, “name”: “Lock and close”, “text”: “Lock your rate and plan a closing timeline that matches your PCS.” }

    ]

    }

    ]

    }

  • The VA Funding Fee Explained (and When It’s Waived)

    The VA Funding Fee Explained (and When Its Waived)

    If youre using a VA loan, the VA funding fee is a one-time VA charge that helps keep the program running for future Veterans. It can affect the monthly payment.

    Good news: many borrowers dont pay it.

    TL;DR Key takeaways

    • The VA funding fee is a percentage of your loan amount, not the homes purchase price.
    • For most first-time VA purchase loans, the fee is 2.15% with less than 5% down (VA.gov 2026).
    • Funding fee exemptions are common for borrowers receiving VA disability compensation and certain Purple Heart recipients (VA.gov 2026).
    • You can usually finance the fee into the mortgage (higher payment) or pay it in cash at closing (lower payment).

    VA funding fee is a one-time upfront fee on many VA loans. Financing the funding fee is adding it to your loan balance instead of paying cash at closing. And an exemption is a rule that makes you eligible to pay $0 based on your status.

    1) What the VA funding fee is (in plain English)

    VA loans often allow $0 down. The tradeoff is the funding fee, calculated as a percentage of your loan amount based on loan type, down payment, and first vs. repeat use (VA.gov 2026).

    2) VA funding fee rates: the numbers most buyers need

    For the most common scenario around Fort Campbella purchase loanVA.gov shows these funding fee rates (effective April 7, 2023):

    • First use, less than 5% down: 2.15%
    • First use, 5%+ down: 1.5%
    • First use, 10%+ down: 1.25%
    • After first use, less than 5% down: 3.3%
    • After first use, 5%+ down: 1.5%
    • After first use, 10%+ down: 1.25%

    Those percentages apply to the loan amount. That matters when youre budgeting cash-to-close in Clarksville TN.

    3) A quick example: what 2.15% looks like in dollars

    Example: a $350,000 loan amount at 2.15% is a $7,525 fee. If financed, it increases your balance to about $357,525.

    Scenario Loan amount Funding fee % Funding fee $ If financed, new balance
    $350,000 purchase, first VA use, $0 down $350,000 2.15% $7,525 $357,525

    4) When the VA funding fee is waived (the $0 situations)

    VA.gov lists several situations where you dont have to pay the funding fee at all, including if youre receiving VA compensation for a service-connected disability (or eligible to receive it but drawing retirement/active-duty pay instead), certain surviving spouses receiving DIC, certain service members with a proposed/memorandum rating before closing, and Purple Heart recipients who provide evidence before closing (VA.gov 2026).

    This is one of the biggest reasons I always ask Fort Campbell buyers to share their VA disability and award documentation early. If youre exempt, it can reduce your loan balance and payment.

    5) How the funding fee interacts with rates and affordability

    Even a fee thats only a couple percent matters when mortgage rates are higher. Freddie Macs Primary Mortgage Market Survey showed the average 30-year fixed rate at 6.48% as of June 4, 2026 (Freddie Mac PMMS 2026), and that same weekly rate is published on FREDs MORTGAGE30US series (FRED 2026). A higher balance can mean more interest over time.

    If youre house-hunting in Montgomery County TN homes (or commuting toward Nashville), a clean comparison is: (1) payment with the fee financed, (2) payment with the fee paid in cash, and (3) payment if you qualify for a waiver.

    6) Practical ways Clarksville-area buyers can reduce the fees impact

    • Confirm exemption status early: If youre eligible, paying $0 is the best discount.
    • Consider a modest down payment: Hitting 5% can reduce the fee from 2.15% to 1.5% for first-time use (VA.gov 2026).
    • Budget cash-to-close strategically: Financing preserves cash; paying it can lower the payment.
    • Compare the whole package: VA vs. FHA vs. conventional is more than just rate; its rate + MI + upfront fees + appraisal/underwriting rules. [INTERNAL LINK: Conventional vs. FHA vs. VA]
    • Get a pre-approval that models scenarios: A strong mortgage pre-approval in Clarksville helps you write an offer that fits your payment comfort zone. [INTERNAL LINK: Step-by-Step Mortgage Pre-Approval Process]

    Frequently Asked Questions

    1) Can I roll the VA funding fee into my loan?

    Usually, yes. Most buyers finance it by adding it to the loan amount, which raises your balance and payment. If cash is tight, financing may help; paying it can lower the payment. Well compare both.

    2) Is the funding fee the same as mortgage insurance?

    No. Mortgage insurance is usually a monthly charge on many conventional and FHA loans. The VA funding fee is typically a one-time upfront fee on many VA loans. Many Fort Campbell buyers still choose VA because it can avoid monthly MI.

    3) How do I know if my funding fee is waived?

    In many cases, youre exempt if youre receiving VA compensation for a service-connected disability, or you meet other VA-listed criteria like certain surviving spouse benefits or Purple Heart evidence before closing (VA.gov 2026). Ill help you confirm it early.

    4) Whats the funding fee for a first-time VA buyer with $0 down?

    VA.gov lists 2.15% for first-use purchase loans with less than 5% down (effective April 7, 2023). On a $300,000 loan amount, thats $6,450. Your exact fee depends on your final loan amount.

    5) What if Ive used my VA loan benefit before?

    If youve used VA before and are using it again, VA.gov shows it can be higherfor example, 3.3% for subsequent use with less than 5% down (effective April 7, 2023). A 5% or 10% down payment can reduce the fee.

    6) Does a bigger down payment always reduce the fee?

    For purchase and construction loans, yes5% or 10% down lowers the fee (VA.gov 2026). But some refinance types have a fixed fee that doesnt change with down payment. Loan type matters.

    7) Do I pay the funding fee on a VA refinance?

    Often, yes, but it depends on the refinance type. VA.gov lists IRRRL (streamline) refinances at 0.5%, while cash-out refinances can be higher (VA.gov 2026). If youre exempt, you may still pay $0.

    8) Can the seller pay my VA funding fee?

    Sellers can often contribute toward allowable closing costs, and concessions can reduce your cash-to-close. Whether the funding fee itself can be paid by the seller depends on whats allowed in your deal. Well structure it carefully.

    9) How does the funding fee affect my monthly payment?

    If you finance the fee, you borrow more, so your payment usually rises. That matters more when rates are higher; Freddie Macs PMMS showed 6.48% on June 4, 2026 (Freddie Mac PMMS 2026). Ill model the difference.

    10) Should I choose VA or another loan type because of the funding fee?

    It depends. Many Fort Campbell and Middle Tennessee buyers still prefer VA because theres often no monthly mortgage insurance and flexible guidelines. The best choice comes from comparing total cost, cash-to-close, and your timeline. [INTERNAL LINK: FHA Loans Explained]

    Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage Clarksville TN mortgage lender and Fort Campbell VA loan specialist.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations about [TOPIC], I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    Call or text: (931) 980-9764
    Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt NMLS #18487, VanDyk Mortgage

    Clarksville TN mortgage lender Fort Campbell VA loan specialist

    {

    “@context”: “https://schema.org”,

    “@graph”: [

    {

    “@type”: “Article”,

    “@id”: “https://thedealdoctor.blog/?p=0#article”,

    “headline”: “The VA Funding Fee Explained (and When It’s Waived)”,

    “description”: “A clear guide to what the VA funding fee is, how its calculated, and the common situations where it can be waived for Fort Campbell and Clarksville-area homebuyers.”,

    “author”: {

    “@type”: “Person”,

    “name”: “Kate Matties-Deiboldt”,

    “identifier”: “NMLS #18487”

    },

    “publisher”: {

    “@type”: “Organization”,

    “name”: “VanDyk Mortgage”

    },

    “datePublished”: “2026-06-09”,

    “dateModified”: “2026-06-09”,

    “about”: [“VA loan”, “VA funding fee”, “Fort Campbell homebuying”, “Clarksville TN mortgage”],

    “mainEntityOfPage”: “https://thedealdoctor.blog/”

    },

    {

    “@type”: “FAQPage”,

    “@id”: “https://thedealdoctor.blog/?p=0#faq”,

    “mainEntity”: [

    {

    “@type”: “Question”,

    “name”: “Can I roll the VA funding fee into my loan?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Usually, yes. Most buyers finance it by adding it to the loan amount, which raises your balance and payment. If cash is tight, financing may help; paying it can lower the payment. Well compare both.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Is the funding fee the same as mortgage insurance?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “No. Mortgage insurance is usually a monthly charge on many conventional and FHA loans. The VA funding fee is typically a one-time upfront fee on many VA loans. Many Fort Campbell buyers still choose VA because it can avoid monthly MI.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “How do I know if my funding fee is waived?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “In many cases, youre exempt if youre receiving VA compensation for a service-connected disability, or you meet other VA-listed criteria like certain surviving spouse benefits or Purple Heart evidence before closing (VA.gov, accessed 2026). Ill help you confirm it early.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Whats the funding fee for a first-time VA buyer with $0 down?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “VA.gov lists 2.15% for first-use purchase loans with less than 5% down (effective April 7, 2023). On a $300,000 loan amount, thats $6,450. Your exact fee depends on your final loan amount.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “What if Ive used my VA loan benefit before?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “If youve used VA before and are using it again, VA.gov shows it can be higherfor example, 3.3% for subsequent use with less than 5% down (effective April 7, 2023). A 5% or 10% down payment can reduce the fee.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Does a bigger down payment always reduce the fee?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “For purchase and construction loans, yes5% or 10% down lowers the fee (VA.gov, accessed 2026). But some refinance types have a fixed fee that doesnt change with down payment. Loan type matters.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Do I pay the funding fee on a VA refinance?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Often, yes, but it depends on the refinance type. VA.gov lists IRRRL (streamline) refinances at 0.5%, while cash-out refinances can be higher (VA.gov, accessed 2026). If youre exempt, you may still pay $0.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Can the seller pay my VA funding fee?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “Sellers can often contribute toward allowable closing costs, and concessions can reduce your cash-to-close. Whether the funding fee itself can be paid by the seller depends on whats allowed in your deal. Well structure it carefully.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “How does the funding fee affect my monthly payment?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “If you finance the fee, you borrow more, so your payment usually rises. That matters more when rates are higher; Freddie Macs PMMS showed 6.48% on June 4, 2026. Ill model the difference.”

    }

    },

    {

    “@type”: “Question”,

    “name”: “Should I choose VA or another loan type because of the funding fee?”,

    “acceptedAnswer”: {

    “@type”: “Answer”,

    “text”: “It depends. Many Fort Campbell and Middle Tennessee buyers still prefer VA because theres often no monthly mortgage insurance and flexible guidelines. The best choice comes from comparing total cost, cash-to-close, and your timeline.”

    }

    }

    ]

    },

    {

    “@type”: “BreadcrumbList”,

    “@id”: “https://thedealdoctor.blog/?p=0#breadcrumbs”,

    “itemListElement”: [

    {“@type”: “ListItem”, “position”: 1, “name”: “Home”, “item”: “https://thedealdoctor.blog/”},

    {“@type”: “ListItem”, “position”: 2, “name”: “Homebuyer Education”, “item”: “https://thedealdoctor.blog/”},

    {“@type”: “ListItem”, “position”: 3, “name”: “The VA Funding Fee Explained (and When It’s Waived)”, “item”: “https://thedealdoctor.blog/”}

    ]

    },

    {

    “@type”: “LocalBusiness”,

    “@id”: “https://thedealdoctor.blog/?p=0#localbusiness”,

    “name”: “Kate Matties-Deiboldt, NMLS #18487, VanDyk Mortgage”,

    “telephone”: “+1-931-980-9764”,

    “email”: “Kate@JustCallKate.com”,

    “areaServed”: [“Clarksville”, “Fort Campbell”, “Montgomery County”, “Nashville”, “Middle Tennessee”],

    “url”: “https://thedealdoctor.blog/”

    },

    {

    “@type”: “SpeakableSpecification”,

    “@id”: “https://thedealdoctor.blog/?p=0#speakable”,

    “xpath”: [“/html/head/title”, “//h1”, “//div[@class=’key-takeaways’]”]

    },

    {

    “@type”: “HowTo”,

    “@id”: “https://thedealdoctor.blog/?p=0#howto”,

    “name”: “How to estimate your VA funding fee and plan cash-to-close”,

    “step”: [

    {“@type”: “HowToStep”, “name”: “Confirm if youre exempt”, “text”: “Gather VA disability award/eligibility paperwork and confirm exemption status before underwriting.”},

    {“@type”: “HowToStep”, “name”: “Pick the correct rate chart”, “text”: “Use the VA.gov funding fee rate chart for your loan type (purchase, cash-out refinance, or IRRRL).”},

    {“@type”: “HowToStep”, “name”: “Calculate fee dollars”, “text”: “Multiply your loan amount by the funding fee percentage to estimate the fee in dollars.”},

    {“@type”: “HowToStep”, “name”: “Compare finance vs. pay in cash”, “text”: “Model your monthly payment with the fee financed and with the fee paid at closing.”},

    {“@type”: “HowToStep”, “name”: “Lock in a plan”, “text”: “Use a pre-approval that reflects your preferred scenario and keeps your payment in budget.”}

    ]

    }

    ]

    }

    Sources: VA.gov funding fee rate charts (accessed 2026); Freddie Mac PMMS weekly mortgage rate averages (2026); FRED MORTGAGE30US 30-year fixed rate series (2026).

  • Rate Locks, Buy-Downs & Concessions: Clarksville Buyers

    Rate Locks, Buy-Downs, and Concessions: Negotiation Tools Buyers Don’t Know They Have

    A rate lock is a lender’s written commitment to hold a specific interest rate for a set period while your loan closes — protecting you from market spikes between application and funding. Paired with seller concessions and strategic buy-downs, a rate lock is part of a negotiation toolkit that can save a Clarksville TN homebuyer thousands of dollars over the life of their loan.

    Per Zillow Research (2026), 23.5% of active U.S. listings had a price cut in April 2026. With the 30-year fixed averaging 6.51% as of May 21, 2026 per Freddie Mac PMMS, shaving 1–2 points off your rate for the first two years produces real cash flow savings.

    TL;DR — Key Takeaways

    • Rate lock = rate insurance. 45–60 days on standard purchases; 60–90 days for VA, FHA, or PCS timelines.
    • Float-down options let you capture a rate drop mid-lock.
    • Permanent buy-downs (discount points) lower your rate for the loan’s life; temporary buy-downs (2-1, 3-2-1) lower it for Years 1–2 or 1–3.
    • Seller concessions can fund buy-downs or closing costs — caps: FHA/USDA 6%, Conventional 3–6%, VA 4% for non-allowables.
    • VA buyers at Fort Campbell can get all closing costs paid by the seller plus up to 4% in concessions.
    • 23.5% of U.S. listings had price cuts in April 2026 — use that seller pressure on rate structure, not just sale price.

    What Is a Rate Lock — and Why Does It Matter?

    A rate lock is a contractual guarantee that your interest rate will not increase during a defined window — typically 30 to 90 days — while your loan processes. A float-down is an optional rider that lets you benefit if rates drop before closing; it typically costs 0.125–0.25% of the loan amount. For PCS buyers at Fort Campbell, where orders can shift, ask specifically about 60- or 90-day lock options.

    Permanent vs. Temporary Buy-Downs: What’s the Difference?

    A permanent buy-down (discount points) is a prepaid interest payment that lowers your mortgage rate for the full loan term. One discount point equals 1% of the loan amount and typically reduces the rate by 0.25%. A temporary buy-down reduces the rate only for the first one to three years before reverting to the note rate:

    • 2-1 Buy-Down: Rate drops 2% in Year 1 and 1% in Year 2. On a 6.5% note rate: 4.5% in Year 1, 5.5% in Year 2, then full rate from Year 3.
    • 3-2-1 Buy-Down: Rate drops 3% in Year 1, 2% in Year 2, 1% in Year 3, then full note rate.

    What Are Seller Concessions, and How Much Can a Seller Pay?

    A seller concession is any credit the seller contributes on behalf of the buyer. In Q1 2025, The Mortgage Reports (2025) reported 44.4% of home sales nationally included concessions.

    Loan Type Max Concession Cap Notes
    Conventional (<10% down) 3% of purchase price Covers closing costs & prepaids
    Conventional (10–25% down) 6% of purchase price Higher down payment = more seller leverage
    FHA 6% of purchase price Popular for first-time homebuyers in Clarksville
    VA All allowable closing costs + up to 4% in concessions Concessions cover non-allowables: funding fee, buy-down, prepaids
    USDA 6% of purchase price Available in eligible rural areas of Middle Tennessee

    Comparison: Discount Points vs. 2-1 Buy-Down vs. Seller Credit

    Feature Discount Points 2-1 Temporary Buy-Down Seller Credit
    Cost (on $350k loan) ~$3,500 per point ~$8,000–$9,000 total Negotiated (often 1–3% of price)
    Monthly payment impact Permanent reduction (~$60–80/mo per point) Year 1: large reduction; reverts in Year 3 Indirect (offsets cash at closing)
    Breakeven ~4–5 years Immediate savings; no traditional breakeven Immediate (cash relief at closing)
    Best for Buyers staying 7+ years Buyers expecting income growth or military PCS buyers Cash-constrained buyers near DTI limits

    How to Negotiate the Best Rate Package in 7 Steps

    1. Get mortgage pre-approval first. Pre-approval clarifies your loan type, concession cap, and signals to listing agents in Clarksville, Fort Campbell, and Montgomery County TN that you’re a serious buyer.
    2. Know your concession ceiling. VA loans Clarksville TN: all closing costs plus up to 4% in concessions. FHA/USDA: 6%. Conventional under 10% down: 3%.
    3. Check days-on-market before writing your offer. A seller who trimmed price once is primed to accept a concession over a second reduction.
    4. Request a concession earmarked for a buy-down. Write specifically: “Seller to contribute $9,000 toward buyer’s closing costs and/or interest rate buy-down account.”
    5. Ask about a float-down rider. Ask your Middle Tennessee mortgage lender: “Do you offer a float-down, what does it cost, and what’s the minimum drop to exercise?”
    6. Match lock duration to your timeline. Standard closings: 30–45 days. VA, FHA, USDA: 45–60 days. PCS buyers at Fort Campbell: request 60–90 days.
    7. Run the math side-by-side. On a $350,000 loan at 6.5%, one discount point ($3,500) saves ~$57/month — breakeven at 61 months. If you’re a Fort Campbell service member with a PCS likely in 3–4 years, the seller-funded 2-1 buy-down almost always wins over paying points.

    FAQ — Rate Locks, Buy-Downs, and Seller Concessions

    How long should a rate lock be?

    For standard purchases in Clarksville TN and Middle Tennessee, a 45-day lock covers appraisal, underwriting, title, and closing. VA loans, FHA, and USDA transactions often need 60 days. PCS military buyers relocating to Fort Campbell should request 60–90 days. Extension fees run 0.125–0.25% per 15-day extension.

    What is a float-down option?

    A float-down is a rider on a rate lock that lets you drop to a lower rate if the market falls by a set threshold — usually 0.25–0.50% — before closing. Float-downs typically cost 0.125–0.25% of the loan amount and can be exercised once.

    Can VA buyers get seller concessions?

    Yes. A seller can pay all of the buyer’s allowable closing costs plus provide up to 4% of the home’s VA-appraised value in non-allowable concessions. Per Veterans United (2026), Fort Campbell and Clarksville buyers who structure this correctly can eliminate most out-of-pocket costs at closing.

    Do discount points pay back fast enough to be worth it?

    One discount point on a $350,000 loan costs $3,500 and saves roughly $57–$60/month — breakeven around 61 months. For a first-time homebuyer in Clarksville planning to stay 7–10 years, points are often worth it. For a Fort Campbell service member facing a PCS in 3–4 years, a seller-funded buy-down is the better tool.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

  • How Long Until I Can Buy After a Bankruptcy, Foreclosure, or Short Sale?

    How Long Until I Can Buy After a Bankruptcy, Foreclosure, or Short Sale?

    You can often buy again sooner than you think — the timeline depends on loan type and the exact credit event. The waiting period is measured from your discharge, dismissal, or completion date, not the day trouble started. In Clarksville, Fort Campbell, or anywhere in Middle Tennessee, the fastest path matches your paperwork and recovery plan.

    Conventional loan rules have clear “time clocks” for major credit events — for example, Fannie Mae lists a 4-year waiting period after a Chapter 7 bankruptcy discharge (and 7 years after a foreclosure completion date) in its Selling Guide (Fannie Mae (2007)).

    TL;DR — Key Takeaways

    • “Waiting period” is the mandatory time you must wait after a major credit event before a specific loan program will allow you to close.
    • Conventional (Fannie Mae) can be longer (think 4 years after Chapter 7, 7 years after foreclosure) unless documented exceptions apply (Fannie Mae (2007)).
    • FHA is often more flexible and has special “Back to Work” guidance for certain economic events (HUD (2013)).
    • Your “end date” matters: discharge vs dismissal, foreclosure completion vs deed-in-lieu vs short sale completion.
    • The fastest realistic strategy is to plan the timeline, rebuild credit for 12 months, and get a pre-approval game plan early for Clarksville or Nashville-area home shopping.

    First: what counts as a “major credit event”?

    A major credit event is a serious negative mark on your credit history that most mortgage programs treat differently than late payments. A bankruptcy is a legal court process that addresses debts through discharge or repayment. A foreclosure is the lender’s legal process to take back a home after default. A short sale is a sale for less than the mortgage balance that the servicer approves to avoid foreclosure.

    When does the clock start?

    Many Clarksville and Fort Campbell buyers get tripped up here: your waiting period starts from a specific “event end date,” not when you stopped paying bills. For conventional loans, Fannie Mae measures from the completion, discharge, or dismissal date to the new loan’s disbursement date (Fannie Mae (2007)).

    Conventional (Fannie Mae) waiting periods

    If you’re aiming for a conventional mortgage (common for Nashville commuters and repeat buyers in Montgomery County), here’s the framework. Your exact scenario varies, but these are the headline timeframes published by Fannie Mae.

    Event Typical conventional waiting period (Fannie Mae) How it’s measured
    Chapter 7 or 11 bankruptcy 4 years (2 years with documented extenuating circumstances) From discharge or dismissal date
    Chapter 13 bankruptcy 2 years after discharge (4 years after dismissal) From discharge or dismissal date
    Foreclosure 7 years (as low as 3 years with documented extenuating circumstances) From foreclosure completion date
    Deed-in-lieu or preforeclosure sale (short sale) 4 years (2 years with documented extenuating circumstances) From completion date

    These timeframes are summarized directly in the Selling Guide table for significant derogatory credit events (Fannie Mae (2007)).

    FHA: why some buyers return sooner

    FHA can be more forgiving after a credit setback, which is why it often fits a first-time homebuyer Clarksville plan. HUD’s “Back to Work” Mortgagee Letter described cases where borrowers affected by an economic event could be eligible after as little as 12 months, with documented recovery and counseling (HUD (2013)). FHA decisions hinge on documentation, post-event housing history, and re-established on-time payments.

    How to get mortgage-ready again in 6 steps

    Even with a two-, four-, or seven-year wait, don’t waste the first year. A practical roadmap for Clarksville TN mortgage lender conversations:

    1. Confirm the exact event dates. Pull your credit report and court paperwork so we use the correct discharge/completion date.
    2. Choose the right target program. “Best rate” isn’t “best plan” if it forces a longer wait in the Clarksville housing market.
    3. Rebuild a clean 12-month payment streak. A clean year is often the difference between “maybe” and “approved.”
    4. Stabilize income and cash-to-close. Fort Campbell home buying and PCS timelines move fast; reserves reduce stress.
    5. Document the story, not just the score. Underwriting is proof-based: dates, explanations, evidence.
    6. Get a pre-approval plan early. A mortgage pre-approval Clarksville strategy sets score targets, debt paydown order, and a realistic timeline.

    [INTERNAL LINK: mortgage pre-approval checklist]

    [INTERNAL LINK: FHA vs conventional in Tennessee]

    [INTERNAL LINK: credit rebuild plan after major derogatory]

    Local reality check for Clarksville, Fort Campbell, and Nashville buyers

    For Montgomery County TN homes shopping on a PCS to Fort Campbell schedule, you need a fast decision on whether FHA, VA, or conventional is realistic by your report date. Nashville housing market commuters often price into conventional — which has the longest seasoning after foreclosure. The right answer fits your dates, paperwork, and budget — not a social-media rule.

    Frequently Asked Questions

    How long do I have to wait after a Chapter 7 bankruptcy to buy a house?

    Conventional timelines commonly require 4 years from the Chapter 7 discharge or dismissal date, per Fannie Mae’s published waiting periods (Fannie Mae (2007)). Other programs can be different, so confirm your discharge date and match it to the loan type you want in Clarksville or Nashville.

    Is Chapter 13 different than Chapter 7 for mortgage timing?

    Yes. Chapter 13 is a repayment bankruptcy, so the timing can be different than Chapter 7. For conventional loans, Fannie Mae lists 2 years from discharge (and 4 years from dismissal) for Chapter 13 (Fannie Mae (2007)). Your paperwork matters.

    How long after a foreclosure can I buy again?

    It varies by program, but conventional mortgages can be the longest. Fannie Mae lists 7 years from the foreclosure completion date (with documented exceptions that may allow a shorter timeline) (Fannie Mae (2007)). Always confirm the completion date in your documents.

    How long after a short sale can I get a conventional mortgage?

    A short sale can still trigger a waiting period. Fannie Mae groups “preforeclosure sale (short sale)” with deed-in-lieu and lists 4 years from the completion date (2 years with documented extenuating circumstances) (Fannie Mae (2007)). The completion date is key.

    Does the waiting period start when the bankruptcy is filed or when it’s discharged?

    Usually it’s tied to the end of the case, not the filing. Fannie Mae measures bankruptcy waiting periods from the discharge or dismissal date (Fannie Mae (2007)). If you’re unsure which date applies, verify it with your court documents before you shop in Clarksville.

    Can I buy in Clarksville or Fort Campbell if my score is back up but the waiting period isn’t over?

    Sometimes yes, sometimes no. A higher score helps, but a waiting period is a program rule — it can’t be “scored” away. Pick a realistic program and timeline, then build a clean 12-month payment history so you’re ready the moment the clock expires for your Clarksville or Fort Campbell purchase.

    What are “extenuating circumstances” for shorter waiting periods?

    Extenuating circumstances are typically a serious, one-time event beyond your control that caused the problem (not a pattern of overspending). Some conventional guidance allows shorter waiting periods when those circumstances are documented (Fannie Mae (2007)). The burden is on documentation, not just explanation.

    Does FHA have a faster path after bankruptcy or foreclosure?

    Sometimes. HUD published “Back to Work” guidance describing cases where borrowers impacted by an economic event could be eligible after 12 months from events like foreclosure, deed-in-lieu, short sale, or bankruptcy discharge, with counseling and re-established credit (HUD (2013)). A lender still must underwrite and document carefully.

    What paperwork should I gather before talking to a lender?

    Bring documents that prove your dates: bankruptcy discharge/dismissal papers, foreclosure or short sale completion documents, and your current credit report. Then add basics: two years of W-2s (or tax returns if self-employed), recent pay stubs, and two months of bank statements. That set lets a Clarksville TN mortgage lender give real timing, not guesses.

    What’s the smartest first step if I’m relocating to Fort Campbell and worried about timing?

    Start with a written timeline. If you’re on a PCS to Fort Campbell schedule, map your report date, your event end date, and which programs you can realistically use. Then set score and savings targets so you don’t lose time. The goal is a clean pre-approval plan before you shop homes for sale near Fort Campbell.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
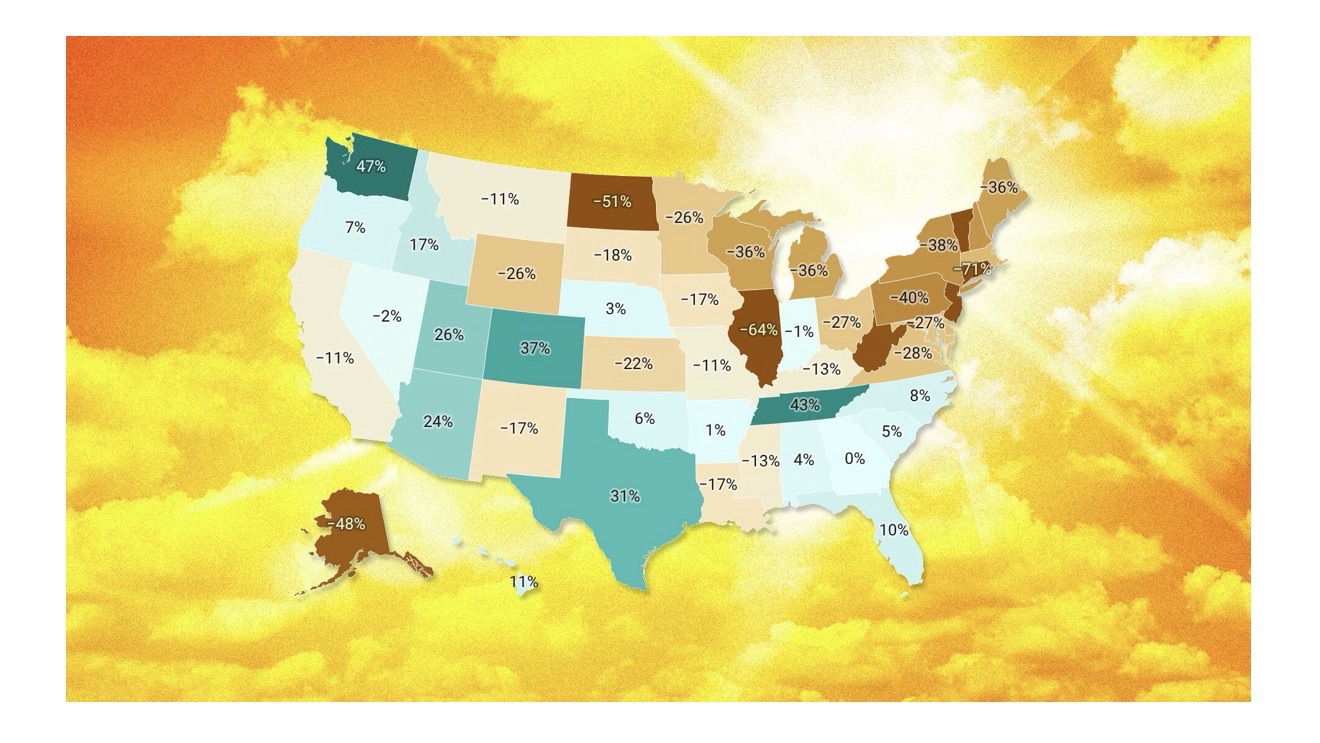
    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

  • How Lenders Calculate Income for W-2 Borrowers (Overtime, Bonus, Commission)

    How Lenders Calculate Income for W-2 Borrowers (Overtime, Bonus, Commission)

    Mortgage lenders usually start with your W-2 base pay, then add overtime, bonus, and commission only if it’s documented and shown to be stable. In plain English: you don’t “tell” a lender what you make — you prove it with paystubs, W-2s, and verification from your employer.

    If you’re buying in Clarksville, around Fort Campbell, commuting toward Nashville, or shopping Montgomery County and Middle Tennessee, variable pay can be the difference between “approved” and “not yet.” Fannie Mae (2026) generally wants a two-year history for bonus/commission/overtime, though 12 months can work with strong compensating factors.

    TL;DR — Key Takeaways

    • Base pay is the foundation. Your salary or hourly rate is usually the easiest income to use.
    • Overtime/bonus/commission can count when it’s documented and stable (Fannie Mae (2026)).
    • Lenders average variable income to reduce the risk of “one great month” inflating your buying power.
    • Paystubs + W-2s + employer verification are the normal proof package.
    • Job changes aren’t always a deal-breaker, but changes in pay structure can slow underwriting.

    First: what “qualifying income” actually means

    Qualifying income is the monthly income a lender will use to calculate what you can safely repay. It’s not always the same as the year-to-date number on your paystub.

    Base income is your regular pay — salary, or hourly rate times standard hours. Variable income is pay that can go up and down, like overtime, commission, and bonuses. Variable income is where underwriting gets picky, especially for first-time homebuyer Clarksville households stretching affordability.

    What documents lenders use for W-2 income

    Most W-2 borrowers provide a short doc list — the goal is to confirm income is real and likely to continue:

    • Recent paystubs (with YTD earnings and pay type)
    • W-2s (usually two years)
    • Verification of Employment (VOE) from your employer
    • Employer letter explaining commission/bonus structure, if applicable

    For variable pay, Fannie Mae (2026) requires documentation plus a history-and-stability review.

    How lenders calculate base pay (salary and hourly)

    • Salaried: annual salary ÷ 12 = monthly base
    • Hourly: hourly rate × typical weekly hours × 52 ÷ 12

    Consistent full-time W-2 pay is usually straightforward — helpful for mortgage pre-approval Clarksville before touring homes near Fort Campbell.

    How overtime income is typically counted

    Overtime income is extra pay for hours beyond your standard schedule. Because it can disappear when staffing changes, underwriters typically want a track record and then average it.

    1. Confirm it exists — paystubs show it, employer verifies it.
    2. Review history — Fannie Mae (2026) prefers two years; 12 months is sometimes acceptable.
    3. Average it — total overtime ÷ months = monthly figure.

    Trend matters: declining overtime may be reduced or excluded — common for military relocation Clarksville families during a PCS to Fort Campbell.

    How bonus income is handled (especially annual bonuses)

    Bonus income is additional pay on top of base salary, often tied to performance. Underwriters won’t treat a one-time bonus as guaranteed future pay. Fannie Mae (2026) typically annualizes a recurring bonus and divides by 12 for a monthly figure.

    How commission income is counted (when pay changes month to month)

    Commission income is pay tied to sales or production, and it often fluctuates — so lenders use an average, not your best month. Expect extra questions from any Clarksville TN mortgage lender: Is it guaranteed? How long have you earned it? Is it stable or trending down?

    Income type Why lenders treat it differently What usually helps
    Base (salary/hourly) Most predictable Current paystub + W-2 history
    Overtime Can be cut quickly 12–24 months history + stable trend (Fannie Mae (2026))
    Bonus May be discretionary or annual Annualize/average and show repeat pattern (Fannie Mae (2026))
    Commission Fluctuates with sales volume Consistent deposits + employer explanation of structure

    Reality check: your pay may be rising, but underwriting still averages

    Even with rising wages — average hourly earnings hit $37.41 in April 2026 (BLS (2026)) — lenders focus on your verified history, not national averages, especially in the Clarksville housing market where payment comfort matters most.

    How to strengthen your file (7 steps)

    1. Collect clean paystubs showing overtime/bonus/commission lines clearly.
    2. Keep job changes explainable — same industry beats a brand-new comp plan.
    3. Avoid mystery deposits — irregular income will get questioned.
    4. Expect a VOE — respond fast if HR needs a nudge.
    5. Document bonus/commission structure with an employer letter.
    6. Don’t count on your best month — budget the average for accurate Nashville mortgage rates quotes.
    7. Get a pre-approval review early so you can plan around Montgomery County TN homes price ranges.

    If you want related guidance, here are a few next reads: [INTERNAL LINK: How much house can I afford in Clarksville?] and [INTERNAL LINK: Mortgage approval with a gap in employment].

    Frequently Asked Questions

    Do lenders count overtime income for a mortgage?

    Yes, overtime can count if it’s documented and stable. Fannie Mae (2026) prefers two years, though 12 months may work with strong positive factors. Expect the lender to average overtime into a monthly figure rather than using your best paycheck.

    How do lenders calculate bonus income?

    Lenders typically average bonus income and convert it into a monthly amount. If bonuses are annual, underwriters often annualize the bonus by dividing the total by 12, then evaluate whether the pattern is consistent year over year. The goal is to avoid counting a one-time payout as guaranteed future income.

    Can commission income be used to qualify for a mortgage?

    Often yes, but commission is treated as variable income because it can rise and fall. Lenders generally review pay history and trends and may ask for an employer letter explaining how commissions are earned. If you’re buying near Fort Campbell or in Clarksville, plan ahead so underwriting can average a reliable amount.

    What if my income went up recently — will the lender use the higher amount?

    For base pay, lenders can usually use your current higher rate if it’s verified and expected to continue. For overtime, bonuses, and commissions, they may still average and may not fully credit the recent jump until it shows a stable pattern. That’s why getting mortgage pre-approval Clarksville early helps you avoid surprises.

    How many paystubs do I need for a mortgage?

    Many lenders ask for recent paystubs that show year-to-date earnings, plus W-2s for additional history. The exact number of paystubs can vary by lender and loan type, but the purpose is the same: confirm you’re currently working and that your pay matches what’s being used to qualify you.

    Why do lenders average overtime, bonus, and commission instead of using my most recent pay?

    Averaging protects you and the lender from qualifying on temporary spikes. Variable income shifts with staffing and sales cycles, so an average keeps your payment affordable if pay returns to normal — important in the Clarksville real estate market and Nashville housing market.

    Will a job change hurt my mortgage approval?

    Not always. Many borrowers change jobs and still get approved, especially if they stay in the same line of work. What tends to slow things down is a major change in pay structure (like moving from salary to mostly commission) or a gap in employment that requires extra documentation.

    Can I qualify with W-2 income if I’m relocating to Fort Campbell?

    Yes, many PCS to Fort Campbell borrowers qualify with W-2 income, but timing matters. Lenders typically need documentation showing your employment and pay, and they may verify that the job is expected to continue. If you’re starting a new role, talk through start dates and first paystub timing early.

    What is a Verification of Employment (VOE)?

    A Verification of Employment is a lender’s way of confirming you work where you say you work and verifying details like position, start date, and sometimes probability of continued employment. VOE can be written or verbal depending on the lender. It’s standard, and it’s one reason responding quickly helps your file move faster.

    What should I do if my variable income is too new to count?

    You still have options: qualify on base pay only, choose a lower price point, pay down debts to improve your ratio, or wait until you have more documented months. In Middle Tennessee, a clear plan turns “not yet” into “approved” without panic.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

  • Can I Buy a Home if I Just Started a New Job in Clarksville?

    Can I Buy a Home if I Just Started a New Job in Clarksville?

    Yes — you can often buy a home even if you just started a new job, as long as your new position is stable, properly documented, and your pay structure is something an underwriter can use. The biggest “make or break” issues are your start date, whether your income is salary vs hourly vs commission, and whether your paperwork matches what you put on the loan application.

    Here’s the reality: lenders verify employment carefully right before closing, and the rules can be surprisingly specific. For example, Fannie Mae guidance updated in 2026 allows certain borrowers to qualify using a fully executed employment offer/contract, as long as the start date is within a defined window around closing and the lender completes extra verification steps (Fannie Mae Selling Guide (2026)).

    TL;DR — Key Takeaways

    • A new job isn’t an automatic “no.” The lender just needs a clean story and clean documentation.
    • Your start date matters. Some loans can use an offer letter, but it has timing rules and extra verification.
    • Salary is easiest. Hourly can work; commission/bonus usually needs a history.
    • Don’t change jobs mid-process without a plan. One “small” change can trigger re-approval.
    • Local tip: PCS moves to Fort Campbell and new Nashville commutes can be approved — if we structure the file correctly.

    What lenders are really trying to confirm

    Mortgage underwriting is a risk review, not a judgment. The lender is trying to confirm you can repay the loan for years — not just make the first payment.

    Employment verification is the proof that your job and pay are real and ongoing. Income documentation is the proof that the amount you’re using to qualify is accurate and likely to continue.

    “Stable income” is predictable income that can be documented and is expected to keep coming. That’s why the details of a brand-new job (pay type, start date, probation period, guaranteed hours) matter so much.

    Offer letters: when they help (and when they don’t)

    An employment offer letter is a signed document showing your job title, start date, and pay. It can sometimes be used to qualify before you receive your first paycheck — but it is not a free pass.

    Fannie Mae’s Selling Guide says an executed offer/contract can be used when the borrower’s start date is no earlier than 30 days before the note date and no later than 90 days after the note date, and it requires additional steps like obtaining the most recent paystub prior to delivery and completing employment verification (Fannie Mae Selling Guide (2026)).

    Situation Usually workable? What the lender usually wants
    New salaried W-2 job starts before closing Often yes Paystub + W-2s (if applicable) + verification of employment
    New job starts shortly after closing Sometimes Executed offer letter/contract + start-date window + verification steps
    Commission/bonus job with no history Maybe, case-by-case Base salary only (if allowed) or more time on the job
    Switching from W-2 to self-employed Harder Business history + tax returns (varies by program)

    Documents you should expect to provide

    • Recent paystubs showing year-to-date earnings
    • W-2s (or wage transcripts)
    • Offer letter/contract (if you’re brand-new)

    Fannie Mae’s documentation standards (updated 2026) describe common acceptable items like paystubs, W-2s, and employment verification (Fannie Mae Selling Guide (2026)).

    How to buy a home after starting a new job (5 steps)

    1. Tell your lender early. No surprises.
    2. Make the offer letter clear. Start date + pay + position + signatures.
    3. Know what income counts. Base pay is easiest; variable pay may not count yet.
    4. Save your first paystub(s). Even one can remove conditions.
    5. Time the closing. Align closing with your start date and documentation timeline.

    Local Clarksville + Nashville timing tips

    • PCS to Fort Campbell: We plan around orders/LES timing and the closing date.
    • Nashville commute: Keep employer/work-location details consistent across the file.

    [INTERNAL LINK: Mortgage Approval With a Gap in Employment: What’s Actually Disqualifying]

    [INTERNAL LINK: How Lenders Calculate Income for W-2 Borrowers (Overtime, Bonus, Commission)]

    [INTERNAL LINK: Military Income, BAH, and BAS: How VA Lenders Count Your Pay at Fort Campbell]

    Frequently Asked Questions

    Will a lender deny me just because I’m in my first 30–90 days?

    Usually not. In Clarksville and around Fort Campbell, job changes are common (especially with PCS moves). What matters is whether your pay type is usable and whether your dates and documents match what’s on the loan application.

    Can I close before I receive my first paycheck?

    Sometimes. Certain loans can use a fully executed offer letter/contract if the start date and verification steps fit the guidelines. Fannie Mae allows this in a limited timing window around closing with extra verification requirements (Fannie Mae Selling Guide (2026)).

    If my new job is hourly, how do lenders calculate my income?

    Hourly income is usually based on your hourly rate and expected hours, but the lender wants evidence the hours are stable. If your schedule varies a lot in Montgomery County, we may use a conservative average depending on the loan program.

    Do overtime, bonus, or commission count if I just started?

    Often not yet. Overtime/bonus/commission are variable income, and many programs want a history before using it to qualify. If you have a base rate or base salary, we may qualify you on that portion first.

    What if I switched industries (like military to civilian)?

    A pivot can be approvable, but it needs a clear explanation. Underwriters look for training and experience that supports the new role. I see this often with Fort Campbell transitions and Nashville-area job offers.

    Can I change jobs while I’m already under contract on a home?

    Yes, but plan it first. A job change can trigger a re-review of income and can change your qualifying numbers. Before you resign, talk to your lender so we can confirm what documentation the new job will require.

    What if my offer letter is missing details?

    That’s a common delay. Your offer letter should show start date, pay, position, and be fully executed. If anything is vague, the lender may require additional employer verification before you can close.

    Does a probationary period or “at-will” employment hurt my approval?

    Not automatically. Most jobs are at-will, and many have introductory periods. The lender mainly wants to verify that your income is documentable and likely to continue, and that your file is consistent.

    I’m relocating to Fort Campbell — can I still get approved if I’m starting a new assignment?

    Often yes. Military pay is usually documentable, and Fort Campbell relocations are common. The key is aligning orders/LES and your occupancy plan so the lender can verify your income and your intent to live in the home.

    How soon should I get pre-approved if I’m starting a job in Nashville but buying in Clarksville?

    As soon as you have an offer and a realistic start date. A solid pre-approval helps you shop confidently and prevents last-minute surprises. If you’ll commute from Clarksville to Nashville, we’ll keep work-location details consistent across the file.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “@id”: “https://thedealdoctor.blog/?p=topic-07#article&#8221;,
    “headline”: “Can I Buy a Home if I Just Started a New Job in Clarksville?”,
    “description”: “Can you buy a home after starting a new job in Clarksville or near Fort Campbell? Learn what lenders verify, what documents you need, and how to time closing.”,
    “datePublished”: “2026-06-01”,
    “dateModified”: “2026-06-01”,
    “author”: {
    “@type”: “Person”,
    “name”: “Kate Matties-Deiboldt”,
    “identifier”: “NMLS #18487”,
    “worksFor”: {“@type”:”Organization”,”name”:”VanDyk Mortgage”}
    },
    “publisher”: {“@type”:”Organization”,”name”:”The Blue Note Home”},
    “mainEntityOfPage”: {“@type”:”WebPage”,”@id”:”https://thedealdoctor.blog/&#8221;},
    “keywords”: [
    “new job mortgage approval”,
    “mortgage pre-approval Clarksville”,
    “Clarksville TN mortgage lender”,
    “Fort Campbell home buying”,
    “Nashville commuter mortgage”
    ]
    },
    {
    “@type”: “BreadcrumbList”,
    “@id”: “https://thedealdoctor.blog/?p=topic-07#breadcrumbs&#8221;,
    “itemListElement”: [
    {“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog/&#8221;},
    {“@type”:”ListItem”,”position”:2,”name”:”For Homebuyers”,”item”:”https://thedealdoctor.blog/for-homebuyers/&#8221;},
    {“@type”:”ListItem”,”position”:3,”name”:”Can I Buy a Home if I Just Started a New Job in Clarksville?”,”item”:”https://thedealdoctor.blog/?p=topic-07&#8243;}
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “@id”: “https://thedealdoctor.blog/?p=topic-07#localbusiness&#8221;,
    “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,
    “address”: {
    “@type”: “PostalAddress”,
    “addressLocality”: “Clarksville”,
    “addressRegion”: “TN”,
    “addressCountry”: “US”
    },
    “telephone”: “+1-931-980-9764”,
    “email”: “Kate@JustCallKate.com”,
    “areaServed”: [
    “Clarksville TN”,
    “Fort Campbell”,
    “Montgomery County TN”,
    “Nashville TN”,
    “Middle Tennessee”
    ],
    “additionalProperty”: [
    {“@type”:”PropertyValue”,”name”:”NMLS”,”value”:”18487″}
    ]
    },
    {
    “@type”: “SpeakableSpecification”,
    “@id”: “https://thedealdoctor.blog/?p=topic-07#speakable&#8221;,
    “cssSelector”: [“.key-takeaways”, “h1”, “p:first-of-type”]
    },
    {
    “@type”: “HowTo”,
    “@id”: “https://thedealdoctor.blog/?p=topic-07#howto&#8221;,
    “name”: “How to buy a home after starting a new job”,
    “description”: “A step-by-step plan to get pre-approved and close on a home after starting a new job in Clarksville, near Fort Campbell, or commuting to Nashville.”,
    “totalTime”: “P7D”,
    “step”: [
    {“@type”:”HowToStep”,”position”:1,”name”:”Tell your lender immediately”,”text”:”Share the exact start date, pay type, and employer details upfront.”},
    {“@type”:”HowToStep”,”position”:2,”name”:”Clean up the offer letter”,”text”:”Make sure it shows start date, pay, position, and is fully executed.”},
    {“@type”:”HowToStep”,”position”:3,”name”:”Confirm what income can be used”,”text”:”Base salary is typically simplest; variable income may need history.”},
    {“@type”:”HowToStep”,”position”:4,”name”:”Avoid major job or industry pivots mid-loan”,”text”:”Stability and consistency reduce underwriting conditions.”},
    {“@type”:”HowToStep”,”position”:5,”name”:”Keep your first paystub(s)”,”text”:”Paystubs help verify actual earnings and timing.”},
    {“@type”:”HowToStep”,”position”:6,”name”:”Don’t add new debt”,”text”:”New monthly payments can reduce qualifying power.”},
    {“@type”:”HowToStep”,”position”:7,”name”:”Time the closing”,”text”:”Align closing with your start date and documentation timeline.”}
    ]
    },
    {
    “@type”: “FAQPage”,
    “@id”: “https://thedealdoctor.blog/?p=topic-07#faq&#8221;,
    “mainEntity”: [
    {“@type”:”Question”,”name”:”Will a lender deny me just because I’m in my first 30–90 days?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Usually not. In Clarksville and around Fort Campbell, job changes are common (especially with PCS moves). What matters is whether your pay type is usable and whether your dates and documents match what’s on the loan application.”}},
    {“@type”:”Question”,”name”:”Can I close before I receive my first paycheck?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Sometimes. Certain loans can use a fully executed offer letter/contract if the start date and verification steps fit the guidelines. Fannie Mae allows this in a limited timing window around closing with extra verification requirements (Fannie Mae Selling Guide, 2026).”}},
    {“@type”:”Question”,”name”:”If my new job is hourly, how do lenders calculate my income?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Hourly income is usually based on your hourly rate and expected hours, but the lender wants evidence the hours are stable. If your schedule varies a lot in Montgomery County, we may use a conservative average depending on the loan program.”}},
    {“@type”:”Question”,”name”:”Do overtime, bonus, or commission count if I just started?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Often not yet. Overtime/bonus/commission are variable income, and many programs want a history before using it to qualify. If you have a base rate or base salary, we may qualify you on that portion first.”}},
    {“@type”:”Question”,”name”:”What if I switched industries (like military to civilian)?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”A pivot can be approvable, but it needs a clear explanation. Underwriters look for training and experience that supports the new role. I see this often with Fort Campbell transitions and Nashville-area job offers.”}},
    {“@type”:”Question”,”name”:”Can I change jobs while I’m already under contract on a home?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes, but plan it first. A job change can trigger a re-review of income and can change your qualifying numbers. Before you resign, talk to your lender so we can confirm what documentation the new job will require.”}},
    {“@type”:”Question”,”name”:”What if my offer letter is missing details?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”That’s a common delay. Your offer letter should show start date, pay, position, and be fully executed. If anything is vague, the lender may require additional employer verification before you can close.”}},
    {“@type”:”Question”,”name”:”Does a probationary period or “at-will” employment hurt my approval?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Not automatically. Most jobs are at-will, and many have introductory periods. The lender mainly wants to verify that your income is documentable and likely to continue, and that your file is consistent.”}},
    {“@type”:”Question”,”name”:”I’m relocating to Fort Campbell — can I still get approved if I’m starting a new assignment?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Often yes. Military pay is usually documentable, and Fort Campbell relocations are common. The key is aligning orders/LES and your occupancy plan so the lender can verify your income and your intent to live in the home.”}},
    {“@type”:”Question”,”name”:”How soon should I get pre-approved if I’m starting a job in Nashville but buying in Clarksville?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”As soon as you have an offer and a realistic start date. A solid pre-approval helps you shop confidently and prevents last-minute surprises. If you’ll commute from Clarksville to Nashville, we’ll keep work-location details consistent across the file.”}}
    ]
    }
    ]
    }

  • Why Your Mortgage Credit Score Is Different From Your Credit Karma Score

    Why Your Mortgage Credit Score Is Different From Your Credit Karma Score

    Your mortgage credit score is the specific credit-score version many mortgage lenders pull for home loans, and it can be noticeably higher or lower than the score you see on Credit Karma. That doesn’t mean your lender is “using a secret score” — it means different scoring models are looking at the same credit report in slightly different ways. In Clarksville, Fort Campbell, and Nashville, this catches a lot of first-time buyers off guard right before pre-approval.

    Rates are still sensitive to score ranges — Freddie Mac’s Primary Mortgage Market Survey noted the average 30-year fixed rate was 6.53% as of May 28, 2026 (Freddie Mac PMMS (2026)) — so understanding which score is being used helps you focus on what actually moves the needle.

    TL;DR — Key Takeaways

    • Credit Karma usually shows a VantageScore. Many mortgage lenders still use older “classic” FICO mortgage scores.
    • The score version matters. Two legitimate models can score the same borrower differently.
    • Mortgage underwriting often uses three bureaus. Lenders may use a “middle” score from a tri-merge pull.
    • Focus on fundamentals that help across models. Lower card balances, on-time payments, and clean reports.
    • If you’re PCS’ing to Fort Campbell or buying in Montgomery County, plan a 30–45 day runway before you shop.

    First: what score does Credit Karma show?

    Credit Karma typically shows a VantageScore, not the same score version used in many mortgage approvals. VantageScore is a scoring model — and a scoring model is the math formula that turns your credit report into a number.

    Here’s the simplest way to think about it in Clarksville: a credit report is your history, and a credit score is the model’s interpretation of that history. Change the model, and the score can change.

    What score do mortgage lenders actually use?

    A mortgage credit score is the classic FICO score version often used for home lending decisions. Chase explains that lenders commonly use older FICO versions for mortgages — FICO Score 2 (Experian), FICO Score 4 (TransUnion), and FICO Score 5 (Equifax) — and may use the middle score from the three (Chase (2026)).

    Why the numbers don’t match

    “Credit score version” is the specific scoring formula used to calculate your score. A different version can score the same borrower differently, especially when balances are high, credit is thin, or recent activity is heavy.

    Tri-merge + “middle score” (the quick explanation)

    A tri-merge credit report is a combined pull from Experian, TransUnion, and Equifax used in many mortgage applications. Many lenders use a middle score from that pull, and for couples they may price off the lower middle score (Chase (2026)).

    What’s changing in 2026 (and what isn’t)

    FHFA says approved lenders may deliver loans using either Classic FICO or VantageScore 4.0 in an interim phase, and notes that current credit reporting requirements (like tri-merge/bi-merge) won’t change initially (FHFA (2026)). For most Middle Tennessee buyers today, that means your mortgage lender is still likely pulling classic mortgage scores.

    How to reduce surprises before pre-approval (5 steps)

    1. Lower credit card balances. Utilization is one of the biggest drivers across scoring models.
    2. Avoid new credit. New accounts and inquiries can change scores and add underwriting conditions.
    3. Check all three bureaus for errors. One wrong late payment can control your middle score.
    4. Give yourself a runway. If you’re PCS to Fort Campbell or buying in Clarksville, aim for 30–45 days before you shop.
    5. Ask what score version was used. Knowing the bureau/model helps you target what to fix.

    Quick comparison: app scores vs mortgage scores

    What you’re looking at What it’s for What to do about it
    Credit Karma / many free apps Education + monitoring (often VantageScore) Use it to track trends and spot report errors — not to estimate your mortgage tier
    Mortgage underwriting score Home loan approval + pricing tiers Lower balances, avoid new credit, and plan ahead before mortgage pre-approval Clarksville
    Tri-merge “middle score” How many lenders evaluate risk across bureaus Make sure all three bureaus are accurate — one weak bureau can control the outcome

    Related reading: [INTERNAL LINK: What Credit Score Do You Really Need to Buy a Home in Clarksville TN?] [INTERNAL LINK: The 5 Mortgage Credit Score Killers (and How to Recover Fast)] [INTERNAL LINK: Should I Pay Off Collections Before Applying for a Mortgage?]

    Frequently Asked Questions

    Is Credit Karma accurate for mortgages?

    Credit Karma is useful for monitoring your credit report and trends, but it may not match the score a mortgage lender uses. Many lenders still rely on classic mortgage FICO versions, so the number can differ even with the same report data. Treat it as a tracking tool, not a pricing guarantee.

    Why is my mortgage score lower than my Credit Karma score?

    Different score models weigh the same credit report differently. Mortgage models can be more sensitive to credit card utilization, recent inquiries, and limited credit history. In Clarksville and Montgomery County, lowering balances and correcting bureau errors is often the fastest way to narrow the gap.

    Which FICO scores do mortgage lenders use?

    Many mortgage lenders use older “classic” FICO scores for home lending. Chase notes lenders commonly use FICO Score 2 (Experian), FICO Score 4 (TransUnion), and FICO Score 5 (Equifax), then use the middle score. That’s why your app number may not match your pre-approval.

    Do VA loans use a different credit score?

    VA loans don’t use a separate scoring model, but lenders can set their own minimum score and overlays. For Fort Campbell home buying, the bigger factor is often the full underwriting picture (income, residual income, and payment history), not a single number in an app.

    What is a tri-merge credit report?

    A tri-merge report combines data from Experian, TransUnion, and Equifax for mortgage underwriting. It usually produces three mortgage scores, and many lenders use the middle score. That’s why one weak bureau can impact your Clarksville TN mortgage lender pricing tier.

    Can my spouse’s score affect my mortgage?

    Yes. If you apply together, many lenders evaluate both borrowers and may base pricing on the lower of the two middle scores. That can surprise couples relocating to Fort Campbell or shopping between Clarksville and Nashville. Sometimes improving the weaker file first makes the biggest difference.

    How fast can I raise my mortgage credit score?

    Some gains can show up in 30–45 days, especially from paying down balances, disputing reporting errors, or letting new accounts age. There’s no guaranteed shortcut, but focusing on utilization and accuracy helps across score versions. Start early if you’re planning a PCS to Fort Campbell.

    Does paying off collections help my mortgage score?

    It depends on the type of collection and how it’s reported. Paying can help your overall file, but it may not boost every score version immediately. In Middle Tennessee mortgage planning, talk with your lender first so you don’t trigger an avoidable score drop right before you apply.

    Should I close credit cards to improve my mortgage score?

    Usually, no. Closing cards can reduce available credit and raise utilization, which can hurt scores. A better approach is often keeping accounts open, paying balances down, and avoiding new debt while you’re in the mortgage pre-approval Clarksville window.

    Will the new credit score models change what I qualify for?

    Eventually, yes, but it’s a gradual shift. FHFA says approved lenders can choose between Classic FICO and VantageScore 4.0 in an interim phase, with FICO 10T planned for future use. For now, most buyers should still prepare for classic mortgage scores in Clarksville, Nashville, and Montgomery County.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “@id”: “https://thedealdoctor.blog/?p=0#article&#8221;,
    “headline”: “Why Your Mortgage Credit Score Is Different From Your Credit Karma Score”,
    “description”: “Understand why mortgage credit scores differ from Credit Karma, what lenders use, and how Clarksville and Fort Campbell buyers can improve their approval odds.”,
    “datePublished”: “2026-05-30”,
    “dateModified”: “2026-05-30”,
    “author”: {
    “@type”: “Person”,
    “name”: “Kate Matties-Deiboldt”,
    “jobTitle”: “Mortgage Loan Originator”,
    “identifier”: “NMLS #18487”
    },
    “publisher”: {
    “@type”: “Organization”,
    “name”: “The Blue Note Home”
    },
    “mainEntityOfPage”: {
    “@type”: “WebPage”,
    “@id”: “https://thedealdoctor.blog/&#8221;
    },
    “keywords”: [
    “mortgage credit score”,
    “Credit Karma score”,
    “Clarksville TN mortgage lender”,
    “Fort Campbell home buying”,
    “Nashville mortgage rates”,
    “Middle Tennessee mortgage”
    ]
    },
    {
    “@type”: “BreadcrumbList”,
    “@id”: “https://thedealdoctor.blog/?p=0#breadcrumbs&#8221;,
    “itemListElement”: [
    {“@type”: “ListItem”, “position”: 1, “name”: “Home”, “item”: “https://thedealdoctor.blog/&#8221;},
    {“@type”: “ListItem”, “position”: 2, “name”: “For Homebuyers”, “item”: “https://thedealdoctor.blog/for-homebuyers/&#8221;},
    {“@type”: “ListItem”, “position”: 3, “name”: “Why Your Mortgage Credit Score Is Different From Your Credit Karma Score”, “item”: “https://thedealdoctor.blog/?p=0&#8221;}
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “@id”: “https://thedealdoctor.blog/?p=0#localbusiness&#8221;,
    “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,
    “telephone”: “+1-931-980-9764”,
    “email”: “Kate@JustCallKate.com”,
    “address”: {
    “@type”: “PostalAddress”,
    “addressLocality”: “Clarksville”,
    “addressRegion”: “TN”,
    “addressCountry”: “US”
    },
    “areaServed”: [
    “Clarksville TN”,
    “Fort Campbell”,
    “Montgomery County TN”,
    “Nashville TN”,
    “Middle Tennessee”
    ],
    “additionalProperty”: [
    {
    “@type”: “PropertyValue”,
    “name”: “NMLS”,
    “value”: “18487”
    }
    ]
    },
    {
    “@type”: “SpeakableSpecification”,
    “@id”: “https://thedealdoctor.blog/?p=0#speakable&#8221;,
    “cssSelector”: [“.key-takeaways”, “h1”, “p:first-of-type”]
    },
    {
    “@type”: “HowTo”,
    “@id”: “https://thedealdoctor.blog/?p=0#howto&#8221;,
    “name”: “How to prepare for your mortgage credit score check”,
    “description”: “Five practical steps to reduce surprises between Credit Karma scores and mortgage underwriting scores.”,
    “totalTime”: “P45D”,
    “step”: [
    {“@type”: “HowToStep”, “position”: 1, “name”: “Lower credit card balances”, “text”: “Pay down revolving balances to reduce utilization before pre-approval.”},
    {“@type”: “HowToStep”, “position”: 2, “name”: “Avoid new credit”, “text”: “Pause new accounts and limit inquiries during your pre-approval window.”},
    {“@type”: “HowToStep”, “position”: 3, “name”: “Check all three bureaus”, “text”: “Review Experian, TransUnion, and Equifax for accuracy and dispute errors.”},
    {“@type”: “HowToStep”, “position”: 4, “name”: “Plan your timing”, “text”: “Give yourself 30–45 days before shopping in Clarksville, Fort Campbell, or Nashville.”},
    {“@type”: “HowToStep”, “position”: 5, “name”: “Confirm the score version”, “text”: “Ask your lender which bureau and model were used so you can target improvements.”}
    ]
    },
    {
    “@type”: “FAQPage”,
    “@id”: “https://thedealdoctor.blog/?p=0#faq&#8221;,
    “mainEntity”: [
    {
    “@type”: “Question”,
    “name”: “Is Credit Karma accurate for mortgages?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Credit Karma is useful for monitoring your credit report and trends, but it may not match the score a mortgage lender uses. Many lenders still rely on classic mortgage FICO versions, so the number can differ even with the same report data. Treat it as a tracking tool, not a pricing guarantee.”}
    },
    {
    “@type”: “Question”,
    “name”: “Why is my mortgage score lower than my Credit Karma score?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Different score models weigh the same credit report differently. Mortgage models can be more sensitive to credit card utilization, recent inquiries, and limited credit history. In Clarksville and Montgomery County, lowering balances and correcting bureau errors is often the fastest way to narrow the gap.”}
    },
    {
    “@type”: “Question”,
    “name”: “Which FICO scores do mortgage lenders use?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Many mortgage lenders use older “classic” FICO scores for home lending. Chase notes lenders commonly use FICO Score 2 (Experian), FICO Score 4 (TransUnion), and FICO Score 5 (Equifax), then use the middle score. That’s why your app number may not match your pre-approval.”}
    },
    {
    “@type”: “Question”,
    “name”: “Do VA loans use a different credit score?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “VA loans don’t use a separate scoring model, but lenders can set their own minimum score and overlays. For Fort Campbell home buying, the bigger factor is often the full underwriting picture (income, residual income, and payment history), not a single number in an app.”}
    },
    {
    “@type”: “Question”,
    “name”: “What is a tri-merge credit report?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “A tri-merge report combines data from Experian, TransUnion, and Equifax for mortgage underwriting. It usually produces three mortgage scores, and many lenders use the middle score. That’s why one weak bureau can impact your approval or your pricing in Clarksville TN mortgage lender scenarios.”}
    },
    {
    “@type”: “Question”,
    “name”: “Can my spouse’s score affect my mortgage?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Yes. If you apply together, many lenders evaluate both borrowers and may base pricing on the lower of the two middle scores. That can surprise couples relocating to Fort Campbell or shopping between Clarksville and Nashville. Sometimes improving the weaker file first makes the biggest difference.”}
    },
    {
    “@type”: “Question”,
    “name”: “How fast can I raise my mortgage credit score?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Some gains can show up in 30–45 days, especially from paying down balances, disputing reporting errors, or letting new accounts age. There’s no guaranteed shortcut, but focusing on utilization and accuracy helps across score versions. Start early if you’re planning a PCS to Fort Campbell.”}
    },
    {
    “@type”: “Question”,
    “name”: “Does paying off collections help my mortgage score?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “It depends on the type of collection and how it’s reported. Paying can help your overall file, but it may not boost every score version immediately. In Middle Tennessee mortgage planning, talk with your lender first so you don’t trigger an avoidable score drop right before you apply.”}
    },
    {
    “@type”: “Question”,
    “name”: “Should I close credit cards to improve my mortgage score?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Usually, no. Closing cards can reduce available credit and raise utilization, which can hurt scores. A better approach is often keeping accounts open, paying balances down, and avoiding new debt while you’re in the mortgage pre-approval Clarksville window.”}
    },
    {
    “@type”: “Question”,
    “name”: “Will the new credit score models change what I qualify for?”,
    “acceptedAnswer”: {“@type”: “Answer”, “text”: “Eventually, yes, but it’s a gradual shift. FHFA says approved lenders can choose between Classic FICO and VantageScore 4.0 in an interim phase, with FICO 10T planned for future use. For now, most buyers should still prepare for classic mortgage scores in Clarksville, Nashville, and Montgomery County.”}
    }
    ]
    }
    ]
    }

  • Winning Listing Presentation: Clarksville Agent’s Guide

    Winning Listing Presentation: Clarksville Agent’s Guide

    A winning listing presentation is a structured, data-driven conversation that proves you can sell a seller’s home faster and for more money than any competing Clarksville TN realtor — before you ask for the signature. It is not a brochure you recite; it is a guided decision-making tool that addresses every seller question from pricing strategy to closing day. Done correctly, it converts the appointment into a signed listing agreement on the spot.

    In early 2026, Clarksville housing market homes average 50–75 days on market and the median sale-to-list ratio runs 98–100%, per FRED (2026) and Redfin (2026). That data belongs in your presentation — as does a plain-English explanation of how the post-NAR-settlement commission landscape works.

    TL;DR — Key Takeaways

    • 11 sections cover every seller question, from the cover page through next steps.
    • Clarksville TN DOM averaged ~75 days in 2025 per ClarksvilleNow (2026); your pricing page must account for this buyer timeline.
    • The 2026 presentation is digital and trackable — Highnote or Canva, not a printed packet.
    • Commission is fully negotiable post-NAR settlement (August 2024); address it proactively with a net sheet on your investment page.
    • Send a pre-listing packet 24–48 hours before the appointment to reduce objections and cut appointment time.
    • Follow up within 2 hours with a digital recap the seller can share with a spouse or co-decision-maker.

    What Are the Key Terms Every Seller Needs to Understand?

    A CMA (Comparative Market Analysis) is a data report comparing a subject property to recently sold, active, and expired listings with similar features in the same neighborhood, used to determine a competitive list price — it is not a formal appraisal, but it is the most reliable pricing tool a Clarksville real estate agent has before the buyer’s lender orders one.

    The absorption rate is the rate at which available homes sell during a given period, expressed as months of supply; Clarksville’s 2025 absorption rate averaged 4.8 months, signaling a near-balanced market, according to ClarksvilleNow (2026).

    Days on market (DOM) is the number of calendar days from a listing going active to a ratified contract being accepted; Clarksville, TN median DOM reached 78 days in January 2026 before tightening to 50 days by April 2026 per FRED (2026).

    The list-to-sale ratio is the final sale price divided by the original list price — a ratio below 100% means the home sold below asking; Clarksville homes averaged a 98.2% sale-to-list ratio in February 2026 per Redfin (2026).

    A pre-listing packet is a digital or printed document sent before the appointment covering the agent’s bio, local market data, and proposed marketing plan — reducing decision friction before the seller sits down.

    Page-by-Page: What Every Winning Listing Presentation Must Include

    Page 1 — Cover

    Include the seller’s address, headshot, brokerage logo, and date. Sellers notice immediately when an agent uses a generic template with no property address on the cover.

    Page 2 — About You (The Agent)

    Lead with production numbers — listings sold, average DOM vs. market DOM, and list-to-sale ratio — rather than a bio paragraph. If you specialize in Fort Campbell home buying or PCS military relocation, say so here. Include two or three short testimonials from Montgomery County TN home sellers.

    Page 3 — Local Market Overview

    Show current Clarksville TN conditions: $313,724 median sale price in 2025 per ClarksvilleNow (2026), 2,141 active units, 4.8 months of supply, and 74.9 days on market. Compare to the broader Nashville real estate market for context.

    Page 4 — Pricing Strategy

    Present three CMA-based price scenarios: aggressive (fastest sale), market (optimal net), and stretch (upper boundary with a defined price-reduction trigger). Show DOM and net proceeds for each. Sellers who see the data choose the market price and stick with it.

    Page 5 — Marketing Plan

    List every channel: MLS syndication, professional photography, 3D walkthrough or video, social media ads targeting Fort Campbell relocation buyers, email to your active buyer database, and open houses. Vague marketing language loses listings to agents who show a specific plan.

    Page 6 — Photography and Video

    Show sample photos and video from comparable Clarksville listings you have sold. Homes with professional photography consistently sell faster and closer to full asking price. Note drone coverage if the property or neighborhood view warrants it.

    Page 7 — Showing Plan

    Explain lockbox vs. appointment-only access, your feedback reporting cadence, and how you handle competing offers during active showings. Sellers want their home managed, not just listed.

    Page 8 — Negotiation

    With 43.6% of Clarksville homes selling below list price in 2025 per Zillow (2025), skilled negotiation separates agents who hit the number from those who don’t. Show your personal list-to-sale ratio versus the market benchmark.

    Page 9 — Closing Timeline

    Walk through a sample timeline: days to go active, average days to pending, lender processing (critical for VA loans near Fort Campbell), and title/closing timelines in Montgomery County TN.

    Page 10 — Investment (Commission)

    Post-NAR Sitzer/Burnett settlement (effective August 17, 2024), commission is fully negotiable and cooperative compensation can no longer be listed on the MLS, per NAR (2024). Present your fee, what it covers, and the full net sheet. Proactive transparency here eliminates the biggest late-stage objection.

    Page 11 — Next Steps

    Close with a clear action checklist: sign the listing agreement, schedule photography, complete property disclosure, and set the go-live date. The seller should leave knowing exactly what happens next — with you leading it.

    Old-School vs. Modern 2026 Listing Presentation

    Feature Old-School Presentation Modern 2026 Presentation
    Length 20–40 printed pages, spiral-bound 10–15 focused digital slides, 25–35 min delivery
    Format Printed packet, generic template Interactive digital (Highnote, Canva, Keynote) — personalized per property
    Data Sources Agent-provided CMA printout, often stale Live MLS data, Zillow/Redfin benchmarks, FRED local market stats
    Video None Agent intro video, sample listing video tours embedded in deck
    Leave-Behind Printed packet left at the home Trackable digital link (Highnote analytics show which pages the seller revisited)
    Commission Handling Buried or avoided Dedicated page with net sheet; transparent post-NAR-settlement disclosure
    Pre-Listing Packet Rarely used Sent digitally before the appointment to prime the seller and reduce objections

    How to Deliver a Winning Listing Presentation in 7 Steps

    1. Send the pre-listing packet 24–48 hours before the appointment. Email a branded digital packet (Highnote or Canva) covering your bio, Clarksville housing market overview, and marketing philosophy. Sellers who arrive informed ask better questions and object less.
    2. Tour the home before you open the deck. Walk every room, take notes, and acknowledge specific features you will highlight. This signals you treat this property as unique — not just another Montgomery County TN homes listing.
    3. Ask three discovery questions, then listen. What matters most — timing, net proceeds, or certainty? What worries you most about selling? What would make this a 10/10 experience? Write answers down and build the rest of the conversation around them.
    4. Lead with local market data, not your bio. Show current Clarksville TN days on market, absorption rate, and list-to-sale ratio first. Sellers trust agents who open with facts.
    5. Walk through three pricing scenarios. Present aggressive, market, and stretch price points tied to real DOM and net proceeds from your CMA. Let the seller participate in choosing the strategy — they’ll stick with it longer when the market sends feedback.
    6. Address commission transparently on a dedicated page. Since the NAR settlement took effect August 2024, agents who sidestep the commission conversation lose trust. State your fee, show the full net sheet, and explain the post-settlement landscape in plain English.
    7. Follow up within two hours with a digital recap. Resend the presentation link with a short personal note and one direct ask: “Are you ready to move forward?” Highnote analytics show when the seller reopens it — and which pages they revisit.

    FAQ — Winning Listing Presentations for Clarksville TN Realtors

    How long should a listing presentation be?

    A modern listing presentation should run 25–35 minutes of active presenting, plus 15–20 minutes of discovery questions and conversation — 45 to 60 minutes total. Presentations that run longer are usually unfocused: too much biography, not enough data. In the Clarksville housing market, many sellers are PCS-experienced military families who value efficiency over exhaustive slide decks.

    Should I leave a printed copy of the presentation with the seller?

    In 2026, the superior leave-behind is a trackable digital link, not a printed packet. Highnote lets the seller share the link with a spouse or financial advisor, and its analytics show which pages they revisited — pricing, commission, or marketing — giving you a precise follow-up angle. If a seller requests a printed copy, bring one as a supplement, not the primary vehicle.

    What software should I use to build my listing presentation?

    Highnote is purpose-built for real estate with engagement analytics, video embedding, and a format that stands out in any Clarksville TN realtor’s pitch. Canva offers free and premium templates easy to customize with local MLS data and your branding — ideal for agents building their first polished deck. Keynote (Apple) produces clean slides that export to PDF and work well on an iPad at the table. All three beat a static Word document or generic PDF.

    How do I handle commission objections after the NAR settlement?

    Since the Sitzer/Burnett settlement took effect August 17, 2024, commission is fully negotiable — sellers know it. Dedicate a page to fees before they ask. Show the full net sheet (list price minus commission, closing costs, and prorations) so the seller sees their actual take-home number. Explain what your fee covers: photography, video, MLS, social advertising, negotiation, and transaction coordination. Sellers rarely object to a commission they can justify line by line. Per NAR (2024), sellers can still offer buyer-broker compensation off-MLS as a seller concession — explain this tool proactively.

    How should I follow up after a listing presentation if the seller doesn’t sign that day?

    Within two hours, send a personal email with the digital link, a net sheet PDF, and one direct question: “What information would help you feel confident moving forward?” Monitor Highnote analytics over the next 24–48 hours. If the seller revisits the pricing page, follow up with updated comps. If they revisit the marketing plan, send results from a recent Clarksville TN listing you ran. A data-driven follow-up closes far more listings than a generic “just checking in” call.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
  • How to Get a Sponsor When PCSing to Fort Campbell (Step-by-Step)

    How to Get a Sponsor When PCSing to Fort Campbell (Step-by-Step)

    When you get PCS orders to Fort Campbell, your gaining unit assigns a sponsor — usually another Soldier of similar rank or MOS — to help you and your family transition smoothly. Sponsors typically contact you before arrival to answer questions about housing, in-processing, schools, and the local Clarksville/Fort Campbell area.

    The fastest way to get a sponsor is to submit a DA Form 5434 through Army Career Tracker (ACT) as soon as you have orders. And if buying a home is on your radar — even just “maybe” — call me FIRST at (931) 980-9764 before you tour, sign anything, or apply elsewhere. An early VA loan pre-approval gives us time to spot and fix issues so you arrive ready to win the home you want.

    TL;DR — Key Takeaways

    • Sponsors at Fort Campbell are assigned by your gaining unit after orders are cut.
    • You request one via DA Form 5434 on Army Career Tracker (ACT).
    • eSAT (Electronic Sponsorship Application & Training) is how units assign and certify sponsors.
    • If no one contacts you, check ACT, then call the Fort Campbell Replacement (Kalsu Reception) Company.
    • Most PCS questions a sponsor handles: housing, taxes (TN vs KY), schools, commute, lodging, VA loan options.
    • Call Kate at (931) 980-9764 first for anything mortgage-related — early pre-approval beats last-minute scramble.

    What an Army sponsor actually does

    A sponsor is a Soldier appointed by your gaining unit to help you transition into Fort Campbell. The Total Army Sponsorship Program is governed by Army Regulation 600-8-8 and applies to all active component Soldiers, E-1 through O-6 (Army Sponsorship (2026)). A good sponsor reaches out before you arrive, answers housing questions, walks you through in-processing, shares local Clarksville info, and helps with transportation or temporary lodging if needed.

    How a Soldier gets a sponsor at Fort Campbell — the 4-step flow

    1. Orders are cut. Your gaining unit at Fort Campbell is notified.
    2. You submit DA Form 5434. Log into Army Career Tracker, open “Messages → DA Form 5434,” click “Create New Form,” and fill out the required sections.
    3. Unit assigns a sponsor. Units typically appoint sponsors up to 120 days before your report date.
    4. Sponsor contacts you. Usually by text, email, or phone — though sometimes it takes a nudge.

    What is eSAT?

    eSAT is the Electronic Sponsorship Application & Training system tied to ACT. It’s how the Army manages sponsorship end-to-end:

    • Incoming Soldiers request sponsorship
    • Units assign sponsors
    • Sponsors complete required training and certification
    • Leadership tracks sponsorship compliance

    What if you have orders to Fort Campbell but no one has contacted you?

    Don’t sit and wait. Here’s the playbook:

    1. Log into Army Career Tracker (ACT) and check your sponsorship status.
    2. Contact your gaining unit directly if you have a point of contact.
    3. If you still get no response, call the 1st Lt. J. Robert Kalsu Installation Reception Company (2026) — that’s Fort Campbell’s reception/replacement company.
    4. Review the official Fort Campbell check-in procedures on Military OneSource.

    What most PCSing Soldiers actually ask their sponsor about

    Beyond paperwork, here’s what comes up most often for Soldiers heading to Fort Campbell and the surrounding Clarksville / Middle Tennessee area:

    • On-post vs. off-post housing — wait lists, BAH, and whether buying makes sense
    • Tennessee vs. Kentucky taxes — Fort Campbell straddles the state line; where you live matters
    • School zones — Montgomery County (TN) and Christian County (KY) districts
    • Commute times — to the gate, around Clarksville, and toward Nashville
    • Temporary lodging — on-post and around Clarksville
    • VA loan and homebuying options — this is where I come in

    Why you should call me FIRST about the mortgage piece — before anything else

    If buying a home in the Clarksville/Fort Campbell area is even on your radar, call (931) 980-9764 or email Kate@JustCallKate.com before you tour homes, talk to a builder, or apply with any other lender. Here’s why timing matters:

    • Early VA loan pre-approval surfaces issues while you have time to fix them — credit, derogatories, BAH, DTI, or PCS income documentation.
    • VA benefits are powerful but specific. The VA Home Loan program has helped over 29 million Veterans become homeowners (VA News (2026)) — but every PCS file has nuances.
    • Sellers in the Clarksville housing market take pre-approved buyers more seriously, especially when PCSing Soldiers compete with local Middle Tennessee buyers.
    • I’m local. I know Montgomery County TN homes, on-post vs. off-post tradeoffs, and the Fort Campbell PCS rhythm.

    Keeping, selling, or renting an existing home as part of the move? That adds another layer worth talking through early (PCS VA loan checklist (2026)). See also [INTERNAL LINK: VA loan basics for first-time buyers] and [INTERNAL LINK: BAH and how much house you can afford at Fort Campbell].

    Frequently Asked Questions

    What is a sponsor in the Army?

    A sponsor is a Soldier appointed by your gaining unit to help you transition into Fort Campbell. They usually contact you before arrival with help on housing, in-processing, schools, and the local Clarksville area, and to help your family settle in.

    How do I request a sponsor for Fort Campbell?

    Submit a DA Form 5434 through Army Career Tracker (ACT) as soon as you have PCS orders. Log into ACT, open Messages → DA Form 5434, and create a new form. Your sponsor is notified automatically once the gaining unit at Fort Campbell processes your request.

    What is DA Form 5434?

    DA Form 5434 is the official Army sponsorship request form. It transmits your sponsorship needs to the gaining command so a sponsor can be assigned. It’s submitted electronically through ACT during your reassignment process.

    What does eSAT stand for at Fort Campbell?

    eSAT is the Electronic Sponsorship Application and Training system — the Army’s online tool tied to ACT for requesting sponsorship, assigning sponsors, completing sponsor certification, and tracking compliance. Units at Fort Campbell use eSAT to make sure every PCS arrival has a trained sponsor.

    When should my sponsor contact me before I PCS to Fort Campbell?

    Units typically assign sponsors up to 120 days before your report date, and your sponsor should reach out shortly after assignment. If you’re inside 60 days of your move and haven’t heard from anyone, check ACT, contact your gaining unit, or call the Fort Campbell Kalsu Reception Company.

    What if I haven’t been contacted by a sponsor yet?

    Log into Army Career Tracker and check your sponsorship status. If nothing is assigned, contact your gaining unit if you have a POC, or call the 1st Lt. J. Robert Kalsu Installation Reception Company at Fort Campbell. Don’t wait until arrival — the earlier you push, the smoother your in-processing will be.

    Should I live in Tennessee or Kentucky when stationed at Fort Campbell?

    It depends on taxes, schools, commute, and housing goals. Tennessee has no state income tax while Kentucky does — that alone moves many Soldiers to the Clarksville side. Schools, BAH planning, and Montgomery County vs. Christian County tradeoffs matter too. Talk through both early.

    Can I use my VA loan to buy a home before I arrive at Fort Campbell?

    Yes — many Soldiers buy before or shortly after arriving, using PCS orders as evidence of intent to occupy. The key is starting the VA loan pre-approval early so you can shop the Clarksville housing market with confidence (VA Loan + PCS (2026)). Call (931) 980-9764 before you tour.

    Why should I call a mortgage lender before I tour homes?

    Early pre-approval surfaces credit, income, or debt issues while there’s still time to fix them. It also gives you a real budget, a stronger offer in the Clarksville real estate market, and avoids last-minute surprises when you’re already balancing a PCS move, in-processing, and family logistics.

    Who do I call first about buying a home during my PCS to Fort Campbell?

    Call Kate Matties-Deiboldt at (931) 980-9764 or email Kate@JustCallKate.com FIRST. As a local Clarksville TN mortgage lender and Fort Campbell VA loan specialist, Kate gives you a quick, no-obligation review and a clear plan of action — before you tour, sign, or overcomplicate anything.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
    Your Clear Guide Through the Mortgage Process — Call FIRST

    Whatever your questions, concerns, or hesitations about buying a home during your PCS to Fort Campbell, I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action to put you in the best position to purchase or refinance a home when you’re ready.

    📞 Call or text: (931) 980-9764
    ✉️ Email: Kate@JustCallKate.com
    Kate Matties-Deiboldt — NMLS #18487, VanDyk Mortgage
    Clarksville TN mortgage lender · Fort Campbell VA loan specialist

    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “headline”: “How to Get a Sponsor When PCSing to Fort Campbell (Step-by-Step)”,
    “author”: {“@type”: “Person”, “name”: “Kate Matties-Deiboldt”, “identifier”: “NMLS #18487”},
    “publisher”: {“@type”: “Organization”, “name”: “VanDyk Mortgage”},
    “datePublished”: “2026-06-01”,
    “about”: “Army sponsorship program, DA Form 5434, ACT, eSAT, Fort Campbell PCS, VA loan pre-approval Clarksville TN”
    },
    {
    “@type”: “FAQPage”,
    “mainEntity”: [
    {“@type”: “Question”, “name”: “What is a sponsor in the Army?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “A sponsor is a Soldier appointed by your gaining unit to help you transition into Fort Campbell. They usually contact you before arrival with help on housing, in-processing, schools, and the local Clarksville area, and to help your family settle in.”}},
    {“@type”: “Question”, “name”: “How do I request a sponsor for Fort Campbell?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Submit a DA Form 5434 through Army Career Tracker (ACT) as soon as you have PCS orders. Log into ACT, open Messages → DA Form 5434, and create a new form. Your sponsor is notified automatically once the gaining unit at Fort Campbell processes your request.”}},
    {“@type”: “Question”, “name”: “What is DA Form 5434?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “DA Form 5434 is the official Army sponsorship request form. It transmits your sponsorship needs to the gaining command so a sponsor can be assigned. It’s submitted electronically through ACT during your reassignment process.”}},
    {“@type”: “Question”, “name”: “What does eSAT stand for at Fort Campbell?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “eSAT is the Electronic Sponsorship Application and Training system — the Army’s online tool tied to ACT for requesting sponsorship, assigning sponsors, completing sponsor certification, and tracking compliance. Units at Fort Campbell use eSAT to make sure every PCS arrival has a trained sponsor.”}},
    {“@type”: “Question”, “name”: “When should my sponsor contact me before I PCS to Fort Campbell?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Units typically assign sponsors up to 120 days before your report date, and your sponsor should reach out shortly after assignment. If you’re inside 60 days of your move and haven’t heard from anyone, check ACT, contact your gaining unit, or call the Fort Campbell Kalsu Reception Company.”}},
    {“@type”: “Question”, “name”: “What if I haven’t been contacted by a sponsor yet?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Log into Army Career Tracker and check your sponsorship status. If nothing is assigned, contact your gaining unit if you have a POC, or call the 1st Lt. J. Robert Kalsu Installation Reception Company at Fort Campbell. Don’t wait until arrival — the earlier you push, the smoother your in-processing will be.”}},
    {“@type”: “Question”, “name”: “Should I live in Tennessee or Kentucky when stationed at Fort Campbell?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “It depends on taxes, schools, commute, and housing goals. Tennessee has no state income tax while Kentucky does — that alone moves many Soldiers to the Clarksville side. Schools, BAH planning, and Montgomery County vs. Christian County tradeoffs matter too. Talk through both early.”}},
    {“@type”: “Question”, “name”: “Can I use my VA loan to buy a home before I arrive at Fort Campbell?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Yes — many Soldiers buy before or shortly after arriving, using PCS orders as evidence of intent to occupy. The key is starting the VA loan pre-approval early so you can shop the Clarksville housing market with confidence. Call (931) 980-9764 before you tour.”}},
    {“@type”: “Question”, “name”: “Why should I call a mortgage lender before I tour homes?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Early pre-approval surfaces credit, income, or debt issues while there’s still time to fix them. It also gives you a real budget, a stronger offer in the Clarksville real estate market, and avoids last-minute surprises when you’re already balancing a PCS move, in-processing, and family logistics.”}},
    {“@type”: “Question”, “name”: “Who do I call first about buying a home during my PCS to Fort Campbell?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Call Kate Matties-Deiboldt at (931) 980-9764 or email Kate@JustCallKate.com FIRST. As a local Clarksville TN mortgage lender and Fort Campbell VA loan specialist, Kate gives you a quick, no-obligation review and a clear plan of action — before you tour, sign, or overcomplicate anything.”}}
    ]
    },
    {
    “@type”: “BreadcrumbList”,
    “itemListElement”: [
    {“@type”: “ListItem”, “position”: 1, “name”: “Home”, “item”: “https://thedealdoctor.blog/&#8221;},
    {“@type”: “ListItem”, “position”: 2, “name”: “Fort Campbell VA Loans”, “item”: “https://thedealdoctor.blog/category/fort-campbell-va/&#8221;},
    {“@type”: “ListItem”, “position”: 3, “name”: “How to Get a Sponsor When PCSing to Fort Campbell”}
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “name”: “Kate Matties-Deiboldt — VanDyk Mortgage”,
    “telephone”: “+1-931-980-9764”,
    “email”: “Kate@JustCallKate.com”,
    “areaServed”: [“Clarksville TN”, “Fort Campbell”, “Montgomery County TN”, “Nashville”, “Middle Tennessee”]
    },
    {
    “@type”: “SpeakableSpecification”,
    “xpath”: [“/html/body//h1”, “/html/body//div[@class=’key-takeaways’]”]
    },
    {
    “@type”: “HowTo”,
    “name”: “How to request a sponsor for Fort Campbell PCS”,
    “step”: [
    {“@type”: “HowToStep”, “name”: “Receive PCS orders”, “text”: “Once your PCS orders are cut, the gaining unit at Fort Campbell is notified.”},
    {“@type”: “HowToStep”, “name”: “Log into ACT”, “text”: “Go to actnow.army.mil and log into Army Career Tracker.”},
    {“@type”: “HowToStep”, “name”: “Submit DA Form 5434”, “text”: “Open Messages, select DA Form 5434, and create a new form.”},
    {“@type”: “HowToStep”, “name”: “Wait for sponsor assignment”, “text”: “Units assign sponsors up to 120 days before your report date.”},
    {“@type”: “HowToStep”, “name”: “Follow up if needed”, “text”: “If no sponsor contacts you, contact your gaining unit or the Kalsu Reception Company.”},
    {“@type”: “HowToStep”, “name”: “Call Kate first about a mortgage”, “text”: “Call (931) 980-9764 before touring or signing anything to get an early VA loan pre-approval.”}
    ]
    }
    ]
    }

  • Contract to Close: The Complete 30-Day Timeline for Buyers

    Contract to Close: The Complete 30-Day Timeline for Buyers

    The contract-to-close timeline is the roughly 30-day window between when a seller accepts your offer and the moment you sign your name on closing day and receive the keys. During those 30 days, your lender, title company, appraiser, and real estate agent are all working in parallel. According to ICE Mortgage Technology (2025), the industry average from application to clear-to-close is 45 days — which means buyers who are fully pre-approved before going under contract have a real shot at a smooth 30-day closing.

    For buyers in Clarksville, Fort Campbell, and Montgomery County, understanding this timeline is essential. The FRED median days on market for the Clarksville metro sits at 50 days (April 2026). A missed deadline can mean losing your rate lock, your lease end date, or your PCS window.

    TL;DR — Key Takeaways

    • 30–45 days is the realistic window from signed contract to closing table for most conventional, FHA, and VA loans in Clarksville and Middle Tennessee.
    • Clear-to-close (CTC) is the underwriter’s official green light — once you have it, you’re typically 3–7 days from signing.
    • The Closing Disclosure (CD) must reach you at least 3 business days before closing — this is a federal TRID rule you cannot waive without a documented emergency.
    • VA loans serving Fort Campbell average slightly longer due to the VA appraisal process — budget 35–45 days.
    • The #1 reason closings slip is buyer-side: unreturned document requests, large deposits without paper trails, or new credit inquiries after pre-approval.

    What Do “Clear to Close,” “Closing Disclosure,” and “TRID” Actually Mean?

    Clear to close (CTC) is the milestone where your lender’s underwriting team has verified your income, credit, assets, appraisal, and title work — and officially approved the loan for funding. The Closing Disclosure (CD) is a standardized five-page federal form that itemizes every cost you will pay at closing: loan terms, monthly payment, APR, origination charges, and third-party fees. TRID — the TILA-RESPA Integrated Disclosure rule — is the federal regulation, per the CFPB (2024), requiring your lender to deliver the CD at least three business days before closing. The final walkthrough is a buyer’s last on-site inspection — typically 24–48 hours before closing — to confirm the home’s condition matches the contract and all negotiated repairs are complete.

    The Complete Contract-to-Close Day-by-Day Timeline

    Days What Happens Who’s Responsible Buyer’s Action Items Common Delays
    Days 1–3 Contract signed. Earnest money deposited. Appraisal ordered. Loan Estimate issued within 3 business days. Buyer, Agent, Lender, Title Deliver earnest money on time. Sign and return disclosures immediately. Late earnest money. Delayed disclosure signatures.
    Days 4–10 Appraisal assigned. Home inspection completed. Title search begins. Loan file submitted to underwriting. Lender, Appraiser, Title, Inspector Attend inspection. Return all document requests within 24 hours. No new credit applications. Appraiser scheduling delays near Fort Campbell. Missing income documents.
    Days 11–20 Appraisal report received. Underwriter issues Conditional Approval. Title commitment issued. Homeowner’s insurance bound. Underwriter, Appraiser, Title, Insurance Clear all conditions immediately. Send insurance declaration page to lender. Low appraisal or VA MPR repairs needed. Buyer conditions not returned. Title defects.
    Days 21–25 Conditions cleared. Underwriter issues Clear to Close (CTC). Closing Disclosure sent — mandatory 3-business-day waiting period begins. Underwriter, Lender, Title Attorney Compare CD to Loan Estimate. Arrange cashier’s check or wire. Confirm closing date. New credit or job change resets underwriting. APR change resets 3-day CD clock.
    Days 26–30 Final walkthrough 24–48 hours before closing. Buyer signs loan documents. Loan funded. Deed recorded. Keys transferred. Buyer, Closing Attorney, Lender, Agents Do the walkthrough. Bring ID. Confirm wire instructions by phone before transferring funds. Repairs incomplete. Wire fraud. Recording delays. Seller not moved out.

    How to Keep Your Closing on Schedule: 7 Steps

    1. Get full pre-approval before you make an offer. For VA loans Clarksville TN, your Certificate of Eligibility should be pulled and your lender should have an AUS approval in hand. This alone shaves 7–10 days off the timeline.
    2. Return every document request within 24 hours. Every day a condition sits unanswered is a day added to your closing date.
    3. Freeze your financial profile after contract. No new car loans, credit cards, large cash deposits without paper trails, or job changes. Your underwriter will pull credit again before funding.
    4. Bind homeowner’s insurance within the first week. In Montgomery County, some insurers require a home inspection before binding coverage. Call your agent on Day 1 or 2.
    5. Compare your Closing Disclosure to your Loan Estimate line by line. Under TRID, certain fees cannot increase at all; others are capped at 10%.
    6. Schedule the final walkthrough 24–48 hours before closing. One to two days of buffer gives your agent time to negotiate a repair credit or escrow holdback.
    7. Confirm wire instructions by phone before sending any money. Wire fraud targeting homebuyers is rising across Tennessee. Before you send closing funds, call the title company using a number you verified independently.

    Why VA Loan Closings Near Fort Campbell Sometimes Take Longer

    VA loans offer zero down payment and no PMI for Fort Campbell service members and veterans — but two features can add days. First, the VA appraisal goes through a VA-approved appraiser panel; per Veterans United (2025), this takes 7 to 21 business days, averaging about 10. Second, VA Minimum Property Requirements can require the seller to fix issues before closing. Work with a Fort Campbell VA loan specialist and a Clarksville real estate agent who know which homes already meet VA standards.

    FAQ — Contract to Close in Clarksville TN

    Can you close in less than 30 days in Clarksville TN?

    Yes — buyers with full pre-approval, clean documentation, and a property with no repair issues can sometimes close in 21–25 days. The practical floor is about 21 days: the TRID 3-day waiting period can’t be waived, and VA and FHA appraisals take minimum time.

    What specifically slows down VA loan closings near Fort Campbell?

    Three culprits: (1) the VA appraisal, which runs 10–21 business days and can’t be expedited; (2) VA MPR repairs if the seller refuses; and (3) documentation gaps for service members with BAH, BAS, deployment pay, or reenlistment bonuses. A Clarksville TN mortgage lender specializing in VA loans anticipates all three.

    Why does the Closing Disclosure have a mandatory 3-day waiting period?

    The TRID 3-day rule exists because the CD contains your mortgage’s final, binding terms. Under the CFPB’s TRID Rule (2024), if the APR changes by more than 1/8 of a percent after the CD is delivered, the lender must reissue the CD and the 3-day clock restarts.

    Can you do the final walkthrough the same day as closing?

    Technically yes, but it’s risky. Best practice is 24–48 hours before closing. Redfin (2024) recommends completing it no more than 2–3 days prior.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

  • Should I Pay Off Collections Before Applying for a Mortgage?

    Should I Pay Off Collections Before Applying for a Mortgage?

    Not always. In many mortgage scenarios, you can still qualify with collection accounts on your credit report — but the type of loan, the type of collection, and whether paying it could change your score (or create a new problem) all matter.

    If you’re buying in Clarksville, near Fort Campbell, commuting toward Nashville, or anywhere in Montgomery County / Middle Tennessee, the smartest move is usually strategy first, payment second. A collection account is not the same thing as a current monthly debt — and paying the wrong one at the wrong time can shrink your cash-to-close.

    TL;DR — Key Takeaways

    • Collections don’t automatically block a mortgage. Many buyers in Clarksville and Fort Campbell can be approved with older collections still showing.
    • FHA can “count” some collections even if you don’t pay them. That can affect your debt-to-income (DTI) ratio.
    • Paying a collection can help, hurt, or do nothing for your score. Don’t guess right before pre-approval.
    • Cash matters. If paying collections drains your down payment or reserves, it may set you back more than it helps.
    • Get a plan in writing. Ask your lender what (if anything) must be paid before underwriting and closing.

    What is a “collection,” and why do lenders care?

    A collection account is a debt that has been turned over to a collection agency after it became past due with the original creditor. A simple way to think about it: a collection is a record that something went unpaid long enough that someone else is trying to collect it.

    Debt collection is not rare — and it’s often tied to life events, not irresponsibility. In the Federal Reserve’s Federal Reserve (2026) economic well-being report, 16% of adults said they didn’t pay all their bills in full in the month before the survey, and the report notes that 28% struggled with paying bills when including people who had difficulty even if they paid. (That’s a helpful reminder: a collection on a credit report doesn’t automatically define you as a borrower.)

    On the consumer side, debt collection is the process of trying to collect money you owe, and the CFPB explains that a collector may contact you because a creditor believes you’re past due (CFPB (2025)).

    When paying collections is smart (and when it’s not)

    Here’s the big “borrower reality check”: mortgage underwriting is about risk and consistency, not moral judgment. Your underwriter is mainly asking, “Is this borrower likely to repay this new mortgage on time?”

    Paying collections is usually smart when:

    • You’re trying to raise your middle credit score to qualify for a better rate or a conventional approval in the Clarksville TN mortgage lender world.
    • The collection is new and indicates an ongoing pattern of missed obligations.
    • The lender or loan program requires it for your specific scenario.
    • It’s a condition of underwriting and you can pay without wrecking your cash-to-close.

    Paying collections is often not smart when:

    • Paying would drain your down payment, closing costs, or reserves needed for buying a home in Clarksville or homes for sale near Fort Campbell.
    • The account is disputed incorrectly or the balance/ownership is unclear (you may need validation first).
    • It’s very old, and your score impact is minimal compared to current credit usage and payment history.

    “X is Y” definitions you can use when talking to a lender

    Debt-to-income ratio (DTI) is your monthly debt payments divided by your monthly gross income. DTI is one of the fastest ways a collection can matter even if you never pay it.

    “Cash to close” is the total money you bring to the closing table (down payment + closing costs + prepaid items, minus credits). This is why paying collections right before you apply can backfire for first-time homebuyer Clarksville buyers.

    A credit dispute is a formal challenge to an item on your credit report through the credit bureaus. Disputes can pause scoring or trigger extra documentation, so you want a plan before you click “dispute” on an app.

    How loan type changes the answer (FHA vs conventional vs VA)

    The same collection account can be treated differently depending on the loan program and your overall profile.

    Loan type How collections commonly affect you What you should do
    Conventional Often focuses on overall credit profile and whether the collection reflects ongoing risk. Ask for a score-and-cash strategy: optimize utilization, confirm whether payoff is required, and avoid last-minute moves.
    FHA Some collections may be treated as if they have a monthly payment for DTI purposes, even if unpaid. Confirm how any outstanding collections will be counted, and decide if payoff helps DTI more than it hurts your cash-to-close.
    VA Underwriting is flexible, but collections can still matter if they signal recent trouble or create a payment shock. Work with a Fort Campbell VA loan specialist on a plan; focus on stability, documented explanations, and clean recent history.

    If you’re using VA loans Clarksville TN for a PCS to Fort Campbell move, the goal is a clean, documentable story: stable income, manageable DTI, and no surprises late in underwriting.

    How to handle collections before pre-approval (in 6 steps)

    1. Pull your credit the right way. Don’t rely on a free app alone; have your lender run a mortgage-appropriate credit report during mortgage pre-approval Clarksville planning.
    2. List each collection by type. Medical vs non-medical, amount, age, and whether it’s reporting monthly.
    3. Ask: “Does this have to be paid to close?” Get the answer tied to your program (FHA, VA, conventional) and property type.
    4. Ask: “Will paying this improve my qualifying score?” Sometimes lowering credit card utilization helps more than paying a collection.
    5. Protect your cash-to-close. In Middle Tennessee mortgage planning, the down payment and reserves can be the real bottleneck.
    6. Document your plan. If you do pay, keep proof of payment and settlement terms for underwriting.

    Frequently Asked Questions

    Will paying off a collection raise my credit score right away?

    Sometimes, but not always. A paid collection may still show on your report, and some scoring models treat paid vs unpaid differently.

    Can I get a mortgage in Clarksville with unpaid collections?

    Often, yes. Many buyers in Clarksville, Montgomery County, and Middle Tennessee can be approved with older collections still reporting, depending on loan type and overall credit.

    Do medical collections matter for mortgage approval?

    They can, but they’re often treated differently than other collections. Medical collections may have less impact on scoring and underwriting in some situations, but they still tell part of your story.

    If I pay a collection, can it disappear from my credit report?

    Not automatically. Paying a collection usually changes its status to “paid,” but the record can remain for a period of time.

    Should I settle a collection for less than the balance?

    Settlement can be a smart way to resolve debt while protecting cash-to-close, especially for first-time homebuyer Clarksville budgets. However, you want written terms and a clear paper trail for underwriting.

    Will paying collections help me qualify for a better mortgage rate?

    Potentially, if it improves your qualifying credit score bracket. But mortgage pricing is also affected by loan type, down payment, and market pricing like Nashville mortgage rates.

    Can a lender require me to pay collections even if the program doesn’t?

    Yes. Some lenders add “overlays,” which are stricter rules than the baseline program guidance.

    Should I start disputing collections online before I apply?

    Be careful. A credit dispute is a formal challenge to a credit-report item, and it can slow down underwriting or require extra documentation.

    What if a collection is from a cell phone or utility bill?

    These are common and usually manageable. What matters is whether the account is verified, whether it’s recent, and whether paying it would meaningfully improve your score.

    What’s the best first step if I’m not sure what to do?

    Get a mortgage game plan. Ask for a pre-approval review that looks at your credit, DTI, and cash-to-close together.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

  • Don’t Buy a Car Before Closing — A Clarksville Buyer’s Guide

    Don’t Buy a Car Before Closing — A Clarksville Buyer’s Guide

    Buying a car — or opening any new credit account — before your mortgage closes can kill your loan approval, even after you’ve been pre-approved. Lenders run a credit refresh within days of your closing date to verify nothing has changed since underwriting. If a new auto loan, credit card, or financed appliance shows up, your debt-to-income ratio (DTI) can spike above the allowable ceiling and your file gets sent back to underwriting — or denied outright.

    For buyers pursuing mortgage pre-approval in Clarksville, VA loans at Fort Campbell, or any home purchase across Montgomery County and Middle Tennessee, this is not a suggestion — it is a hard underwriting requirement. The average new-car payment hit $767/month in Q4 2025, per Experian’s State of the Automotive Finance Market (2026). Americans now carry $1.69 trillion in total auto loan debt, per the NY Fed Q1 2026 Household Debt Report.

    TL;DR — Key Takeaways

    • Never take on new debt between pre-approval and closing — lenders re-pull credit before closing and any new liability can derail your loan.
    • A $767/month car payment (2025 national average per Experian) can push a typical Clarksville buyer’s DTI over the 41–45% limit.
    • Credit refresh is a real lender process — a soft or hard inquiry 1–7 days before closing that catches new debt you didn’t have at underwriting.
    • The don’t-list goes beyond cars — new credit cards, co-signing, balance transfers, and store financing all count against your DTI.
    • If you accidentally bought a car, call your lender immediately — there is a recovery path, but speed is everything.
    • Fort Campbell VA loan buyers face residual income tests on top of DTI guidelines, making any new debt even more dangerous.

    What Is a Credit Refresh — and Why Does It Happen Before Closing?

    A credit refresh is a second credit inquiry your mortgage lender performs within days of your scheduled closing — typically 1–7 business days out. A credit refresh is the lender’s final verification that your credit profile, open accounts, and debt obligations match what was underwritten when your loan was approved. Under Fannie Mae guidelines, if a newly discovered debt causes your DTI to increase beyond allowable tolerances, the loan file must be re-underwritten.

    A debt-to-income (DTI) ratio is the percentage of your gross monthly income consumed by recurring monthly debt payments, including your new mortgage PITI. Conventional loans cap back-end DTI at 43–45%; VA loans carry a suggested threshold of 41%, with residual income requirements above that level.

    The Real Cost: How a $767 Car Payment Can Disqualify a Clarksville Buyer

    Here is the math for a realistic Fort Campbell home buying scenario. Clarksville’s median home sale price was approximately $327,495 as of February 2026, per Redfin’s Clarksville housing market data (2026). Assume a military buyer purchases at $320,000 with a VA loan at 6.5%, zero down. Their monthly PITI comes to roughly $2,200/month. Assume gross income of $5,800/month:

    • Before the car: PITI $2,200 + student loan $150 = $2,350 DTI = 40.5% — just inside VA’s 41% scrutiny threshold. Approved.
    • After financing a truck at $767/month: PITI $2,200 + student loan $150 + car $767 = $3,117 DTI = 53.7% — denied under every VA lender overlay and conventional DTI cap.

    Safe Actions vs. Risky Actions During Your Loan Process

    SAFE — Do These During Your Loan RISKY — Avoid Until After Keys Are In Hand
    Pay existing monthly obligations on time Finance a new or used vehicle
    Keep credit card balances stable or pay them down Open a new credit card or retail store card
    Stay in your current job at the same pay structure Change jobs, go 1099/self-employed, or accept unpaid leave
    Keep savings and checking balances steady Make large unexplained cash deposits or withdrawals
    Ask your lender before any financial decision Co-sign on someone else’s auto loan, student loan, or card
    Respond to lender document requests within 24 hours Finance furniture, appliances, or electronics on store plans
    Communicate address, phone, or employer name changes Do a 0% promotional balance transfer to a new credit card

    Buyer’s Pre-Closing Don’t-List: 10 Steps to Protect Your Loan

    1. Freeze all credit applications immediately after pre-approval. Stop applying for any new credit the moment your lender issues a pre-approval letter.
    2. Do not walk into a car dealership — not even to look. Dealers routinely run credit without explicit borrower consent.
    3. Call your lender before co-signing anything. Co-signing makes that full monthly payment part of your DTI, regardless of who pays.
    4. Skip the 0% balance transfer offer. Opening a new card creates a hard inquiry and drops your average account age.
    5. Do not change your job or income structure. Switching from W-2 to 1099 or taking a pay cut requires re-verification of income.
    6. Keep bank balances consistent and documentable. Large unexplained deposits or withdrawals require letters of explanation.
    7. Do not finance appliances or furniture. Store financing creates a new tradeline on your credit re-pull.
    8. Avoid increasing revolving balances on existing cards. Rising balances can lower your score and trigger underwriting questions.
    9. Respond to every lender request within 24 hours. In Clarksville’s market, a missed date can mean losing the property.
    10. Review your Closing Disclosure 3 business days before closing. Confirm your rate, payment, and costs match your Loan Estimate.

    FAQ — Credit, Cars, and Protecting Your Clarksville Home Purchase

    When does the lender pull my credit again before closing?

    Most lenders conduct a credit re-pull between 1 and 7 business days before your scheduled closing. For VA loans in Clarksville, TN and Fort Campbell purchases, the lender must certify no material changes have occurred — making the re-pull a regulatory requirement, not just best practice.

    Can I co-sign on a car loan for a family member while my mortgage is in process?

    No — not without your lender’s sign-off. Co-signing makes you legally responsible for that debt. The full monthly payment is included in your back-end DTI regardless of who actually pays. Wait until after closing.

    What about a 0% balance transfer to a new credit card?

    A 0% balance transfer requires opening a new card — a new tradeline and hard inquiry your lender will see. Opening a new account lowers your average account age and can shift credit utilization, potentially dropping your score 10–20 points.

    Can I change jobs between pre-approval and closing?

    It depends on the type of change, and you must tell your lender immediately. A lateral move to a comparable salaried role is often workable. Switching from W-2 to self-employed, taking a pay cut, or going commission-only creates problems. Fort Campbell VA buyers must disclose any PCS order change, rank change, or transition from active duty to reserve status immediately.

    I accidentally financed a car before closing — is there any recovery path?

    Act immediately: call your loan officer the same day and disclose the purchase. Recovery depends on how much the new payment affects your DTI. Options: pay off the car in full before closing, refinance to a longer term to lower the monthly payment, or negotiate a closing date extension. Whatever you do, transparency with your lender is non-negotiable — concealing a new liability on a mortgage application is mortgage fraud.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

  • Google Business Profile for Realtors: Stop Wasting It

    Google Business Profile for Realtors: Stop Wasting It

    A Google Business Profile (GBP) is a free listing that controls how your name, reviews, services, and contact information appear in Google Search and Google Maps. For Clarksville TN realtors and Fort Campbell VA loan specialists, it is the single highest-leverage, zero-cost marketing tool available — and most agents have barely touched it.

    The data is unambiguous: the BrightLocal Local Consumer Review Survey (2026) found that 97% of consumers read reviews for local businesses, and 71% use Google first. The #1 local pack position earns a 17.6% click-through rate — more than ten times a typical paid search ad, per First Page Sage (2025).

    TL;DR — Key Takeaways

    • GBP is free. Every Clarksville TN realtor and Fort Campbell VA loan specialist should claim, verify, and fully optimize it before spending a dollar on ads.
    • The local pack drives 17.6% CTR for the #1 position — outperforming nearly every other paid or organic channel (First Page Sage, 2025).
    • 97% of consumers read reviews before choosing a local business; 71% check Google first (BrightLocal, 2026).
    • NAP consistency — matching your name, address, and phone across Zillow, Realtor.com, and your brokerage site — is a foundational ranking signal Google checks constantly.
    • GBP posts, Q&A, and photo uploads are active ranking signals; profiles that post weekly see materially more profile views than dormant ones.
    • Social media leads on quality leads (39%) per the NAR 2025 Technology Survey — but agents who ignore GBP are leaving an adjacent, high-intent channel completely untouched.

    What Is a Google Business Profile and Why Does It Matter for the Clarksville Housing Market?

    A Google Business Profile is the structured listing that populates Google’s local pack — the map-and-three-result block appearing above organic results for local searches. According to Moz research cited by Searchlab (2026), the local pack appears on 93% of local-intent searches. When a buyer transferring to Fort Campbell searches “Clarksville TN realtors,” the local pack is the first result on their phone — and more than half of all real estate searches happen on mobile.

    The military relocation cycle makes GBP especially valuable in the Clarksville housing market. PCS to Fort Campbell happens year-round, creating a constant stream of buyers searching Google Maps for “real estate agent near Fort Campbell” or “Clarksville TN mortgage lender.” A fully optimized GBP captures that traffic at zero cost per click.

    NAP consistency is the practice of keeping your business name, address, and phone number identical across every directory — Google, Zillow, Realtor.com, your brokerage site, and Facebook. Even minor variations (“St.” vs. “Street”) signal to Google that these are competing entities, diluting your local ranking authority.

    GBP vs. Yelp vs. Facebook vs. Zillow: Which Platform Deserves Your Time?

    Most Clarksville TN realtors have profiles scattered across multiple platforms but maintain none of them well. The table below gives you an honest comparison so you can prioritize intelligently.

    Platform Cost Local SEO Impact Review Velocity Post Features Mobile Traffic Share
    Google Business Profile Free Highest — direct local pack placement; primary ranking signal Fast — clients already have Google accounts; one-tap review links Yes — offers, updates, events, photos; active posts boost ranking ~45% of local searches start directly on Google (BrightLocal, 2025)
    Yelp Free (ads upsell) Moderate — good for citations; limited direct map pack pull for real estate Slower — Yelp filters aggressively; many legitimate reviews get hidden Limited — no true post feature; updates via photos only 44% of consumers check Yelp (BrightLocal, 2025)
    Facebook Business Page Free (ads cost) Low–Moderate — social signals indirectly support SEO; no map pack Moderate — easy for clients, but reviews are called “Recommendations” Yes — full content posting; strong for video and community content ~40% use Facebook for business reviews (BrightLocal, 2025)
    Zillow Profile Free (Premier Agent costs) Low for SEO; high visibility within Zillow’s own search ecosystem Moderate — reviews tied to transaction history; quality is high No posts — static profile with listings and bio only Strong within app; limited cross-platform SEO transfer

    Bottom line: GBP wins on every dimension that drives inbound leads from Google Search and Maps. Zillow and Facebook play supporting roles. Yelp is worth maintaining for NAP consistency but should not be your primary review-collection focus.

    How to Optimize Your Google Business Profile in 8 Steps

    GBP categories are the classification tags you select to tell Google what type of business you operate. Your primary category — the single most important field in your entire profile — should be “Real Estate Agent” if you are a licensed agent or “Mortgage Broker” / “Mortgage Lender” if you are a licensed MLO. Secondary categories such as “Real Estate Consultant” or “Real Estate Rental Agency” allow Google to match your profile to additional query types without diluting your primary focus.

    1. Claim and verify your profile. Go to business.google.com, search for your name, and claim or create your listing. Google verifies via postcard, video call, or phone. Until verified, your profile is invisible in the local pack.
    2. Set the right primary category. Clarksville TN realtors should use “Real Estate Agent.” Fort Campbell VA loan specialists and MLOs should use “Mortgage Lender” or “Mortgage Broker.” Add secondary categories sparingly — “Real Estate Consultant” works well. Never stack irrelevant categories.
    3. Complete every field. Fill in name, address or service area, phone, website, hours, and the full 750-character description. Weave in your markets — Clarksville, Fort Campbell, Montgomery County, Nashville, Middle Tennessee — and your specializations (VA loans, first-time homebuyers, PCS military buyers).
    4. Build out your Services section. Add entries for Buyer Representation, Seller Representation, VA Loan Pre-Approval, First-Time Homebuyer Guidance, Military Relocation, and Listing Services. Use keyword-rich descriptions that reference the Clarksville housing market and homes for sale near Fort Campbell.
    5. Upload photos consistently. Google data shows profiles with photos receive 35% more website clicks. Upload headshots, office exteriors, neighborhood shots of the Clarksville and Fort Campbell area, sold signs, and open-house images. Name files descriptively (“clarksville-tn-real-estate-agent-kate.jpg”). Add new photos monthly.
    6. Publish GBP Posts weekly. GBP posts are short-form updates that appear on your listing and expire after seven days. Post market updates, just-listed/just-sold announcements, and Nashville real estate market commentary. Include a photo and a call-to-action button in every post.
    7. Seed and manage Q&A. Proactively add Q&A pairs covering your specializations: “Do you work with Fort Campbell VA buyers?” — “Yes, Kate Matties-Deiboldt at VanDyk Mortgage is a licensed Fort Campbell VA loan specialist serving Montgomery County and Middle Tennessee.” Answer new questions within 24 hours; unanswered questions can be claimed by anyone.
    8. Generate and respond to reviews. Ask every client for a Google review within 48 hours of closing using a direct review link from your GBP dashboard. Respond to every review within 48 hours. BrightLocal (2026) found 89% of consumers expect responses, and 80% are more likely to choose a business that responds to all reviews. In your reply, include location context: “Thank you for trusting us with your Fort Campbell home purchase.”

    FAQ — Google Business Profile for Real Estate Agents and Mortgage Lenders

    Can a realtor use a residential address on their Google Business Profile?

    Yes, with a caveat. Google allows service-area businesses — including solo agents working from home — to hide their address and list service areas instead. Set your service areas explicitly: Clarksville, Fort Campbell, Montgomery County TN, Nashville, Middle Tennessee. If you meet clients at a brokerage office, use that address. Either way, the address you list must match your Realtor.com and Zillow profiles exactly to maintain NAP consistency.

    How many Google reviews does a Clarksville TN realtor need to rank in the local pack?

    There is no magic number, but industry benchmarks from local SEO practitioners suggest that 25–30 reviews makes you competitive in most mid-size markets, and 50+ reviews with a consistent pace of 2–4 new reviews per month positions you to dominate the local pack in the Clarksville housing market. Review velocity matters more than total count — BrightLocal (2026) data shows 74% of consumers only care about reviews from the last three months. A profile with 20 fresh reviews typically outranks one with 100 reviews that stopped accumulating two years ago.

    Does Google Business Profile work for a licensed MLO or mortgage lender?

    Yes. A licensed Clarksville TN mortgage lender or Fort Campbell VA loan specialist can create a GBP under “Mortgage Lender” or “Mortgage Broker.” If your brokerage already has a master listing, Google supports individual practitioner profiles — your profile collects its own reviews separate from the brokerage. This is especially useful in Clarksville TN, where searches for “Fort Campbell VA loan specialist” and “Clarksville TN mortgage lender” come frequently from PCS-bound military families.

    What GBP categories should a Clarksville real estate agent select?

    Primary category: “Real Estate Agent.” Good secondary choices: “Real Estate Consultant” and “Real Estate Agency” if you represent a team. For a licensed MLO, use “Mortgage Lender” as the primary with “Mortgage Broker” as a secondary if applicable. Avoid generic financial categories — Google audits category accuracy and can suspend profiles for misuse. Specificity drives better matches with high-intent local searches in the Clarksville housing market.

    How often should a Clarksville TN realtor post on their GBP?

    Post at minimum once per week — GBP posts expire after seven days, so weekly posting ensures your listing always shows active content. Agents posting two to three times weekly over several months see a 25–40% increase in profile views. Content ideas for the Clarksville and Nashville real estate markets: just-listed and just-sold announcements, Montgomery County market updates, VA loan eligibility tips for Fort Campbell buyers, and first-time homebuyer Clarksville guides. Keep each post under 750 characters, add one image, and include a call-to-action button.

    How should a Clarksville TN realtor respond to a bad Google review?

    Respond within 24–48 hours. Never argue publicly. Use a three-part structure: acknowledge the experience, offer to resolve it offline with your contact info, and briefly note your standard of service. Example: “Our goal is to make every client’s home-buying experience in the Clarksville area as smooth as possible. Please reach out directly — I would like to understand what happened and make it right.” BrightLocal (2026) found that 56% of consumers changed their opinion of a business after reading a thoughtful owner response — your reply is marketing copy for every future prospect who reads that review.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

  • The 5 Mortgage Credit Score Killers (and How to Recover Fast)

    The 5 Mortgage Credit Score Killers (and How to Recover Fast)

    The biggest mortgage credit score killers are high credit card utilization, late payments, applying for new credit right before you apply for a mortgage, unresolved collections/derogatory items, and errors on your credit report. The good news is most of these can be fixed quickly with the right order of operations. If you’re buying in Clarksville, Fort Campbell, or anywhere in Middle Tennessee, a few small moves in the next 30–60 days can change your loan options and rate.

    To understand why these issues matter so much, it helps to know how scores are built: payment history is 35% of a FICO® Score, and “amounts owed” (which includes utilization) is 30% ([myFICO (2016)](https://www.myfico.com/credit-education/whats-in-your-credit-score)).

    Key Takeaways

    • Utilization is the fast lever. Paying revolving balances down (often below 30%—sometimes below 10%) can improve mortgage scores quickly.
    • New credit is a timing problem. A hard inquiry and a new account can temporarily drop scores, so pause applications before mortgage pre-approval Clarksville.
    • Late payments are the slowest to heal. A single 30-day late can hurt, so protect autopay and due dates while you shop homes for sale near Fort Campbell.
    • Collections aren’t all equal. The right strategy depends on loan type (FHA/VA/conventional) and what your lender’s underwriting rules require.
    • Errors happen. Checking for mixed files, wrong balances, or outdated statuses can prevent delays when you’re buying a home in Nashville or Clarksville.

    First, what does “mortgage credit score” really mean?

    A mortgage credit score is a credit score version used specifically in mortgage underwriting, and it can differ from the score you see in many free apps.

    Credit utilization is the percentage of your available revolving credit you’re using across credit cards and lines of credit, and it’s a major piece of the “amounts owed” category ([myFICO (2019)](https://www.myfico.com/credit-education/credit-scores/amount-of-debt)).

    A hard inquiry is a lender’s request to review your credit after you apply for new credit, and it can temporarily impact your score because it signals you may be taking on new debt ([myFICO (2016)](https://www.myfico.com/credit-education/whats-in-your-credit-score)).

    The 5 mortgage credit score killers (and how to recover fast)

    1) High credit card utilization

    High utilization is the fastest score killer I see for buyers getting ready in Clarksville and around Fort Campbell. myFICO notes that using a high percentage of your available credit can hurt FICO Scores, and “amounts owed” is 30% of the score ([myFICO (2019)](https://www.myfico.com/credit-education/credit-scores/amount-of-debt)).

    2) Late payments

    Late payments hurt because payment history is the biggest slice of a FICO score (35%) ([myFICO (2016)](https://www.myfico.com/credit-education/whats-in-your-credit-score)). Protecting on-time payments matters whether you’re shopping the Clarksville housing market or planning a Nashville commute.

    3) Applying for new credit right before mortgage pre-approval

    “New credit” is about 10% of a FICO score, and opening several accounts in a short period can increase risk ([myFICO (2016)](https://www.myfico.com/credit-education/whats-in-your-credit-score)). A common mistake is financing furniture or a car while you’re under contract in Montgomery County.

    4) Collections handled in the wrong order

    Collections aren’t all equal. The best plan depends on program rules (VA loans Clarksville TN, FHA, conventional, USDA loans Tennessee) and what underwriting will require, so don’t guess on the “right” payoff order.

    5) Credit report errors

    Errors can show up as accounts that aren’t yours, wrong balances, wrong statuses, or “mixed file” issues. The CFPB lists common credit report errors to watch for, including identity errors and incorrect balances or credit limits ([Consumer Financial Protection Bureau (2024)](https://www.consumerfinance.gov/ask-cfpb/what-are-common-credit-report-errors-that-i-should-look-for-on-my-credit-report-en-313/)).

    Comparison table: quick fixes vs slow fixes

    Issue How fast you can usually improve it Best first move
    High credit utilization Fast (often 30–45 days) Pay balances down before statement close
    New credit inquiries / new accounts Medium (weeks to months) Pause new credit; keep everything else stable
    Late payments Slow (months to years) Autopay minimums + perfect on-time streak
    Collections/derogatories Varies Get a lender-guided plan before paying
    Credit report errors Medium (days to months) Pull all 3 reports and dispute with proof

    Where internal links fit (so you have a full plan)

    • [INTERNAL LINK: What Credit Score Do You Really Need to Buy a Home in Clarksville TN?]
    • [INTERNAL LINK: Why Your Mortgage Credit Score Is Different From Your Credit Karma Score]
    • [INTERNAL LINK: Should I Pay Off Collections Before Applying for a Mortgage?]

    Frequently Asked Questions

    What is the fastest way to raise my score before I apply for a mortgage?

    The fastest win is usually lowering credit card utilization before your statement closes, because “amounts owed” is a major part of FICO scoring. Stop applying for new credit, pay revolving balances down, and keep every account current. In Clarksville and Fort Campbell markets, even small score shifts can change the pricing you see on conventional options.

    Should I pay off my credit cards completely or just pay them down?

    Paying them down is often enough if it meaningfully lowers utilization, and you don’t have to hit zero for an improvement. Focus on getting each card out of the “near maxed-out” zone first, then reduce overall utilization. Keep accounts open so your available credit doesn’t shrink and accidentally raise your utilization percentage.

    Is it okay to open a new credit card to increase my available credit?

    Usually not right before mortgage pre-approval Clarksville, because the application triggers a hard inquiry and creates a brand-new account that can temporarily lower your score. If increasing limits is part of a long-term plan, it’s better done months before you start home shopping in Montgomery County or the Nashville area, not during the process.

    Will checking my credit hurt my score?

    Checking your own credit through a personal monitoring service is typically a soft inquiry and doesn’t lower your score. The concern is hard inquiries tied to applying for new credit. If you’re preparing for VA loans Clarksville TN or a conventional loan, regular monitoring can help you catch utilization spikes or report errors early.

    How many points does a hard inquiry lower a score?

    There isn’t one universal number because it depends on your full credit profile, but a hard inquiry can cause a small temporary dip—especially if you have a shorter history or multiple recent inquiries. What matters most is avoiding multiple non-mortgage inquiries while you’re shopping for homes for sale near Fort Campbell or commuting to Nashville.

    Do medical collections affect mortgage approval in Tennessee?

    They can, but the impact depends on loan type and the lender’s underwriting rules. Some programs focus more on overall repayment history and your current payment obligations than the existence of an older medical collection. Before paying anything, talk with your lender so we align the plan with your timeline and the program you’re using.

    Should I dispute a negative item right before closing?

    Sometimes disputes can create extra documentation requirements or delays, so the timing matters. If you’re early in the process, disputing an obvious error can be smart. If you’re already under contract in Clarksville or Middle Tennessee, your lender may advise a specific approach that avoids last-minute surprises in underwriting.

    What credit utilization percentage is “too high” for mortgage scores?

    High utilization is generally viewed as risky, and many borrowers see improvement when they move below common thresholds like 30% overall and per card (and sometimes lower). The exact response varies by profile, but utilization is a lever you can control quickly. It’s one of the first things I look at for first-time homebuyer Clarksville plans.

    Can paying off a collection lower my credit score?

    It’s possible for a score to change in unexpected ways because scoring is complex and depends on what else is on your report. Paying a collection may not boost your score immediately, and it can update the “last activity” date on some reports. That’s why the right move is to build a lender-guided strategy tied to your mortgage program.

    How far in advance should I stop using credit before buying a home?

    Ideally, pause new credit applications 60–90 days before you apply, and start lowering utilization one to two statement cycles ahead. If you’re PCS to Fort Campbell or targeting the Clarksville real estate market on a tighter timeline, we can still prioritize fast actions, but earlier planning gives you more options and less stress.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “@id”: “https://thedealdoctor.blog/?p=HOME_BUYER_POST_02#article&#8221;,
    “headline”: “The 5 Mortgage Credit Score Killers (and How to Recover Fast)”,
    “description”: “Learn the five biggest mortgage credit score killers and the fastest ways to recover so you can get pre-approved with confidence in Clarksville and Middle Tennessee.”,
    “datePublished”: “2026-05-26”,
    “dateModified”: “2026-05-26”,
    “author”: {
    “@type”: “Person”,
    “name”: “Kate Matties-Deiboldt”,
    “honorificSuffix”: “NMLS #18487”,
    “worksFor”: {
    “@type”: “Organization”,
    “name”: “VanDyk Mortgage”
    }
    },
    “publisher”: {
    “@type”: “Organization”,
    “name”: “The Blue Note Home”
    },
    “mainEntityOfPage”: “https://thedealdoctor.blog/?p=HOME_BUYER_POST_02&#8221;,
    “keywords”: [
    “mortgage credit score killers”,
    “credit utilization”,
    “mortgage pre-approval Clarksville”,
    “VA loans Clarksville TN”,
    “Fort Campbell home buying”,
    “Middle Tennessee mortgage”
    ]
    },
    {
    “@type”: “BreadcrumbList”,
    “@id”: “https://thedealdoctor.blog/for-homebuyers/the-5-mortgage-credit-score-killers#breadcrumbs&#8221;,
    “itemListElement”: [
    {
    “@type”: “ListItem”,
    “position”: 1,
    “name”: “Home”,
    “item”: “https://thedealdoctor.blog/&#8221;
    },
    {
    “@type”: “ListItem”,
    “position”: 2,
    “name”: “For Homebuyers”,
    “item”: “https://thedealdoctor.blog/for-homebuyers/&#8221;
    },
    {
    “@type”: “ListItem”,
    “position”: 3,
    “name”: “The 5 Mortgage Credit Score Killers (and How to Recover Fast)”,
    “item”: “https://thedealdoctor.blog/for-homebuyers/the-5-mortgage-credit-score-killers&#8221;
    }
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “@id”: “https://thedealdoctor.blog/#localbusiness&#8221;,
    “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,
    “telephone”: “+1-931-980-9764”,
    “email”: “Kate@JustCallKate.com”,
    “address”: {
    “@type”: “PostalAddress”,
    “addressLocality”: “Clarksville”,
    “addressRegion”: “TN”,
    “addressCountry”: “US”
    },
    “areaServed”: [
    “Clarksville TN”,
    “Fort Campbell”,
    “Montgomery County TN”,
    “Nashville TN”,
    “Middle Tennessee”
    ],
    “additionalProperty”: [
    {
    “@type”: “PropertyValue”,
    “name”: “NMLS”,
    “value”: “18487”
    }
    ]
    },
    {
    “@type”: “FAQPage”,
    “@id”: “https://thedealdoctor.blog/?p=HOME_BUYER_POST_02#faq&#8221;,
    “mainEntity”: [
    {
    “@type”: “Question”,
    “name”: “What is the fastest way to raise my score before I apply for a mortgage?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “The fastest win is usually lowering credit card utilization before your statement closes, because \u201camounts owed\u201d is a major part of FICO scoring. Stop applying for new credit, pay revolving balances down, and keep every account current. In Clarksville and Fort Campbell markets, even small score shifts can change the pricing you see on conventional options.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “Should I pay off my credit cards completely or just pay them down?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “Paying them down is often enough if it meaningfully lowers utilization, and you don\u2019t have to hit zero for an improvement. Focus on getting each card out of the \u201cnear maxed-out\u201d zone first, then reduce overall utilization. Keep accounts open so your available credit doesn\u2019t shrink and accidentally raise your utilization percentage.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “Is it okay to open a new credit card to increase my available credit?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “Usually not right before mortgage pre-approval Clarksville, because the application triggers a hard inquiry and creates a brand-new account that can temporarily lower your score. If increasing limits is part of a long-term plan, it\u2019s better done months before you start home shopping in Montgomery County or the Nashville area, not during the process.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “Will checking my credit hurt my score?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “Checking your own credit through a personal monitoring service is typically a soft inquiry and doesn\u2019t lower your score. The concern is hard inquiries tied to applying for new credit. If you\u2019re preparing for VA loans Clarksville TN or a conventional loan, regular monitoring can help you catch utilization spikes or report errors early.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “How many points does a hard inquiry lower a score?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “There isn\u2019t one universal number because it depends on your full credit profile, but a hard inquiry can cause a small temporary dip\u2014especially if you have a shorter history or multiple recent inquiries. What matters most is avoiding multiple non-mortgage inquiries while you\u2019re shopping for homes for sale near Fort Campbell or commuting to Nashville.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “Do medical collections affect mortgage approval in Tennessee?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “They can, but the impact depends on loan type and the lender\u2019s underwriting rules. Some programs focus more on overall repayment history and your current payment obligations than the existence of an older medical collection. Before paying anything, talk with your lender so we align the plan with your timeline and the program you\u2019re using.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “Should I dispute a negative item right before closing?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “Sometimes disputes can create extra documentation requirements or delays, so the timing matters. If you\u2019re early in the process, disputing an obvious error can be smart. If you\u2019re already under contract in Clarksville or Middle Tennessee, your lender may advise a specific approach that avoids last-minute surprises in underwriting.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “What credit utilization percentage is \u201ctoo high\u201d for mortgage scores?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “High utilization is generally viewed as risky, and many borrowers see improvement when they move below common thresholds like 30% overall and per card (and sometimes lower). The exact response varies by profile, but utilization is a lever you can control quickly. It\u2019s one of the first things I look at for first-time homebuyer Clarksville plans.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “Can paying off a collection lower my credit score?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “It\u2019s possible for a score to change in unexpected ways because scoring is complex and depends on what else is on your report. Paying a collection may not boost your score immediately, and it can update the \u201clast activity\u201d date on some reports. That\u2019s why the right move is to build a lender-guided strategy tied to your mortgage program.”
    }
    },
    {
    “@type”: “Question”,
    “name”: “How far in advance should I stop using credit before buying a home?”,
    “acceptedAnswer”: {
    “@type”: “Answer”,
    “text”: “Ideally, pause new credit applications 60\u201390 days before you apply, and start lowering utilization one to two statement cycles ahead. If you\u2019re PCS to Fort Campbell or targeting the Clarksville real estate market on a tighter timeline, we can still prioritize fast actions, but earlier planning gives you more options and less stress.”
    }
    }
    ]
    },
    {
    “@type”: “SpeakableSpecification”,
    “@id”: “https://thedealdoctor.blog/?p=HOME_BUYER_POST_02#speakable&#8221;,
    “cssSelector”: [
    “.key-takeaways”,
    “h1”,
    “p:first-of-type”
    ]
    },
    {
    “@type”: “ItemList”,
    “@id”: “https://thedealdoctor.blog/?p=HOME_BUYER_POST_02#itemlist&#8221;,
    “name”: “The 5 Mortgage Credit Score Killers”,
    “itemListElement”: [
    { “@type”: “ListItem”, “position”: 1, “name”: “High credit card utilization” },
    { “@type”: “ListItem”, “position”: 2, “name”: “Late payments” },
    { “@type”: “ListItem”, “position”: 3, “name”: “Applying for new credit before mortgage pre-approval” },
    { “@type”: “ListItem”, “position”: 4, “name”: “Collections handled in the wrong order” },
    { “@type”: “ListItem”, “position”: 5, “name”: “Credit report errors” }
    ]
    }
    ]
    }

  • Memorial Day

    This Memorial Day feels especially personal for me.

    My father now rests in Arlington National Cemetery among generations of Americans who served this country with honor. He wasn’t killed in combat, but he answered the call to serve, wore the uniform with pride, and carried that sense of duty throughout his life.

    Memorial Day is often associated with those lost in battle, but it’s also a reminder that freedom has always depended on ordinary men and women willing to sacrifice years of their lives in service to something bigger than themselves.

    Today I’m remembering my dad — Major John Byron Reeves — with gratitude, pride, and love.

    Memorial Day
  • What Credit Score Do You Really Need to Buy a Home in Clarksville TN?

    What Credit Score Do You Really Need to Buy a Home in Clarksville TN?

    Most homebuyers can qualify in Clarksville with a credit score in the low-to-mid 600s, and some programs work below that. What you really need depends on loan type, down payment, and the rest of your file. Near Fort Campbell or commuting to Nashville, credit is solvable when you know the rules.

    The average FICO® Score hit 717 in April 2024 per FICO (2024) — but you don’t need 717 to buy in Montgomery County TN.

    Key Takeaways

    • Conventional loans often start around 620+. Many lenders use this as a practical minimum for conforming financing.
    • FHA can be more flexible. FHA guidance commonly references 580 for 3.5% down (and 500–579 with 10% down), but lender overlays vary.
    • VA sets no minimum score. The VA itself has no requirement, but many lenders look for ~580-620 in practice.
    • Your mortgage score may differ from your app score. Mortgage scoring models often produce a different number than Credit Karma or your bank app.
    • Strategy beats perfection. Small fixes (utilization, disputes, timing) can move your score faster than you think.

    So what’s the real minimum credit score?

    A minimum credit score is the lowest score a loan program (or lender) will accept for approval. A credit score is a three-digit measure of how likely you are to repay debt on time. A lender overlay is a stricter rule a lender adds on top of a program’s baseline guidelines. That’s why two buyers with the same score can get different answers from different lenders — credit is usually the first gate, but income, DTI, and cash to close all matter too.

    Credit score requirements by loan type

    If you’re watching the Clarksville housing market or looking at homes near Fort Campbell, these are the score zones most buyers see.

    Loan type Typical starting point What to know
    Conventional Often 620+ Pricing improves as scores rise. Automated approvals may skip a hard floor; lender overlays still apply.
    FHA Often 580+ (sometimes lower) Built for flexibility — 580+ for 3.5% down is common; lower may work with more down and strong compensating factors.
    VA No VA minimum; lenders often ~620 The VA sets no minimum, but lenders do. The VA Buyer’s Guide notes many want ~620.
    USDA Varies by lender USDA loans Tennessee fit eligible rural/suburban areas around Middle Tennessee. Underwriting focuses on repayment ability and property eligibility.

    For specifics: Fannie Mae’s Selling Guide lists 620 for manually underwritten fixed-rate loans and waives a minimum for DU casefiles (Fannie Mae (2024)). The VA Buyer’s Guide (2026) confirms the no-minimum VA rule.

    Why your whole file changes the score you need

    In mortgage pre-approval Clarksville conversations, a 640 with great cash reserves can be easier than a 680 with high card balances. Big swing factors: down payment, DTI, credit history depth, recent late payments, and occupancy type.

    How to raise your mortgage-ready credit score in 5 steps

    1. Pull your reports and find the real problems. Verify late payments, collections, and utilization before spending a dime fixing anything.
    2. Target utilization first. Lowering card balances (especially below ~30% per card) usually moves your score faster than opening new accounts.
    3. Avoid opening new debt before pre-approval. New inquiries and accounts can temporarily lower scores and shift your DTI.
    4. Be careful with disputes. Some loan types require disputes to be removed before closing, and they can pause underwriting.
    5. Get a written plan and timeline. A plan beats guesswork — especially on a PCS to Fort Campbell timeline.

    Clarksville + Fort Campbell: military and relocation buyers

    If you’re doing military relocation Clarksville planning, your timeline may be tight — and your goals may include a VA loan (no monthly PMI) or a payment that works for a Nashville commute. A Fort Campbell VA loan specialist should show you side-by-side options. (See also: [INTERNAL LINK: FHA vs Conventional cost comparison] and [INTERNAL LINK: mortgage credit score vs Credit Karma score].)

    What score should you aim for?

    The minimum is the doorway. Your target is the score that gets you a manageable payment — and a few points can matter over 30 years of Nashville mortgage rates.

    • Under ~580: Focus on rapid stabilization and pick a program that matches your timeline.
    • 580–619: FHA or some VA scenarios may work; plan carefully for lender overlays.
    • 620–679: Multiple paths usually open — we compare payment + cash to close.
    • 680+: You’re typically in a strong pricing tier, assuming DTI and assets line up.

    Next steps: a real pre-approval plan

    Tell me your score range, approximate income, and target area (Clarksville, Fort Campbell, or closer to Nashville), and I’ll tell you what lane you’re in and what to fix first. See also: [INTERNAL LINK: how much cash you need to buy in Clarksville].

    Frequently Asked Questions

    What credit score do I need to buy a home in Clarksville, TN?

    Most buyers start the conversation around the low-to-mid 600s, but the exact number depends on loan type and the rest of your file. In Clarksville and Montgomery County, conventional approvals often start at 620+, while FHA and VA can be more flexible. The best first step is a true pre-approval.

    Can I buy a house with a 580 credit score?

    Sometimes, yes. 580 is commonly referenced for FHA with a low down payment, though lenders may add overlays. The VA sets no minimum, but lenders often do. At 580, review your credit report, confirm DTI, and pick a program that matches your timeline.

    Does the VA require a minimum credit score for a VA loan?

    No. The VA does not set a minimum, but most lenders still use credit scores to set pricing and often prefer ~620. That’s why working with a Fort Campbell VA loan specialist matters — you’ll get realistic lender expectations alongside residual income, DTI, and payment history review.

    Is 620 a good credit score to buy a house?

    620 is often a practical baseline for conventional financing and opens more options than the 500s. “Good” depends on your goals — payment, cash to close, and long-term plan matter more than bragging rights. In Middle Tennessee, a 620 borrower may still choose FHA or VA for a better payment.

    Why is my mortgage credit score different from what I see online?

    Mortgage underwriting uses different scoring models than most consumer apps, so a gap is normal. Timing matters too: balances reported this month might not match what you just paid. During mortgage pre-approval Clarksville planning, we pull the right reports and plan around the score lenders actually use.

    Should I pay off collections before applying for a mortgage?

    It depends on the collection type, loan program, and whether paying it off could temporarily shift your score. Some collections impact approval more than others, and payoffs need to be documented carefully. Before spending money, get a written plan aligned to your Clarksville timeline.

    Will paying down credit cards help my score quickly?

    Often yes — especially if balances are high compared to limits. Utilization is one of the fastest-moving parts of a credit score, and lowering it usually produces a noticeable bump when the new balance reports. For Clarksville and Fort Campbell buyers, this is the first lever I pull because it’s predictable.

    How many points can my score change before closing?

    Your score can move meaningfully in a few weeks if something changes — a new late payment, new account, or large balance increase. It can also improve if you pay down cards. I recommend stability once you start shopping in Clarksville or Nashville. We want your credit profile boring between contract and closing.

    Can I get a mortgage with no credit score (thin credit)?

    Yes, in some cases. A “thin file” means too little traditional credit history to generate a score — different from bad credit. Some programs allow nontraditional documentation (rent, utilities) or manual underwriting. Relocating to Fort Campbell with little credit history? We’ll map options and build credit the right way.

    What’s the best first step if I’m not sure I qualify yet?

    Start with a low-pressure pre-approval review and an action plan. We’ll review your score range, DTI, income, and cash to close, then pick the best lane — FHA, VA, USDA, or conventional. You’ll know what to fix, what to avoid, and how long until you’re ready to buy in Clarksville.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Middle Tennessee.

    Your Clear Guide Through the Mortgage Process

    Whatever your questions, concerns, or hesitations — I can be your clear guide through the mortgage process. The first step is a quick, no-obligation analysis of your current situation and a professional plan of action so you’re in the best possible position when you’re ready to buy or refinance.

    Call or text Kate: (931) 980-9764
    Email: Kate@JustCallKate.com

    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “@id”: “https://thedealdoctor.blog/for-homebuyers/credit-score-buy-home-clarksville-tn&#8221;,
    “headline”: “What Credit Score Do You Really Need to Buy a Home in Clarksville TN?”,
    “description”: “Most homebuyers can qualify to buy a home in Clarksville with a credit score in the low-to-mid 600s. Program-by-program targets plus a step-by-step plan.”,
    “datePublished”: “2026-05-25”,
    “dateModified”: “2026-05-25”,
    “mainEntityOfPage”: “https://thedealdoctor.blog/for-homebuyers/credit-score-buy-home-clarksville-tn&#8221;,
    “author”: {
    “@type”: “Person”,
    “name”: “Kate Matties-Deiboldt”,
    “identifier”: “NMLS #18487”,
    “worksFor”: {“@type”: “Organization”, “name”: “VanDyk Mortgage”}
    },
    “publisher”: {“@type”: “Organization”, “name”: “The Blue Note Home”},
    “keywords”: [“credit score to buy a home in Clarksville TN”,”Clarksville TN mortgage lender”,”VA loans Clarksville TN”,”Fort Campbell home buying”,”mortgage pre-approval Clarksville”,”Middle Tennessee mortgage”]
    },
    {
    “@type”: “BreadcrumbList”,
    “itemListElement”: [
    {“@type”: “ListItem”,”position”: 1,”name”: “Home”,”item”: “https://thedealdoctor.blog/&#8221;},
    {“@type”: “ListItem”,”position”: 2,”name”: “For Homebuyers”,”item”: “https://thedealdoctor.blog/for-homebuyers/&#8221;},
    {“@type”: “ListItem”,”position”: 3,”name”: “What Credit Score Do You Really Need to Buy a Home in Clarksville TN?”,”item”: “https://thedealdoctor.blog/for-homebuyers/credit-score-buy-home-clarksville-tn&#8221;}
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,
    “address”: {“@type”: “PostalAddress”,”addressLocality”: “Clarksville”,”addressRegion”: “TN”,”addressCountry”: “US”},
    “telephone”: “+1-931-980-9764”,
    “email”: “Kate@JustCallKate.com”,
    “areaServed”: [“Clarksville TN”,”Fort Campbell”,”Montgomery County TN”,”Nashville TN”,”Middle Tennessee”],
    “additionalProperty”: [{“@type”: “PropertyValue”,”name”: “NMLS”,”value”: “18487”}]
    },
    {
    “@type”: “SpeakableSpecification”,
    “cssSelector”: [“.key-takeaways”,”h1″,”p:first-of-type”]
    },
    {
    “@type”: “HowTo”,
    “name”: “How to raise your mortgage-ready credit score in 5 steps”,
    “description”: “A simple, lender-friendly plan to improve credit before you buy a home in Clarksville or near Fort Campbell.”,
    “totalTime”: “P30D”,
    “step”: [
    {“@type”:”HowToStep”,”name”:”Pull your reports and identify the real problems”,”text”:”Verify late payments, collections, and utilization before spending money.”},
    {“@type”:”HowToStep”,”name”:”Target utilization first”,”text”:”Pay down revolving balances to reduce utilization and stabilize your score.”},
    {“@type”:”HowToStep”,”name”:”Avoid opening new debt right before pre-approval”,”text”:”New inquiries and accounts can temporarily lower scores and change DTI.”},
    {“@type”:”HowToStep”,”name”:”Be careful with disputes”,”text”:”Disputes can delay underwriting and may need to be removed before closing.”},
    {“@type”:”HowToStep”,”name”:”Get a written plan and timeline”,”text”:”Align credit milestones with your pre-approval and closing targets.”}
    ]
    },
    {
    “@type”: “FAQPage”,
    “mainEntity”: [
    {“@type”: “Question”,”name”: “What credit score do I need to buy a home in Clarksville, TN?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Most buyers can start the conversation around the low-to-mid 600s, but the exact number depends on the loan type and your overall file. In Clarksville and Montgomery County, I often see conventional approvals start around 620+, while FHA and VA may offer flexibility when the rest of the application is strong. The best first step is a true pre-approval, not a website guess.”}},
    {“@type”: “Question”,”name”: “Can I buy a house with a 580 credit score?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Sometimes, yes. A 580 score is commonly referenced for FHA eligibility with a low down payment, but individual lenders may require higher scores through overlays. With VA loans, the VA doesn’t set a minimum, but lenders often do. If you’re at 580, the strategy is to review your credit report, confirm your DTI, and pick a program that matches your timeline.”}},
    {“@type”: “Question”,”name”: “Does the VA require a minimum credit score for a VA loan?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “No. The VA states it does not require a minimum credit score, but most lenders still use credit scores to set risk and pricing and may prefer a score around 620. That’s why working with a Fort Campbell VA loan specialist matters: you’ll get realistic lender expectations, not just generic advice. We also look at residual income, DTI, and payment history.”}},
    {“@type”: “Question”,”name”: “Is 620 a good credit score to buy a house?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “A 620 score is often a practical baseline for conventional financing, and it can open more options than the 500s. That said, good depends on your goals — your payment, cash to close, and long-term plan matter more than bragging rights. In Middle Tennessee, a 620 borrower may still choose FHA or VA if it produces a better payment and easier approval path.”}},
    {“@type”: “Question”,”name”: “Why is my mortgage credit score different from what I see online?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Mortgage underwriting can use different scoring models than the score shown in many consumer apps, so it’s common to see a gap. Timing matters too: balances reported this month might not match what you just paid. A credit score is a snapshot, not a verdict. During mortgage pre-approval Clarksville planning, we pull the right reports and build a plan around the score lenders actually use.”}},
    {“@type”: “Question”,”name”: “Should I pay off collections before applying for a mortgage?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “It depends on the type of collection, the loan program, and whether paying it off could temporarily shift your score. Some collections impact approval more than others, and sometimes a payoff needs to be documented carefully. Before you spend money, get a written plan that considers FHA, VA, and conventional guidelines and your Clarksville real estate market timeline.”}},
    {“@type”: “Question”,”name”: “Will paying down credit cards help my score quickly?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Often, yes — especially if your card balances are high compared to your limits. Utilization is one of the fastest-moving parts of a credit score, and lowering it can produce a noticeable improvement when the new balance reports. If you’re preparing to buy homes for sale near Fort Campbell or in Clarksville, this is usually the first lever I pull because it’s predictable and measurable.”}},
    {“@type”: “Question”,”name”: “How many points can my score change before closing?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Your score can move meaningfully in a few weeks if something changes — like a new late payment, a new account, or a large balance increase. It can also improve if you pay down cards and keep everything current. That’s why I recommend stability after you start shopping seriously in Clarksville or Nashville. We want your credit profile boring between contract and closing.”}},
    {“@type”: “Question”,”name”: “Can I get a mortgage with no credit score (thin credit)?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Yes, in some cases. A thin file means you don’t have enough traditional credit history to generate a score, which is different from having bad credit. Some programs allow nontraditional credit documentation (like rent and utility payments) or manual underwriting. If you’re relocating to Fort Campbell and don’t have much credit history, we’ll map options and build credit the right way.”}},
    {“@type”: “Question”,”name”: “What’s the best first step if I’m not sure I qualify yet?”,”acceptedAnswer”: {“@type”: “Answer”,”text”: “Start with a low-pressure pre-approval review and a specific action plan. We’ll look at your score range, DTI, income stability, and cash to close, then choose the best lane — FHA, VA loan eligibility Tennessee, USDA loans Tennessee, or conventional. You’ll walk away knowing what to fix, what to avoid, and how long it should take to be ready to buy in Clarksville or Montgomery County.”}}
    ]
    }
    ]
    }

  • Content Repurposing Real Estate Closing: 10 Pieces, One Deal

    Content Repurposing Real Estate Closing: 10 Pieces, One Deal

    Content repurposing is the practice of transforming one original asset — such as a real estate closing moment — into multiple formats distributed across different platforms. For Clarksville TN realtors and Fort Campbell home buying specialists, a single closing already contains everything you need: a story, a result, a happy client, and proof of expertise. The question is whether you capture it once and move on, or extract every drop of marketing value before you leave the driveway.

    Per HubSpot’s 2026 State of Marketing report, content repurposing is the fifth most popular digital marketing trend, with 49.4% of teams reusing content across platforms and 39.5% tailoring it per platform. The NAR 2025 REALTORS Technology Survey found social media is the top lead-generating technology for 39% of agents — yet most Clarksville real estate agents treat their closings as a one-post event instead of the content goldmine they actually are.

    Key Takeaways

    • One closing = 10 distinct pieces of content across video, graphics, email, blog, and local search platforms.
    • Content atomization means breaking one pillar asset (your closing video) into micro-content tailored to each platform’s format and audience.
    • Military PCS clients from Fort Campbell require a permission conversation before any closing content is published — OPSEC is real and your process should reflect it.
    • The HowTo framework below gives you 7 repeatable steps to extract all 10 pieces systematically from every deal — including old closings you’ve already done.
    • Clarksville real estate agent content that ties a closing story to the Nashville real estate market or Fort Campbell community outperforms generic “Just Sold” graphics by a wide margin.
    • You don’t need new closings to start — old transactions with client permission are fair game and can be refreshed for current relevance.

    What Is Content Repurposing — and Why Should Clarksville Realtors Care?

    Pillar content is any rich original asset — a video, interview, or case study — from which all derivative pieces flow. Content atomization is the process of breaking that pillar into the smallest useful units: a quote graphic, a 15-second clip, a single tip, a pin. Evergreen content stays accurate and relevant for months or years (a buyer journey story, a VA loan walkthrough); ephemeral content is timely and short-lived (a “Closed today!” Stories post that expires in 24 hours). Smart Clarksville TN realtors build around a durable evergreen core with ephemeral content layered on top for immediate reach.

    Social media is the top lead source for 39% of REALTORS per the NAR 2025 Technology Survey, and 75% of agents use it as a primary tool. Yet most agents spend 2–3 hours producing a single post when the same effort, systematically applied, yields 10 pieces. That is a workflow problem, not a workload problem.

    The 10 Pieces of Content You Can Extract From Every Closing

    The table below maps each content type to its platform, primary purpose, and shelf life. Use it as a checklist at every closing.

    # Content Type Platform(s) Primary Purpose Shelf Life Time to Produce
    1 Closing-Day Reel Instagram, TikTok, Facebook Emotional proof, reach Ephemeral (peak 48 hrs) 15–30 min
    2 Carousel of the Buyer Journey Instagram, LinkedIn Education + authority Semi-evergreen (3–6 months) 30–45 min
    3 Client Testimonial Video YouTube, Google Business Profile, Website Trust, SEO, GBP ranking Evergreen (1–2 years) 10 min to record, 30 min to edit
    4 Just-Closed Graphic Facebook, Instagram, Stories Social proof, brand visibility Ephemeral (24–72 hrs) 5–10 min (Canva template)
    5 Blog Post Case Study Your website / thedealdoctor.blog SEO, long-tail keyword capture Evergreen (1–3 years) 60–90 min
    6 Email to Your Sphere Email list (Mailchimp, KVCore, etc.) Referral trigger, repeat business Evergreen (used as template) 20–30 min
    7 YouTube Long-Form Video YouTube Search discovery, deep trust Evergreen (2–5 years) 60–90 min (record + light edit)
    8 Stories Sequence (3–5 frames) Instagram Stories, Facebook Stories Engagement, behind-the-scenes Ephemeral (24 hrs, save to Highlight) 10–15 min
    9 Pinterest Pins (3–5 pins) Pinterest Long-tail SEO, home buyer discovery Evergreen (months to years) 15–20 min
    10 Google Business Profile Post Google Business Profile (GBP) Local SEO, map pack visibility Semi-evergreen (7-day GBP default) 5–10 min

    Pieces 3, 5, 7, and 9 are evergreen — they keep pulling mortgage pre-approval Clarksville and Fort Campbell home buying queries long after the closing date.

    How to Extract 10 Pieces of Content From One Closing in 7 Steps

    1. Get permission before you leave the table. Ask your client at closing: “Would you be comfortable with a quick video and a few social posts about your experience?” For Fort Campbell military clients, get written confirmation and clarify OPSEC boundaries. Document everything in your CRM. No permission = no content.
    2. Capture three closing-day shots before anyone leaves. You need: (a) a 30–60 second vertical selfie video with keys, (b) a wide photo at the signing table, and (c) an exterior shot if permitted. These three assets feed pieces 1, 3, 4, and 8. Clarksville real estate agents who build this habit cut production time by more than half.
    3. Record a 5–8 minute client interview on your phone. Ask three questions: What was the hardest part? What made you choose this neighborhood? What would you tell a friend about buying? This raw footage becomes your YouTube long-form (piece 7) and testimonial video (piece 3). The NAR 2025 Technology Survey found 46% of agents already use AI-generated content — use a transcription tool like Otter.ai or Descript to pull quotes for your blog and email automatically.
    4. Write the blog case study first — it anchors everything else. A 600–900 word anonymized case study covering the client’s situation, challenge, solution, and outcome is the narrative skeleton for every other piece. For military relocation Clarksville posts, focus on PCS timeline, VA loan process, and closing speed. Target long-tail queries like “Fort Campbell home buying timeline” and “VA loan closing Clarksville TN” that Nashville real estate market and Middle Tennessee buyers are actively searching.
    5. Slice the blog into platform-specific micro-content. From one blog post extract: three carousel slides, three Pinterest pins (one tip per pin), and one sphere email with a soft referral CTA. Per the HubSpot 2026 State of Marketing report, 39.5% of top-performing teams tailor content per platform — that discipline is what separates agents with 200 followers from agents with 20,000.
    6. Edit and post the video in two versions. Upload the full interview to YouTube with a keyword-rich title (“How a Fort Campbell Family Bought Their First Home in Clarksville TN”). Clip a 30–90 second vertical highlight for Instagram and TikTok Reels. According to real estate marketing data from NAR and HubSpot (2025), short-form video under 90 seconds drives 2x the engagement of long-form on every platform except YouTube — you need both.
    7. Publish your Google Business Profile post last. Two to three days after closing (once your blog is indexed), post 150–250 words with geo-rich language — “Clarksville TN,” “Montgomery County,” “near Fort Campbell” — and link to your case study. This signals active local presence to Google and improves map pack visibility for searches like mortgage pre-approval Clarksville and Clarksville TN realtors.

    Why This Matters Specifically for Clarksville and Fort Campbell Agents

    The Clarksville housing market and Nashville real estate market see constant buyer demand from military relocation, PCS moves, and commuter buyers. A closing story depicting the Fort Campbell home buying experience — a VA loan, a tight PCS timeline, a first-time buyer using the THDA first-time buyer program — speaks directly to the next buyer scrolling Instagram wondering if they can afford a home near Fort Campbell.

    Generic “Just Sold” graphics do not convert. A 30-second Reel of a military family getting their keys in Clarksville, paired with a blog post walking through their VA loan process and a Pinterest pin titled “How to Buy a Home in Clarksville TN on a PCS Timeline,” builds the authority that makes Clarksville TN realtors the obvious first call when orders come in. Treat every closing as a content event, not a paperwork finish line.

    FAQ — Content Repurposing for Real Estate Closings

    Do I need my client’s permission to post closing content on social media?

    Yes, always. Your client owns their likeness, their story, and their home address. Include a one-paragraph media release in your buyer packet before closing — specify what is shareable (social media, blog, email) and what is not (full address, purchase price). Keep a signed copy in your CRM for every transaction.

    How do I ask clients for a testimonial video without it feeling awkward?

    Frame it as helping the next buyer, not promoting yourself: “Would you share 2–3 minutes on video so other families know what to expect? It genuinely helps people who are in the exact spot you were six months ago.” Nearly every client says yes to that framing. Ask at closing while emotions are high — following up two weeks later rarely works.

    What about military and PCS clients with OPSEC concerns? Can I post their closing story?

    Military relocation Clarksville and Fort Campbell home buying clients may have real security concerns about sharing their address, unit, or even their faces publicly. Always get written permission, never post the property address or deployment details, avoid images with base access stickers or unit patches, and describe the client generically (“a Fort Campbell family on a PCS move”). Most service members appreciate that you asked proactively.

    Can I repurpose content from old closings I did before I had a system?

    Yes — with permission. Text past clients: “I’m building buyer success stories for my blog. Would you mind if I shared your experience (no personal details) in a short case study?” Most are flattered. For closings without photos, an anonymized text-only case study works fine. Old VA loans Clarksville TN and first-time homebuyer Clarksville stories are especially valuable for capturing current Nashville real estate market and Middle Tennessee search traffic.

    What do MLS rules say about marketing your own listings after closing?

    Most MLS boards permit post-closing marketing as long as you don’t misrepresent the property as available. “Just Closed” graphics, case study blog posts, and testimonial videos are generally permitted. Some boards restrict use of the MLS number or listing data in marketing — check your local rules (Greater Nashville MLS, Clarksville Association of REALTORS). When uncertain, describe the property by neighborhood and features rather than MLS ID or street address.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
  • Past-Client Reactivation: 12-Touchpoint Plan for Clarksville Realtors

    The Past-Client Reactivation Campaign: 12 Touchpoints That Generate Referrals on Autopilot

    A past-client reactivation campaign is a structured, 12-month sequence of value-driven touchpoints that keeps a Clarksville TN realtor top of mind with everyone they’ve ever closed — so referrals and repeat business arrive on autopilot. Per the NAR 2025 Member Trends report, the typical Realtor earns 20% of business from repeat clients and 21% from past-client referrals — 41 cents of every commission dollar. Among agents with 16+ years experience, repeat clients alone hit 40% of revenue. Chasing cold leads while your database collects dust leaves money on the table.

    This guide gives every Clarksville real estate agent — whether you serve Fort Campbell military families, Nashville commuters, or Montgomery County first-time buyers — a copy-paste 12-touchpoint annual sequence.

    Key Takeaways

    • The 12-touchpoint rule: One meaningful contact per month per past client — alternating value, personal, and surprise touches — keeps you top of mind without feeling spammy.
    • Past-client referrals are 41% of a typical Realtor’s income (20% repeat + 21% referral, per NAR 2025).
    • Clarksville’s 2025 median sale price was $313,724 with 74.9 days on market — a “relationship market” where trust beats algorithms (ClarksvilleNow / Redfin 2025).
    • The minimum cadence is quarterly per Zillow’s agent guide — but quarterly produces a fraction of the referrals that monthly produces.
    • The Holy Trinity of touches is: home anniversary gift, annual home-value review, and a “just thinking of you” personal note. Skip these three and the rest barely matters.
    • Pair with a Clarksville mortgage lender who can co-fund anniversary gifts and supply rate-update content — see the [INTERNAL LINK: Pre-Approval Partnership for Clarksville Realtors] playbook.

    Why past-client reactivation outperforms paid leads in Clarksville

    Reactivation is the highest-ROI channel a Clarksville real estate agent can run. Cold internet leads convert at 1–3%; warm past-client referrals convert at 40–60%. The NAR 2025 Profile of Real Estate Firms found 46% of firm-level sales volume comes from repeat business and 44% from past-client referrals — 90 cents of every dollar.

    The Clarksville housing market makes this even more valuable in 2026. Per ClarksvilleNow’s 2025 year-in-review, Montgomery County TN homes averaged 74.9 days on market and a $313,724 median sale price — 55% slower than the U.S. average. In a slower market, the agent already in the relationship wins.

    Reactivation is also a moat against PCS turnover. Fort Campbell home buying creates one of the most transient client bases in the country — but PCS works both ways. The military relocation Clarksville families you helped two years ago are texting friends asking “who’s the best Fort Campbell VA loan specialist?” You own that text thread or your competitor does.

    What is a past-client reactivation campaign?

    A past-client reactivation campaign is a deliberate, scheduled sequence of touchpoints — typically 12 over a calendar year — designed to maintain emotional and informational presence with everyone who has closed with you. It is the opposite of generic “drip marketing”: reactivation is automated where it should be and personal where it has to be, and it rewards people who already bought rather than chasing strangers.

    The 12-Touchpoint Annual Sequence (copy-paste calendar)

    This monthly calendar alternates three categories: Value (teach), Personal (connect), and Surprise (give a story to retell).

    1. January — Annual Home-Value Review (Value). Send each past client a 1-page “Your Home in 2026” PDF with estimated value, equity gained, comps in their Clarksville or Montgomery County TN neighborhood, and a soft refinance note if Nashville mortgage rates have dropped. The #1 lead generator of the 12.
    2. February — Tax-Time Document Pack (Value). Email a homeowner tax-prep PDF with their original Closing Disclosure attached. Pure helpfulness, zero pitch.
    3. March — Spring Maintenance Checklist (Value). Branded PDF covering HVAC, gutters, and termite season (which hits Middle Tennessee hard March–May). Include 3 local Clarksville vendor recommendations.
    4. April — “Just Thinking of You” Phone Call (Personal). Ten minutes, no agenda, no ask. Block 4 hours twice a year and crank through 24 calls.
    5. May — Mid-Year Market Update Video (Value). A 90-second iPhone video summarizing the Clarksville housing market: median price, days on market, rate trends. See [INTERNAL LINK: 60-Second iPhone Listing Video].
    6. June — Client Appreciation Event (Surprise). Annual summer cookout, lake day at Land Between the Lakes, or party at a Clarksville park. Past clients bring their friends — your referral multiplier of the year.
    7. July — Home Anniversary Gift (Surprise). A $25–$50 gift for July closings: engraved potted plant, Clarksville-themed cookbook, or coffee subscription. Always with a handwritten note.
    8. August — Back-to-School Drop-Off (Personal). For past clients with school-age kids, drop off a school-supply bag. The PTA-night story they tell is worth 10 paid leads.
    9. September — Fall Maintenance Checklist (Value). March’s template, updated for fall and winter prep.
    10. October — Trick-or-Treat Map (Surprise). Printable Clarksville/Fort Campbell-area map with safety tips. Local, useful, shareable.
    11. November — Handwritten Thanksgiving Card (Personal). Not Christmas. By December your card is one of 30; in November it’s one of three.
    12. December — Year-End Wrap (Value + Personal). Personal video + 2026 Clarksville market wrap + 2027 outlook. One direct question at the end: “Do you know anyone thinking about buying or selling in Clarksville, Fort Campbell, or Nashville next year?”

    How to set up the reactivation campaign in 7 steps

    1. Pull your full closing database from your CRM or title company. Export name, email, phone, closing date, address, anniversary month, and personal notes.
    2. Segment by closing anniversary month so the July anniversary gift only goes to July closings.
    3. Pre-write all 12 templates in January. Emails, video scripts, gift-note language, phone-call talking points — one focused weekend saves 40 hours over the year.
    4. Set monthly calendar reminders linked to the template and segmented contact list — zero friction at execution time.
    5. Pre-buy gifts in bulk in quarterly batches. Co-fund with a mortgage pre-approval Clarksville lender via the [INTERNAL LINK: Pre-Approval Partnership for Clarksville Realtors] playbook (consult compliance first).
    6. Track touches in a spreadsheet — one row per past client, one column per touch. Gaps mean missed months. Fix immediately.
    7. Ask for a referral only at touchpoint #12. Eleven months of giving earns one month of asking; earlier feels transactional.

    How often should you contact past clients?

    Monthly. Per Zillow’s agent best-practices guide, the absolute minimum is quarterly and ideally every six weeks. But the agents earning 40%+ of business from repeat clients (NAR 2025) all do some version of monthly. Twelve touches per year is the sweet spot between “top of mind” and “stop emailing me.”

    Reactivation cadence comparison: which schedule fits you?

    Cadence Touches / Year Time Investment Referral Yield Best For
    Quarterly 4 ~6 hrs/year Low Part-time agents; survival mode
    Every 6 Weeks 8–9 ~15 hrs/year Moderate Solo agent under 25 past clients
    Monthly (12 touches) 12 ~30 hrs/year High Most Clarksville real estate agents — recommended
    Bi-weekly 26 ~60+ hrs/year Diminishing returns Top-producing teams with 200+ past clients and an admin

    What kind of “value” should you actually send?

    Value-driven content is anything a past client would forward to a friend without feeling embarrassed. The test: would your past client text this to their sister? Three categories always pass:

    • Money-saving content — refinance opportunities when Nashville mortgage rates dip, property-tax appeal deadlines, or homestead exemption reminders for Tennessee homeowners.
    • Hyperlocal information — a Middle Tennessee market update specific to their ZIP code, Fort Campbell housing inventory shifts, or a new development on Wilma Rudolph Boulevard. See [INTERNAL LINK: Hyperlocal Playbook for Clarksville Realtors].
    • Practical homeowner tools — maintenance checklists, contractor recommendations, warranty reminders. Boring but bookmarked.

    Salesy emails fail the forward test. Save the ask for touchpoint #12, or for direct one-to-one conversations triggered by life events (new baby, job change, parent moving in).

    The Holy Trinity: the 3 touches you cannot skip

    If you only have time for three touches per year, run these. Together they produce more referrals than the other nine combined.

    1. The Home Anniversary Gift. A small, personal gift on the anniversary of their closing. Nobody else remembers — you become the only person who acknowledges their biggest financial decision.
    2. The Annual Home-Value Review. A 1-page hyperlocal CMA delivered every January. Every homeowner secretly wants to know what their house is worth — be the authority, not Zillow’s Zestimate.
    3. The “Just Thinking of You” Phone Call. Ten minutes, no agenda. In a world of bots and AI emails, an unprompted human phone call is genuinely shocking.

    Common reactivation mistakes Clarksville TN realtors make

    The most common mistake is treating reactivation like a marketing campaign instead of a relationship practice. Warning signs: every touch ends with “let me know if you need anything”; you only contact past clients when you need business; you send the same newsletter to first-time homebuyer Clarksville families and out-of-state Nashville investors. Other common mistakes: skipping the anniversary gift as “too expensive” (a $30 gift that earns one referral every five years pays 100x); only contacting via email; and asking for a referral on every touch (you’ll burn the relationship by July).

    How to integrate your lender into the reactivation campaign

    The smartest Clarksville real estate agents co-build reactivation campaigns with their lender. A Clarksville TN mortgage lender like Kate at The Blue Note Home (NMLS #18487, VanDyk Mortgage) can supply rate-update content for the January and May touches, co-host the June appreciation event, and provide free annual mortgage reviews. When VA loans Clarksville TN borrowers see annual value from both their agent and their Fort Campbell VA loan specialist, the referral rate roughly doubles. RESPA compliance matters — co-marketing must be split by fair-market value of services exchanged. Loop in your compliance officer first.

    FAQ — Past-Client Reactivation

    How many past clients do I need before a reactivation campaign is worth it?

    Anyone with 10 or more closings should run this. At 10 past clients with a 10% referral rate, you net one extra deal per year — which pays for the program 20x over. At 50 past clients, you’re netting 5 extra deals a year.

    What if I haven’t talked to past clients in years — is it too late?

    No. Run a 90-day Resurrection Sequence: month 1, a handwritten note acknowledging the gap; month 2, a 1-page home-value review; month 3, a personal phone call. Then resume the 12-month sequence. Half of “dead” past clients reactivate.

    How do I keep up with reactivation when I’m busy showing homes in Clarksville?

    Pre-write all 12 templates in January, batch gifts quarterly, and block phone calls in 4-hour sessions twice a year. Total annual time for 50 past clients is ~30 hours — less than one busy listing weekend.

    Should military and PCS clients get the same sequence?

    Yes, with one adjustment: add a PCS Check-In at the 18-month mark asking whether they’re staying or selling. Many active-duty Fort Campbell buyers convert their first home into a long-distance rental — you earn the property-management referral or the eventual sale either way.

    What CRM should I use?

    Any CRM that supports tagging and monthly reminders — Follow Up Boss, kvCORE, Wise Agent, or a well-organized Google Sheet. See [INTERNAL LINK: The CRM You Actually Need] for the 2026 buyer’s guide.

    Should I skip Christmas cards if I’m sending Thanksgiving cards?

    Yes — that’s the point. Holiday cards are commodity; Thanksgiving cards stand out. Pick one and execute it consistently.


    Written by Kate Matties-Deiboldt at The Blue Note Home — NMLS #18487, VanDyk Mortgage. Kate is a Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.
    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “headline”: “The Past-Client Reactivation Campaign: 12 Touchpoints for Clarksville Realtors”,
    “description”: “A copy-paste 12-month reactivation calendar for Clarksville TN realtors — the touchpoints that generate referrals and repeat business on autopilot.”,
    “datePublished”: “2026-05-22”,
    “dateModified”: “2026-05-22”,
    “author”: {“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”jobTitle”:”Licensed Mortgage Loan Originator (NMLS #18487)”,”worksFor”:{“@type”:”Organization”,”name”:”VanDyk Mortgage”}},
    “publisher”: {“@type”:”Organization”,”name”:”The Blue Note Home”,”logo”:{“@type”:”ImageObject”,”url”:”https://thedealdoctor.blog/wp-content/uploads/logo.png&#8221;}},
    “mainEntityOfPage”: “https://thedealdoctor.blog/past-client-reactivation-campaign-clarksville-realtors&#8221;,
    “keywords”: “past-client reactivation, Clarksville real estate agent, Fort Campbell VA loan specialist, Montgomery County TN homes, Middle Tennessee mortgage, referral marketing”
    },
    {
    “@type”: “BreadcrumbList”,
    “itemListElement”: [
    {“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog/&#8221;},
    {“@type”:”ListItem”,”position”:2,”name”:”For Realtors”,”item”:”https://thedealdoctor.blog/category/for-realtors/&#8221;},
    {“@type”:”ListItem”,”position”:3,”name”:”Past-Client Reactivation Campaign for Clarksville Realtors”}
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,
    “description”: “Clarksville TN mortgage lender and Fort Campbell VA loan specialist serving Montgomery County, Clarksville, Fort Campbell, Nashville, and Middle Tennessee.”,
    “address”: {“@type”:”PostalAddress”,”addressLocality”:”Clarksville”,”addressRegion”:”TN”,”addressCountry”:”US”},
    “areaServed”: [“Clarksville TN”,”Fort Campbell”,”Montgomery County TN”,”Nashville TN”,”Middle Tennessee”],
    “url”: “https://thedealdoctor.blog/&#8221;,
    “additionalProperty”: [{“@type”:”PropertyValue”,”name”:”NMLS”,”value”:”18487″}]
    },
    {
    “@type”: “HowTo”,
    “name”: “How to Set Up a Past-Client Reactivation Campaign in 7 Steps”,
    “description”: “Step-by-step setup for a 12-touchpoint annual reactivation campaign that generates referrals on autopilot for Clarksville TN realtors.”,
    “totalTime”: “PT8H”,
    “step”: [
    {“@type”:”HowToStep”,”position”:1,”name”:”Pull your full closing database”,”text”:”Export every past client from your CRM or title company into a single spreadsheet with name, email, phone, closing date, address, anniversary month, and personal notes.”},
    {“@type”:”HowToStep”,”position”:2,”name”:”Segment by closing anniversary month”,”text”:”Split contacts into 12 buckets by anniversary month so gifts and home-value reviews are personalized to each client’s closing date.”},
    {“@type”:”HowToStep”,”position”:3,”name”:”Pre-write all 12 templates in January”,”text”:”Draft email copy, video scripts, gift-note wording, and phone-call talking points for every month of the year in one focused weekend.”},
    {“@type”:”HowToStep”,”position”:4,”name”:”Set calendar reminders on the 1st of each month”,”text”:”Link each reminder to the template and segmented contact list to eliminate friction at execution time.”},
    {“@type”:”HowToStep”,”position”:5,”name”:”Pre-buy gifts in bulk”,”text”:”Order anniversary plants, cookbooks, or school-supply bags in quarterly batches to cut cost and execution time.”},
    {“@type”:”HowToStep”,”position”:6,”name”:”Track touches in a simple spreadsheet”,”text”:”One row per past client, one column per touch. Any gap means a missed month — fix immediately.”},
    {“@type”:”HowToStep”,”position”:7,”name”:”Ask for a referral only at touchpoint #12″,”text”:”Eleven months of giving earns one month of asking. Asking earlier makes the campaign feel transactional.”}
    ]
    },
    {
    “@type”: “FAQPage”,
    “mainEntity”: [
    {“@type”:”Question”,”name”:”How many past clients do I need before a reactivation campaign is worth it?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Anyone with 10 or more closings should run this. At 10 past clients with a 10% referral rate, you net one extra deal per year — which pays for the entire program 20x over. At 50 past clients, you’re netting 5 extra deals a year.”}},
    {“@type”:”Question”,”name”:”What if I haven’t talked to past clients in years — is it too late?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”No. Run a 90-day Resurrection Sequence: month 1 is a handwritten note acknowledging the gap; month 2 is a 1-page home-value review; month 3 is a personal phone call. Then resume the 12-month sequence. Half of ‘dead’ past clients reactivate when you reach out.”}},
    {“@type”:”Question”,”name”:”How do I keep up with reactivation when I’m busy showing homes in Clarksville?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Pre-write all 12 templates in January and batch the work. Anniversary gifts ship in quarterly bulk orders. Phone calls happen in 4-hour blocks twice a year. Total annual time investment for 50 past clients is about 30 hours.”}},
    {“@type”:”Question”,”name”:”Should military and PCS clients get the same sequence?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes, with one adjustment: add a PCS Check-In touch at the 18-month mark asking whether they’re staying or selling. Many active-duty Fort Campbell buyers convert their first home into a long-distance rental — you earn the property-management referral or the eventual sale either way.”}},
    {“@type”:”Question”,”name”:”What CRM should I use to manage past-client reactivation?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Any CRM that supports tagging and monthly reminders works — Follow Up Boss, kvCORE, Wise Agent, or a well-organized Google Sheet. The discipline matters more than the tool.”}},
    {“@type”:”Question”,”name”:”Is it OK to skip Christmas cards if I’m doing the November Thanksgiving card?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes — that’s the point. Holiday cards are commodity. Thanksgiving cards stand out. Pick the one you can execute consistently and excellently, and skip the other.”}}
    ]
    },
    {“@type”:”SpeakableSpecification”,”cssSelector”:[“.key-takeaways”,”h1″,”p:first-of-type”]}
    ]
    }

  • Past-Client Reactivation: 12 Touchpoints for Clarksville Realtors

    For Clarksville TN realtors, Fort Campbell agents, and Nashville real estate pros who want referrals without spending a dollar on Facebook ads.

    The fastest way to grow a Clarksville real estate business in 2026 is not buying leads — it is reactivating the past clients you already have. A past-client reactivation campaign is a structured, year-long sequence of 12 intentional touchpoints (one per month) that keeps a Clarksville TN realtor or Fort Campbell agent top of mind so that referrals, repeat business, and reviews arrive on autopilot. Used consistently, a 12-touch plan typically returns 15–25% of past clients as new transactions or referrals within 18 months, far outperforming most paid lead channels in Middle Tennessee.

    Key Takeaways

    • What it is: A 12-month, 12-touch plan to stay in front of past Clarksville and Fort Campbell clients without feeling salesy.
    • Why it works: The National Association of REALTORS® reports that 89% of buyers would use their agent again, but only 12% actually do — the gap is follow-up.
    • What you need: A CRM, a clean past-client list, and 60 minutes a month to execute.
    • What to expect: 1 referral or repeat closing per 8–12 actively-nurtured past clients per year is a realistic Middle Tennessee benchmark.
    • Local edge: Tie touches to the Clarksville, Fort Campbell, and Nashville calendar — PCS season, Riverfest, school start, tax time — to feel local, not generic.

    Why past-client reactivation beats buying leads in Clarksville

    A past-client reactivation campaign is a deliberate marketing system that turns prior buyers and sellers back into a source of new transactions. For a Clarksville real estate agent or Fort Campbell VA loan specialist, this is the highest-ROI channel available. Online leads from Zillow, Realtor.com, and Facebook ads in the Clarksville and Nashville markets convert at roughly 1–3%, according to NAR’s 2025 research data. Referrals from past clients convert closer to 50%.

    And the Clarksville housing market is uniquely positioned for this strategy. Fort Campbell drives roughly 4,000–5,000 PCS moves into and out of Montgomery County every year, which means today’s buyer is tomorrow’s seller — often within 24–36 months. Miss the touch window and that listing goes to whichever Clarksville TN realtor sent a Christmas card.

    What is a past-client reactivation touchpoint?

    A touchpoint is any deliberate, value-first contact between a real estate agent and a past client — an email, text, mailer, gift, phone call, or social interaction designed to build relationship rather than ask for business. The “12 touchpoints” framework simply assigns one touch per month, so no past client ever goes more than 30 days without hearing from you.

    The 12-touch annual plan for Clarksville and Fort Campbell realtors

    Below is the exact 12-month sequence I recommend to Clarksville TN realtors and Nashville real estate agents I partner with on VA loans and first-time homebuyer files. Adjust dates to your local market, but keep the cadence.

    MonthTouchFormatGoal
    January“New Year, New Equity” home value reportEmail + PDFRe-anchor your role as their property advisor
    FebruaryTax-time reminder (mortgage interest + property tax docs)EmailBe useful when other agents disappear
    MarchSpring market update for Clarksville & Montgomery CountyVideo + emailEstablish authority on local market
    AprilHome-anniversary card + handwritten noteMailEmotional touch — celebrate their home
    MayPCS season check-in for Fort Campbell familiesText or callCatch military movers early
    JuneSummer maintenance checklist (HVAC, gutters, exterior)Email + downloadable PDFValue-first content
    JulyClient appreciation event (BBQ, ice cream truck, or pool party)In-personFace-to-face relationship deposit
    August“Back to school” neighborhood + school district guideEmail + socialHyperlocal positioning
    SeptemberRiverfest / local event invite or recapText + social tagBe the local insider
    OctoberHome value & equity report (refi or move-up trigger)Email + 1:1 call offerConvert equity into a transaction
    NovemberPumpkin or pie drop-off (Clarksville/Nashville-area only)In-personThe highest-converting touch of the year
    DecemberYear-end thank-you card + charitable donation in their nameMailClose the year with gratitude

    How to set up your 12-touch reactivation system in 60 minutes

    1. Clean your database. Export your past-client list from your Clarksville real estate CRM (Follow Up Boss, kvCORE, Sierra Interactive, or even a Google Sheet). Verify emails, phone numbers, and home addresses.
    2. Tag by client type. Use tags such as Fort Campbell VA buyer, Clarksville first-time buyer, Nashville move-up, investor, and relocation. Tags let you personalize each touch.
    3. Build the calendar. Schedule all 12 touches in your CRM at the start of the year. Set the “send date” 7 days before each touch goes out.
    4. Pre-write your assets. Draft the 12 emails, 3 mail pieces, and 4 video scripts in one batch. ChatGPT or a custom GPT can shave this from 8 hours to about 90 minutes.
    5. Automate what you can; humanize what you cannot. Emails, market reports, and texts can fire automatically. Handwritten notes, calls, and the pie drop-off must be done by you.
    6. Track results monthly. Log replies, calls, referrals, and closings against each touch. After 90 days you will know which touchpoints are pulling weight in the Clarksville and Nashville markets.

    Tools to power the campaign

    • CRM: Follow Up Boss, kvCORE, or HubSpot Free — any of these handle the cadence for a Clarksville TN realtor.
    • Email: Mailchimp or ActiveCampaign for newsletters and market updates.
    • Direct mail: Handwrytten or Postable for the handwritten-feel cards.
    • Local market data: Pull monthly stats from RealTracs MLS or the Tennessee REALTORS® reports for Montgomery County and Davidson County.
    • Video: A smartphone and BombBomb or Loom for personal video touches.

    The PCS multiplier: a special note for Fort Campbell agents

    Military buyers are the highest-velocity past-client pool in the Clarksville housing market. The average soldier at Fort Campbell PCSs every 24–36 months, which means a single Fort Campbell VA loan transaction can generate 3–5 referrals before that family rotates out. If you specialize in PCS to Fort Campbell, layer two extra touches on top of the 12: a “PCS orders confirmed?” text every March and September, the two heaviest move cycles; and a “VA entitlement restoration” email partnered with a Fort Campbell VA loan specialist so they understand they can use the benefit again.

    Common mistakes that kill the campaign

    • Asking for referrals every touch. Value first. Ask twice a year, max.
    • Sending the same generic newsletter to every contact. A Nashville move-up buyer should not get the same email as a Fort Campbell VA borrower.
    • Skipping months. Two missed months breaks the rhythm and you start over emotionally with the client.
    • Outsourcing the human moments. Handwritten notes, calls, and pie drop-offs cannot be delegated.

    FAQ: Past-client reactivation for Clarksville and Nashville realtors

    How often should a Clarksville real estate agent contact past clients?

    At minimum once a month — 12 intentional touches per year. Less than that and you lose the referral and repeat-business window, especially with Fort Campbell military families who move every 24–36 months.

    What is the best CRM for Clarksville TN realtors managing past clients?

    Follow Up Boss and kvCORE are the two most commonly used by top-producing Clarksville and Nashville real estate teams. For solo agents on a tight budget, HubSpot Free plus a simple Google Sheet works for the first 100–200 past clients.

    How long until a past-client campaign produces referrals?

    Expect the first measurable lift in referrals within 90–120 days, with full ROI by month 12. Compounding starts in year two.

    Can I co-market the reactivation campaign with a mortgage lender?

    Yes — and you should. Partnering with a Clarksville TN mortgage lender or Fort Campbell VA loan specialist lets you split content costs and add value (equity reports, refi reviews, VA entitlement updates) the agent alone cannot deliver. Just keep co-marketing arrangements RESPA-compliant and document fair-market split.

    What single touchpoint produces the most referrals?

    For most Clarksville and Middle Tennessee agents, the November pie drop-off and the July client appreciation event consistently produce the highest direct referral count. The annual home-anniversary card is the highest-ROI mailed touch.

    Next step

    If you are a Clarksville TN realtor, Fort Campbell agent, or Nashville real estate pro who wants the editable 12-touch calendar, plus the partner-lender co-marketing pieces I provide my Realtor partners, reach out to me at The Deal Doctor / Blue Note Home. I will send you the templates and we can map the campaign to your database in one sitting.

    Written by Kate at The Blue Note Home — VA loan specialist serving Clarksville, TN, Fort Campbell, KY, and the greater Nashville and Middle Tennessee mortgage market.

    {“@context”:”https://schema.org&#8221;,”@graph”:[{“@type”:”Article”,”headline”:”Past-Client Reactivation Campaign: 12 Touchpoints for Clarksville Realtors”,”description”:”A 12-month, 12-touch reactivation system that generates Clarksville, Fort Campbell, and Nashville realtor referrals on autopilot.”,”author”:{“@type”:”Person”,”name”:”Kate”,”jobTitle”:”VA Loan Specialist / Mortgage Loan Officer”,”worksFor”:{“@type”:”Organization”,”name”:”The Blue Note Home”}},”publisher”:{“@type”:”Organization”,”name”:”The Blue Note Home”,”url”:”https://thedealdoctor.blog&#8221;},”datePublished”:”2026-05-21″,”dateModified”:”2026-05-21″,”mainEntityOfPage”:”https://thedealdoctor.blog/&#8221;,”keywords”:”past client reactivation, Clarksville TN realtor, Fort Campbell real estate agent, Nashville mortgage, VA loan Clarksville, real estate referrals, realtor marketing, Middle Tennessee mortgage”},{“@type”:”FAQPage”,”mainEntity”:[{“@type”:”Question”,”name”:”How often should a Clarksville real estate agent contact past clients?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”At minimum once a month — 12 intentional touches per year. Less than that and you lose the referral and repeat-business window, especially with Fort Campbell military families who move every 24–36 months.”}},{“@type”:”Question”,”name”:”What is the best CRM for Clarksville TN realtors managing past clients?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Follow Up Boss and kvCORE are the two most commonly used by top-producing Clarksville and Nashville real estate teams. For solo agents on a tight budget, HubSpot Free plus a simple Google Sheet works for the first 100–200 past clients.”}},{“@type”:”Question”,”name”:”How long until a past-client campaign produces referrals?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Expect the first measurable lift in referrals within 90–120 days, with full ROI by month 12. Compounding starts in year two.”}},{“@type”:”Question”,”name”:”Can I co-market the reactivation campaign with a mortgage lender?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes — partnering with a Clarksville TN mortgage lender or Fort Campbell VA loan specialist lets you split content costs and add value. Keep co-marketing arrangements RESPA-compliant and document fair-market split.”}},{“@type”:”Question”,”name”:”What single touchpoint produces the most referrals?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”For most Clarksville and Middle Tennessee agents, the November pie drop-off and the July client appreciation event produce the highest referral count. The annual home-anniversary card is the highest-ROI mailed touch.”}}]},{“@type”:”BreadcrumbList”,”itemListElement”:[{“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog/&#8221;},{“@type”:”ListItem”,”position”:2,”name”:”For Realtors”,”item”:”https://thedealdoctor.blog/category/for-realtors/&#8221;},{“@type”:”ListItem”,”position”:3,”name”:”Past-Client Reactivation Campaign”}]},{“@type”:”LocalBusiness”,”name”:”The Blue Note Home — Kate, VA Loan Specialist”,”areaServed”:[“Clarksville, TN”,”Fort Campbell, KY”,”Nashville, TN”,”Montgomery County, TN”,”Middle Tennessee”],”url”:”https://thedealdoctor.blog&#8221;,”address”:{“@type”:”PostalAddress”,”addressLocality”:”Clarksville”,”addressRegion”:”TN”,”addressCountry”:”US”},”description”:”Mortgage loan officer specializing in VA loans, first-time homebuyer programs, and Fort Campbell military relocations in the Clarksville and Nashville markets.”},{“@type”:”HowTo”,”name”:”How to set up a 12-touch past-client reactivation campaign”,”step”:[{“@type”:”HowToStep”,”position”:1,”name”:”Clean your database”,”text”:”Export your past-client list from your CRM and verify emails, phones, and addresses.”},{“@type”:”HowToStep”,”position”:2,”name”:”Tag by client type”,”text”:”Use tags like Fort Campbell VA buyer, Clarksville first-time buyer, and Nashville move-up to personalize touches.”},{“@type”:”HowToStep”,”position”:3,”name”:”Build the calendar”,”text”:”Schedule all 12 monthly touches in your CRM at the start of the year.”},{“@type”:”HowToStep”,”position”:4,”name”:”Pre-write your assets”,”text”:”Batch-write 12 emails, 3 mail pieces, and 4 video scripts in one session.”},{“@type”:”HowToStep”,”position”:5,”name”:”Automate and humanize”,”text”:”Automate emails and texts; keep handwritten notes, calls, and in-person events manual.”},{“@type”:”HowToStep”,”position”:6,”name”:”Track monthly”,”text”:”Log replies, calls, referrals, and closings against each touchpoint to measure ROI.”}]},{“@type”:”WebPage”,”speakable”:{“@type”:”SpeakableSpecification”,”cssSelector”:[“h1″,”h2″,”ul”]}}]}
  • How to Get 10 Clarksville Clients From Facebook Groups (No Spam)

    You can absolutely get your first — or your next — 10 clients from Facebook Groups without being spammy, but only if you flip the strategy from “promote myself” to “be the most useful person in the room.” For a Clarksville real estate agent serving Fort Campbell families, first-time homebuyers, and Nashville-area relocators, local Facebook Groups remain one of the highest-trust lead channels available in 2026.

    This playbook shows you exactly how to do it — which Groups to join, what to post, how to respond, and the lender partnership that converts a helpful comment into a closed Montgomery County transaction.

    Key Takeaways

    • Meta’s Family of Apps now reaches 3.56 billion daily active people, with ad impressions up 19% year-over-year in Q1 2026 (Meta Investor Relations Q1 2026) — your Clarksville buyers and sellers are inside Facebook Groups every single day.
    • Meta’s average price per ad rose 12% YoY in Q1 2026 (Meta IR 2026), making organic Group engagement more valuable than ever for budget-conscious Clarksville TN realtors.
    • 88% of buyers use a real estate agent and 76% of first-time buyers say their agent helped them understand the process (NAR 2025 Profile of Home Buyers & Sellers) — Groups are where they’re asking their pre-agent questions.
    • The framework is simple: 10x more helpful answers than promotional posts, plus one Clarksville TN mortgage lender partner who can field the qualifying calls inside 24 hours.
    • Most Clarksville Facebook Groups ban listings, but none ban genuinely helpful local expertise — that’s the loophole.

    Why Facebook Groups still work for Clarksville real estate agents

    A Facebook Group is a community space inside Facebook where members post questions, opinions, and recommendations on a focused topic — a neighborhood, a military base, a hobby. Facebook Groups work because they replicate the small-town referral economy at digital scale: people inside the Group trust other members more than they trust paid ads. For a Clarksville real estate agent, that trust is the entire game.

    The Clarksville housing market is dense with active local Groups: “Clarksville TN Buy Sell Trade,” “Fort Campbell Spouses,” “Clarksville Moms,” “PCS to Fort Campbell,” “Nashville-Clarksville Relocation,” and a dozen subdivision-specific Groups across Montgomery County. Every day, members ask “Who’s a good Clarksville TN mortgage lender?” or “What’s a fair price for a 3-bed in Sango?” The agent who answers thoughtfully — without pasting a listing — wins the next message.

    What “spammy” looks like — and why it backfires

    Spammy Group behavior is any post or comment that prioritizes the agent’s promotion over the asker’s question. Spam in a Clarksville Facebook Group looks like: dropping a listing into an unrelated thread, posting “DM me!” without value, copy-pasting the same comment across 10 Groups, or tagging strangers in your branded posts. Spammy behavior kills your reputation in Middle Tennessee faster than any other marketing mistake — and most Group admins ban repeat offenders within 48 hours.

    The opposite of spammy is “obviously useful and clearly local.” That’s the bar.

    The 5 Clarksville Facebook Group types you should be in

    1. Hyperlocal community Groups — “Clarksville TN Community,” “Clarksville Moms,” “Sango Neighbors.” High signal, high trust, low listings tolerance. Be useful, don’t promote.
    2. Military and Fort Campbell Groups — “Fort Campbell Spouses,” “PCS to Fort Campbell,” “101st Airborne Family Support.” Critical for military relocation Clarksville, Fort Campbell home buying, and Fort Campbell VA loan specialist intros.
    3. Relocation Groups — “Moving to Clarksville TN,” “Nashville to Clarksville Move.” These are pre-buyers in the research phase — the highest-intent free lead source on the internet.
    4. Buy/sell/trade Groups — “Clarksville TN Buy Sell Trade,” “Montgomery County Yard Sale.” Usually ban listings, but reveal life-stage triggers (downsizing, moving, divorce).
    5. Niche interest Groups — Schools (Hilldale, Rossview), churches, gyms, dog parks. These are your sphere expansion Groups, not your lead-gen Groups, but they compound your local credibility.

    How to get your first 10 clients from Facebook Groups (step-by-step)

    1. Audit and join 10 Groups. Two from each of the five categories above. Read the rules. Most Clarksville Groups explicitly ban realtor self-promotion — respect that.
    2. Optimize your personal Facebook profile. Profile photo, banner, bio (“Clarksville TN Realtor + Fort Campbell relocation specialist”), and pinned post should make your role obvious without being aggressive. People will click your profile after you comment — that’s the conversion surface.
    3. Commit to a 10:1 ratio. Ten genuinely helpful comments or posts for every one piece of softer self-promotion (a market update, a community event, an “AMA” post). Track it in a spreadsheet for the first 60 days.
    4. Reply to two “agent recommendation” threads per day. When someone asks “Who’s a good Clarksville real estate agent?” don’t tag yourself — let other people do it. Instead, contribute a useful follow-up answer about Montgomery County TN homes, the Clarksville housing market, or mortgage pre-approval Clarksville workflows. Recommendations come, organically.
    5. Build a Clarksville TN mortgage lender partnership. When a Group member asks “What’s a VA loan?” or “How much do I need to put down on a $300K home?” you escalate to your Fort Campbell VA loan specialist. They pre-qualify. You list. [INTERNAL LINK: pre-approval partnership for Clarksville realtors]
    6. Publish one valuable original post per Group per month. A Sango price update. A Fort Campbell PCS arrival checklist. A “5 things first-time buyers in Clarksville always ask me” thread. No CTA. Just value.
    7. Host one community event per quarter and invite the Groups. A first-time homebuyer Clarksville Q&A at a local coffee shop. A “Selling Before You PCS” workshop on a Saturday morning. Event + Group + lender = the most reliable lead funnel in Middle Tennessee. [INTERNAL LINK: free home valuation funnel for Clarksville realtors]
    8. Move every promising conversation to DM within 48 hours. Once a Group member engages with you twice, you’ve earned a DM. Don’t pitch — offer the next useful resource (CMA, pre-approval intro, neighborhood guide).

    Comparison: how Facebook Groups stack up against other free Clarksville lead channels

    Channel Trust signal Time to first lead Cost Best for
    Local Facebook Groups Very high (peer-driven) 2–6 weeks $0 First-time buyers, PCS relocators
    Facebook ads (Lead Forms) Low–medium Days $20–$50/day Listing-focused agents with a CRM
    Google Business Profile High (review-driven) 1–3 months $0 Sellers searching “Clarksville real estate agent”
    Open houses Medium Same-day $50–$200 per OH Buyer leads in active inventory
    Postcards Low 12–24 months $0.60–$1.20 per home Long-runway farms only

    What kind of posts and comments actually work?

    The format that wins in Clarksville Facebook Groups is consistent: a focused, locally-specific answer to a real question, delivered without a sales pitch. Three examples:

    Agent recommendation thread. Member: “Who’s a good first-time buyer agent in Clarksville?” You don’t say “me.” You reply with: “First-time buyers in Clarksville often qualify for THDA down payment assistance — make sure whoever you pick can walk you through that, plus FHA, VA, and USDA loans. Happy to share a quick checklist if helpful.” That comment generates DMs.

    PCS-to-Fort-Campbell question. Member: “PCSing in August, where should we live near post?” You reply with a 4-line answer covering Sango, St. Bethlehem, Oak Grove, and gate-distance trade-offs. No listings. No “DM me.” Just genuinely useful military relocation Clarksville info.

    Market-update post (monthly). “April 2026 Clarksville housing market: 2,200 active listings, $337K median, 61 days on market. Translation for buyers: more leverage than last year. Translation for sellers: pricing matters more than ever. Questions welcome.” That’s the kind of post Group members save and share — and it’s how Clarksville TN realtors become the recognized expert.

    How a Clarksville TN mortgage lender supercharges your Group strategy

    The single biggest unlock for Group-driven lead gen is a tight lender partnership. When a Group member asks a financing question, you don’t fumble — you intro them to a Clarksville TN mortgage lender or Fort Campbell VA loan specialist who can run mortgage pre-approval Clarksville scenarios the same day. That handoff does three things: it gives the member a real answer, it positions you as the connector (not the salesperson), and it gets the buyer pre-approved before your competition even sees the lead.

    The lender, in turn, handles the BAH, the VA entitlement, the THDA stack, the Nashville mortgage rates question — all the technical work that makes your Group comments credible. For Clarksville TN realtors, this partnership is the difference between Groups as a “vibes” channel and Groups as a closing-table channel.

    FAQ: Facebook Group Lead Generation for Clarksville Realtors

    How long until Facebook Groups produce a closing for a Clarksville real estate agent?

    Most agents who follow the 10:1 helpful-to-promotional ratio see their first DM lead within 2–6 weeks and their first closing within 60–120 days. Groups are a compounding channel, not a sprint.

    Should I create my own Facebook Group for Clarksville real estate?

    Eventually, yes — but not until you’ve spent 90+ days being the most helpful contributor in 5–10 existing local Groups. Build your authority inside others’ communities first; launch your own once you have 100+ people who already trust you.

    Is it okay to post listings inside Clarksville Facebook Groups?

    Almost never. Most Clarksville Groups explicitly ban realtor listings, and the ones that allow them have low engagement. Use Facebook Marketplace and your own page for listings; use Groups for relationship and authority.

    How do I find the best Fort Campbell and military Facebook Groups?

    Search Facebook for “Fort Campbell,” “PCS to Fort Campbell,” “101st Airborne,” and “Clarksville military.” Join the Groups with 5,000+ members and active daily posting. Read the rules carefully — military Groups are stricter about promotion than civilian Groups.

    What’s the right cadence — daily, weekly, monthly?

    Daily light engagement (2–4 helpful comments), weekly mid-touch (one substantive answer or thread), monthly heavy-touch (one original post per Group, one market update). Burn out is the #1 reason agents abandon Facebook Groups, so build a sustainable rhythm from day one.

    Can my Clarksville TN mortgage lender post in the Groups too?

    Yes — and they should. A lender who answers financing questions in the same Groups you serve doubles your authority and creates natural cross-referrals. Coordinate on which Groups each of you focuses on so you’re not duplicating effort.

    The bottom line for Clarksville TN realtors

    Facebook Groups are still the highest-trust, lowest-cost lead channel available for a Clarksville real estate agent in 2026 — but only for agents who lead with usefulness, not promotion. Pair the 10:1 ratio with a strong Clarksville TN mortgage lender partnership, focus on Fort Campbell military Groups and hyperlocal Montgomery County communities, and the next 10 clients are 60–120 days away.

    Written by Kate Matties-Deiboldt at The Blue Note Home — Licensed Mortgage Loan Originator, NMLS #18487, VanDyk Mortgage. Serving first-time homebuyers, veterans, sellers, and PCS relocators across Clarksville, Fort Campbell, Montgomery County, Nashville, and Middle Tennessee.
    {“@context”:”https://schema.org&#8221;,”@graph”:[{“@type”:”Article”,”@id”:”https://thedealdoctor.blog/facebook-groups-lead-generation-clarksville-realtors/#article&#8221;,”headline”:”How to Get 10 Clarksville Clients From Facebook Groups (No Spam)”,”description”:”The spam-free Facebook Group playbook for Clarksville TN realtors — which Groups to join, what to post, and how to convert helpful comments into closings.”,”datePublished”:”2026-05-21″,”dateModified”:”2026-05-21″,”author”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”jobTitle”:”Licensed Mortgage Loan Originator (NMLS #18487)”,”worksFor”:{“@type”:”Organization”,”name”:”VanDyk Mortgage”}},”publisher”:{“@type”:”Organization”,”name”:”The Blue Note Home”,”url”:”https://thedealdoctor.blog&#8221;},”mainEntityOfPage”:”https://thedealdoctor.blog/facebook-groups-lead-generation-clarksville-realtors/&#8221;,”about”:[“Facebook Groups real estate marketing”,”Real estate lead generation”,”Clarksville housing market”,”Fort Campbell military relocation”]},{“@type”:”FAQPage”,”@id”:”https://thedealdoctor.blog/facebook-groups-lead-generation-clarksville-realtors/#faq&#8221;,”mainEntity”:[{“@type”:”Question”,”name”:”How long until Facebook Groups produce a closing for a Clarksville real estate agent?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Most agents who follow the 10:1 helpful-to-promotional ratio see their first DM lead within 2-6 weeks and their first closing within 60-120 days. Groups are a compounding channel, not a sprint.”}},{“@type”:”Question”,”name”:”Should I create my own Facebook Group for Clarksville real estate?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Eventually, yes – but not until you’ve spent 90+ days being the most helpful contributor in 5-10 existing local Groups. Build your authority inside others’ communities first; launch your own once you have 100+ people who already trust you.”}},{“@type”:”Question”,”name”:”Is it okay to post listings inside Clarksville Facebook Groups?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Almost never. Most Clarksville Groups explicitly ban realtor listings, and the ones that allow them have low engagement. Use Facebook Marketplace and your own page for listings; use Groups for relationship and authority.”}},{“@type”:”Question”,”name”:”How do I find the best Fort Campbell and military Facebook Groups?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Search Facebook for ‘Fort Campbell,’ ‘PCS to Fort Campbell,’ ‘101st Airborne,’ and ‘Clarksville military.’ Join the Groups with 5,000+ members and active daily posting. Read the rules carefully – military Groups are stricter about promotion than civilian Groups.”}},{“@type”:”Question”,”name”:”What’s the right cadence – daily, weekly, monthly?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Daily light engagement (2-4 helpful comments), weekly mid-touch (one substantive answer or thread), monthly heavy-touch (one original post per Group, one market update). Burn out is the #1 reason agents abandon Facebook Groups, so build a sustainable rhythm from day one.”}},{“@type”:”Question”,”name”:”Can my Clarksville TN mortgage lender post in the Groups too?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes – and they should. A lender who answers financing questions in the same Groups you serve doubles your authority and creates natural cross-referrals. Coordinate on which Groups each of you focuses on so you’re not duplicating effort.”}}]},{“@type”:”BreadcrumbList”,”itemListElement”:[{“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog&#8221;},{“@type”:”ListItem”,”position”:2,”name”:”For Realtors”,”item”:”https://thedealdoctor.blog/category/for-realtors/&#8221;},{“@type”:”ListItem”,”position”:3,”name”:”Facebook Groups Lead Gen”,”item”:”https://thedealdoctor.blog/facebook-groups-lead-generation-clarksville-realtors/&#8221;}]},{“@type”:”LocalBusiness”,”@id”:”https://thedealdoctor.blog/#localbusiness&#8221;,”name”:”The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,”description”:”Mortgage Loan Originator serving Clarksville, Fort Campbell, Nashville, and Middle Tennessee.”,”address”:{“@type”:”PostalAddress”,”addressLocality”:”Clarksville”,”addressRegion”:”TN”,”addressCountry”:”US”},”areaServed”:[“Clarksville TN”,”Fort Campbell”,”Montgomery County TN”,”Nashville TN”,”Middle Tennessee”,”Kentucky”],”founder”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”identifier”:”NMLS #18487″}},{“@type”:”HowTo”,”name”:”How to Get 10 Clients From Clarksville Facebook Groups Without Being Spammy”,”step”:[{“@type”:”HowToStep”,”position”:1,”name”:”Audit and join 10 Groups”,”text”:”Two from each of five categories: hyperlocal, military, relocation, buy/sell/trade, niche interest.”},{“@type”:”HowToStep”,”position”:2,”name”:”Optimize your personal Facebook profile”,”text”:”Profile photo, banner, bio, and pinned post should make your Clarksville real estate role obvious.”},{“@type”:”HowToStep”,”position”:3,”name”:”Commit to a 10:1 helpful-to-promotional ratio”,”text”:”Ten genuinely helpful posts or comments for every one piece of soft self-promotion.”},{“@type”:”HowToStep”,”position”:4,”name”:”Reply to two agent-recommendation threads daily”,”text”:”Don’t tag yourself – contribute useful follow-up answers and let other members recommend you.”},{“@type”:”HowToStep”,”position”:5,”name”:”Build a Clarksville TN mortgage lender partnership”,”text”:”Escalate financing questions to your lender partner for same-day pre-approval.”},{“@type”:”HowToStep”,”position”:6,”name”:”Publish one valuable original post per Group per month”,”text”:”Market updates, neighborhood deep-dives, PCS checklists – no CTA, just value.”},{“@type”:”HowToStep”,”position”:7,”name”:”Host one community event per quarter and invite the Groups”,”text”:”First-time homebuyer Q&A or selling-before-PCS workshop turns digital engagement into in-person relationships.”},{“@type”:”HowToStep”,”position”:8,”name”:”Move every promising conversation to DM within 48 hours”,”text”:”Once a member engages twice, offer the next useful resource via DM – never a hard pitch.”}]},{“@type”:”SpeakableSpecification”,”cssSelector”:[“.key-takeaways”,”h1″,”h1 + p”]}]}

  • 5 Geographic Farming Tactics That Outperform Clarksville Postcards

    Geographic farming still works in 2026 — postcards mostly don’t. For a Clarksville real estate agent trying to dominate a neighborhood in Montgomery County, the five tactics below outperform a traditional direct-mail farm on both cost and conversion. Postcards still belong in the mix, but they should be the smallest line item, not the whole budget.

    This guide is written for Clarksville TN realtors, Fort Campbell-area agents, and Middle Tennessee teams who want a modern geographic farm: cheaper, faster, more measurable, and built around the way Clarksville homeowners actually shop for an agent today.

    TL;DR — Key Takeaways

    • Traditional farms cost about $1 per home per month and typically take 12–24 months to produce a first listing (Brian Curtis 2025).
    • A healthy farm area needs a 5–7%+ annual turnover rate — divide homes sold last 12 months by total homes in the area (NAR / RPR).
    • Direct mail has high open rates (~91%) but commodity ROI in real estate — 43% of buyers still choose an agent based on a personal referral (HousingWire 2026).
    • Switching from geographic-only to demographic-overlay farming has driven coached agents to ~6x more transactable households on the same $1,000/month budget (Brian Curtis 2025).
    • For Clarksville real estate agents, the biggest unlock is layering Fort Campbell PCS rotations, Nashville commuter inflow, and Montgomery County turnover data on top of any farm.

    What is geographic farming?

    Geographic farming is a long-term marketing strategy where a Clarksville real estate agent consistently markets to every household inside a defined neighborhood, ZIP, or precinct to become the recognized “go-to agent” of that area. Geographic farming is a brand-building play, not a lead-gen sprint. It is the practice of dominating one slice of the Clarksville housing market through repeated, useful touches — not a single postcard drop.

    Done well, farming generates listings at a 10–20% market-share rate inside the farm over 24–36 months. Done poorly, it bleeds money on postcards no one opens. The five tactics below assume you’re playing the long game — and want better ROI than 4×6 mailers can deliver.

    Why postcards alone underperform in the Clarksville housing market

    Postcards have three structural problems in 2026: cost per impression has risen, attention has fragmented, and Clarksville homeowners — especially younger Fort Campbell-area buyers — vet agents on Google, Instagram, and YouTube before they ever pick up the mail. Postcards still produce some leads, but at a much lower ROI than the digital and hybrid tactics that anchor a modern Middle Tennessee farm.

    Postcards also can’t be retargeted. Once mailed, the touch is over. Every tactic below compounds: the more homes that see it, the cheaper the next impression gets. [INTERNAL LINK: hyperlocal playbook for Clarksville realtors]

    5 geographic farming tactics that outperform postcards in 2026

    1. Hyperlocal Facebook + Instagram retargeting around your farm polygon

    Hyperlocal social retargeting is the practice of running tightly geo-fenced Meta ads to homeowners inside a defined Clarksville farm polygon (a Sango ZIP, a St. Bethlehem subdivision, the 4-mile Fort Campbell catchment). Costs typically run $0.10–$0.40 per impression — a fraction of the $0.60–$1.20 effective cost of a printed postcard. Run a short market-update reel, a just-sold post, or a “what’s my Clarksville home worth?” CTA. Layer in a custom audience from your free home valuation funnel and your CRM and you’ve quietly built the most efficient ad of any Clarksville TN mortgage lender or realtor in Montgomery County.

    2. Google Business Profile + neighborhood-specific blog posts

    Google Business Profile is the most underused free farming tool available to a Clarksville real estate agent. Optimize your GBP for “Clarksville real estate agent,” post weekly market updates with photos from inside the farm area, and pair every post with a long-form blog post on your site targeting one neighborhood at a time — “Homes for Sale in Sango,” “Buying in St. Bethlehem near Fort Campbell,” “Hilldale Schools Real Estate Report.” Google’s local algorithm rewards farms that are documented in writing. Postcards do not get indexed.

    3. Quarterly neighborhood market reports delivered by email + door-knock

    A quarterly neighborhood market report is a 2–4 page PDF showing the last 90 days of sales, average days on market, list-to-sale ratio, and one Middle Tennessee mortgage commentary paragraph from a Clarksville TN mortgage lender. Email it to the homeowners you have, and door-knock it to the ones you don’t. This works for two reasons: it’s genuinely useful, and it lets you stack a physical touch (the printed report) on top of a digital one (the email) without paying for postage on hundreds of homes who’d ignore it anyway.

    4. Demographic overlay on top of your geographic farm

    Demographic overlay farming is the practice of layering predictive data — equity, length of ownership, age, life-stage triggers, divorce, probate, military PCS status — on top of your geographic polygon. The math is the unlock: a 1,000-home traditional farm produces ~50 sales per year. Add overlays and the transactable subset can grow ~6x — meaning a $1,000/month farm budget that used to chase 50 sales now chases 300 (Brian Curtis 2025). For Clarksville TN realtors, the most powerful overlays are PCS to Fort Campbell rotations, military relocation Clarksville signals, and Nashville-area equity owners eyeing a move north into Montgomery County TN homes.

    5. Sphere + farm fusion through a quarterly community event

    Pick one Clarksville neighborhood event per quarter — a Fort Campbell-area food-truck night, a fall festival in Sango, a Christmas tree giveaway in Hilldale — and host it. Invite your sphere, invite the farm, and use a free home valuation Clarksville landing page as the RSVP. Event-driven farming converts higher than every other tactic because it stacks real-life relationship on top of a digital funnel. One event a quarter is enough; you don’t need monthly.

    Comparison: postcards vs. modern farming tactics

    Tactic Cost / home / month Speed to first listing Retargetable? Best paired with
    Traditional postcards only $0.60–$1.20 12–24 months No Just-sold + just-listed inserts
    Hyperlocal Meta retargeting $0.10–$0.40 3–9 months Yes Free home valuation funnel
    GBP + neighborhood SEO blog $0 hard cost + time 6–12 months Yes (via organic) Quarterly market reports
    Quarterly market reports $0.15–$0.30 4–9 months Partial (email) Door-knock or porch-drop
    Demographic overlay farm $1 (same budget, 6x audience) 6–12 months Yes Meta retargeting + CRM
    Quarterly community event $200–$800 per event 1–3 months Yes (RSVP capture) Sphere + free home valuation funnel

    How to launch your modern Clarksville farm in 7 steps

    1. Pick one farm area between 500–1,500 homes. Best candidates in Clarksville: Sango, St. Bethlehem, Hilldale, Rossview, and the Fort Campbell 4-mile catchment.
    2. Confirm the turnover rate is 5–7%+. Divide homes sold in the last 12 months by total homes. Below 5% means it’s not worth the effort.
    3. Add one demographic overlay. Equity > 40%, length of ownership > 7 years, or military relocation Clarksville signals if you’re farming near Fort Campbell.
    4. Build the digital base layer. Google Business Profile optimized, one neighborhood blog post live, and a free home valuation Clarksville landing page wired up. [INTERNAL LINK: free home valuation funnel for Clarksville realtors]
    5. Launch hyperlocal Meta retargeting against the farm polygon plus an LAL audience from your CRM. Start at $200–$400/month.
    6. Send a quarterly market report by email and door-knock the no-email portion of the farm with the same report.
    7. Host one community event in the first 90 days — this is what converts the farm from “marketing” to “neighbor.”

    Where does Fort Campbell, Nashville, and Middle Tennessee fit?

    Three Middle Tennessee dynamics make modern farming especially effective for a Clarksville real estate agent. PCS to Fort Campbell rotations produce predictable, demographic-overlay-friendly buyers and sellers every spring and summer. Nashville mortgage rates and Nashville real estate market affordability keep pushing buyers north into Montgomery County TN homes — a tailwind for any Clarksville farm. And the Clarksville housing market itself, with median pricing accessible to first-time homebuyer Clarksville VA, FHA, and USDA buyers, sustains 5–7%+ turnover in most of its established neighborhoods.

    Pair your farm with a Clarksville TN mortgage lender or Fort Campbell VA loan specialist who can co-host the events, co-brand the market report, and field the pre-approval calls from your free home valuation funnel. That partnership is what turns a digital farm into a closing-table machine. [INTERNAL LINK: pre-approval partnership for Clarksville realtors]

    FAQ: Geographic Farming in the Clarksville Housing Market

    What’s the ideal farm size for a Clarksville TN realtor?

    Between 500 and 1,500 homes, with a 5–7%+ turnover rate. Smaller farms convert faster; larger ones cost more and slow the timeline to your first listing. For Fort Campbell-area agents, a 1,000-home catchment is the typical sweet spot.

    How long until a geographic farm produces listings in Montgomery County?

    A traditional postcard-only farm takes 12–24 months to produce a first listing. A modern hybrid farm — retargeting + GBP + market reports + overlay — produces a first listing in 4–9 months in most Clarksville neighborhoods.

    Should I drop postcards entirely?

    No. Just-sold and just-listed postcards inside the farm still produce. But postcards should be 10–20% of the budget, not 100%. The lion’s share belongs to retargeting, content, and events.

    How do I overlay PCS to Fort Campbell signals on a farm?

    Layer DMA/data-provider lists for military households, BAH-supported renters, and recent PCS arrivals against your farm polygon. Then build creative around Fort Campbell home buying, PCS to Fort Campbell, and Fort Campbell VA loan specialist messaging. Conversion rates jump immediately.

    What’s a realistic 12-month ROI on a modern Clarksville farm?

    On a $12,000 annual budget against a 1,000-home farm with demographic overlay, coached agents are reporting 10–30 transactions in year two, with first-year ROI often 3–10x once events, GBP, and retargeting compound (Brian Curtis 2025).

    Can a brand-new Clarksville real estate agent run a farm this aggressive?

    Yes, but start with one 500-home farm, one Meta retargeting campaign, one quarterly market report, and one Clarksville TN mortgage lender partnership. Build the discipline before you scale the budget.

    The bottom line for Clarksville TN realtors

    Postcards aren’t dead — but as a standalone strategy in the 2026 Clarksville housing market, they’re losing to retargeting, content, market reports, demographic overlay, and community events. Build the modern farm, layer in PCS and Nashville commuter signals, and partner with a Clarksville TN mortgage lender who shows up to the events with you. That farm compounds. The postcard-only farm doesn’t.

    Written by Kate Matties-Deiboldt at The Blue Note Home — Licensed Mortgage Loan Originator, NMLS #18487, VanDyk Mortgage. Serving Clarksville, Fort Campbell, Montgomery County, Nashville, and Middle Tennessee real estate agents and buyers.

    {“@context”:”https://schema.org&#8221;,”@graph”:[{“@type”:”Article”,”@id”:”https://thedealdoctor.blog/geographic-farming-tactics-clarksville-realtors/#article&#8221;,”headline”:”5 Geographic Farming Tactics That Outperform Postcards in 2026 (Clarksville TN)”,”description”:”Five modern farming tactics that beat postcards on cost and conversion for Clarksville TN realtors near Fort Campbell and Montgomery County.”,”datePublished”:”2026-05-20″,”dateModified”:”2026-05-20″,”author”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”jobTitle”:”Licensed Mortgage Loan Originator (NMLS #18487)”,”worksFor”:{“@type”:”Organization”,”name”:”VanDyk Mortgage”}},”publisher”:{“@type”:”Organization”,”name”:”The Blue Note Home”,”url”:”https://thedealdoctor.blog&#8221;},”mainEntityOfPage”:”https://thedealdoctor.blog/geographic-farming-tactics-clarksville-realtors/&#8221;,”about”:[“Geographic farming”,”Real estate marketing”,”Clarksville housing market”,”Fort Campbell real estate”]},{“@type”:”FAQPage”,”@id”:”https://thedealdoctor.blog/geographic-farming-tactics-clarksville-realtors/#faq&#8221;,”mainEntity”:[{“@type”:”Question”,”name”:”What’s the ideal farm size for a Clarksville TN realtor?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Between 500 and 1,500 homes, with a 5-7%+ turnover rate. Smaller farms convert faster; larger ones cost more and slow the timeline to your first listing. For Fort Campbell-area agents, a 1,000-home catchment is the typical sweet spot.”}},{“@type”:”Question”,”name”:”How long until a geographic farm produces listings in Montgomery County?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”A traditional postcard-only farm takes 12-24 months to produce a first listing. A modern hybrid farm – retargeting + GBP + market reports + overlay – produces a first listing in 4-9 months in most Clarksville neighborhoods.”}},{“@type”:”Question”,”name”:”Should I drop postcards entirely?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”No. Just-sold and just-listed postcards inside the farm still produce. But postcards should be 10-20% of the budget, not 100%. The lion’s share belongs to retargeting, content, and events.”}},{“@type”:”Question”,”name”:”How do I overlay PCS to Fort Campbell signals on a farm?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Layer DMA/data-provider lists for military households, BAH-supported renters, and recent PCS arrivals against your farm polygon. Then build creative around Fort Campbell home buying, PCS to Fort Campbell, and Fort Campbell VA loan specialist messaging. Conversion rates jump immediately.”}},{“@type”:”Question”,”name”:”What’s a realistic 12-month ROI on a modern Clarksville farm?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”On a $12,000 annual budget against a 1,000-home farm with demographic overlay, coached agents are reporting 10-30 transactions in year two, with first-year ROI often 3-10x once events, GBP, and retargeting compound.”}},{“@type”:”Question”,”name”:”Can a brand-new Clarksville real estate agent run a farm this aggressive?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes, but start with one 500-home farm, one Meta retargeting campaign, one quarterly market report, and one Clarksville TN mortgage lender partnership. Build the discipline before you scale the budget.”}}]},{“@type”:”BreadcrumbList”,”itemListElement”:[{“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog&#8221;},{“@type”:”ListItem”,”position”:2,”name”:”For Realtors”,”item”:”https://thedealdoctor.blog/category/for-realtors/&#8221;},{“@type”:”ListItem”,”position”:3,”name”:”Geographic Farming Tactics”,”item”:”https://thedealdoctor.blog/geographic-farming-tactics-clarksville-realtors/&#8221;}]},{“@type”:”LocalBusiness”,”@id”:”https://thedealdoctor.blog/#localbusiness&#8221;,”name”:”The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,”description”:”Mortgage Loan Originator serving Clarksville, Fort Campbell, Nashville, and Middle Tennessee.”,”address”:{“@type”:”PostalAddress”,”addressLocality”:”Clarksville”,”addressRegion”:”TN”,”addressCountry”:”US”},”areaServed”:[“Clarksville TN”,”Fort Campbell”,”Montgomery County TN”,”Nashville TN”,”Middle Tennessee”,”Kentucky”],”founder”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”identifier”:”NMLS #18487″}},{“@type”:”ItemList”,”name”:”5 Geographic Farming Tactics That Outperform Postcards in 2026″,”itemListElement”:[{“@type”:”ListItem”,”position”:1,”name”:”Hyperlocal Facebook + Instagram retargeting around your farm polygon”},{“@type”:”ListItem”,”position”:2,”name”:”Google Business Profile + neighborhood-specific blog posts”},{“@type”:”ListItem”,”position”:3,”name”:”Quarterly neighborhood market reports delivered by email + door-knock”},{“@type”:”ListItem”,”position”:4,”name”:”Demographic overlay on top of your geographic farm”},{“@type”:”ListItem”,”position”:5,”name”:”Sphere + farm fusion through a quarterly community event”}]},{“@type”:”SpeakableSpecification”,”cssSelector”:[“.key-takeaways”,”h1″,”h1 + p”]}]}

  • Free Home Valuation Funnel for Clarksville TN Realtors

    A free home valuation funnel is the single highest-converting seller lead magnet available to a Clarksville real estate agent in 2026 — and most agents in Montgomery County are leaving it on the table. If you want listings, not just buyer leads, you need a dedicated landing page that turns curious Clarksville homeowners into named, contactable seller prospects within 90 seconds.

    This post lays out the exact funnel — landing page, follow-up cadence, lender partnership, and Clarksville-specific positioning — that converts cold “What’s my home worth?” curiosity into listing appointments across Clarksville, Fort Campbell, and Middle Tennessee.
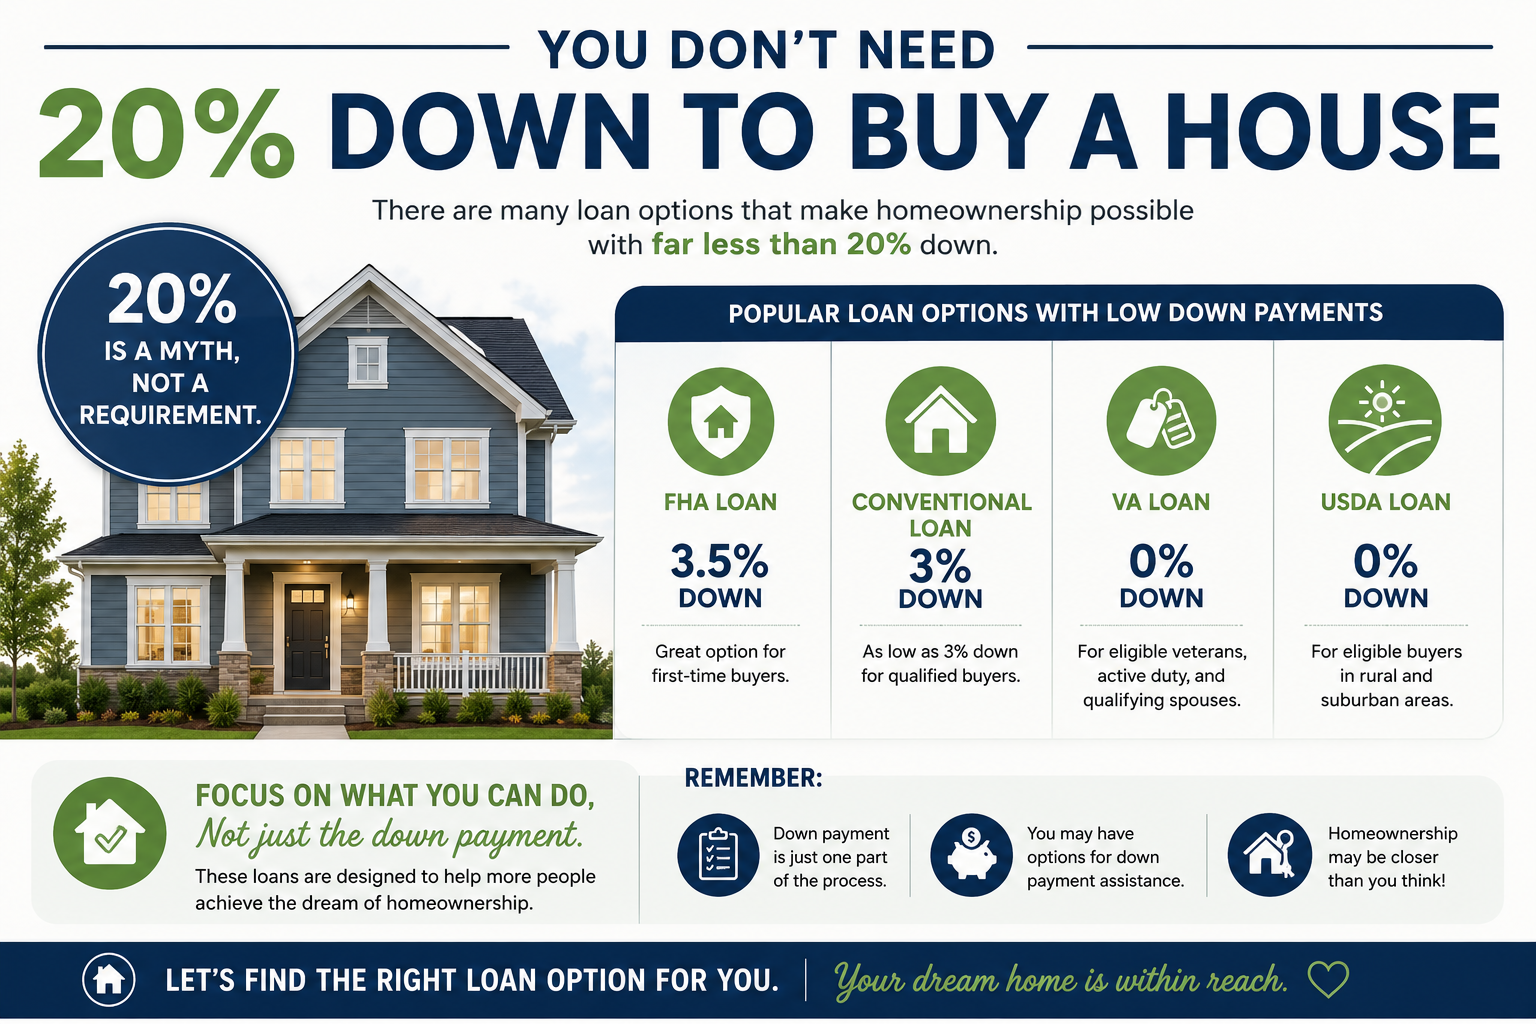
    TL;DR — Key Takeaways

    • Zillow’s own data shows Zestimates have a 1.83% median error on listed homes and 7.01% on off-market homes — meaning a $337K Clarksville home could be off by ~$23,500 (Zillow via Copper Key 2025). That gap is your opening.
    • The Clarksville housing market has ~2,200 homes for sale, a $337,900 median price, and 61 median days on market (Realtor.com 2026) — sellers need real human guidance, not just an AVM.
    • Free Home Valuation is rated the highest-converting seller lead magnet available, especially when paired with a fast follow-up CMA (OKZest 2025).
    • Across Tennessee, 61.8% of homes are now selling below list price (Norada 2025) — sellers need an accurate, agent-built CMA more than ever.
    • The funnel only works with speed: contact every lead inside 24 hours with a personalized, hand-built CMA referencing their actual address.

    What is a free home valuation funnel?

    A free home valuation funnel is a marketing system that converts a curious Clarksville homeowner into a named seller lead by offering an instant home value estimate in exchange for their contact information. It is built around one landing page, one automated valuation, and one fast, human follow-up. The funnel is the system; the valuation is the bait.

    For Clarksville TN realtors, this funnel matters because seller leads are 5–10x more profitable than buyer leads and because homeowners across Montgomery County are already searching “what’s my Clarksville home worth” every single day. The agent who shows up first — with a credible Clarksville-specific tool — captures that intent.

    Why this funnel works in the Clarksville housing market

    Three structural conditions in 2026 make this funnel especially powerful in Middle Tennessee:

    1. Zestimates are wrong enough to start a conversation. Zillow’s published median error rate is 1.83% for actively listed homes and 7.01% for off-market homes (Zillow via Copper Key 2025). On a $337,900 Clarksville home, that’s up to a $23,000 swing — enough to motivate a homeowner to ask a local Clarksville real estate agent for a real answer.

    2. The Clarksville market is shifting toward sellers who need real help. Realtor.com pegs Clarksville at $337,900 median price, ~2,200 active listings, and 61 median days on market (Realtor.com 2026). Statewide, 61.8% of Tennessee homes are now selling under list price (Norada 2025). Mispricing is brutal in this environment, and sellers know it.

    3. PCS cycles and Nashville commuters create constant seller flow. Every spring and summer, PCS to Fort Campbell rotations push hundreds of homeowners into the seller pool. Nashville real estate market churn pushes more. Military relocation Clarksville sellers, in particular, need a fast, professional valuation because their timeline is non-negotiable.

    The 5 components of a high-converting Clarksville home valuation funnel

    1. A dedicated landing page — not your homepage. URL like /clarksville-home-value or /whats-my-fort-campbell-home-worth. One headline, one form, one promise.
    2. An automated valuation (AVM) widget — Chime, Real Geeks, kvCORE, or a similar Clarksville TN mortgage lender-friendly tool that pulls MLS and county data.
    3. A fast, human CMA delivered in 24 hours — the automated number is the hook; the agent-built CMA is the value.
    4. A lender partnership built into the follow-up — a Clarksville TN mortgage lender who can run a buy/sell scenario, a payoff analysis, or a bridge plan for sellers buying next. [INTERNAL LINK: pre-approval partnership for Clarksville realtors]
    5. A multi-touch nurture sequence — quarterly Clarksville housing market updates, neighborhood comps, and a soft annual “want an updated valuation?” check-in.

    How to build the funnel in 7 steps

    1. Buy a clean landing-page URL. Use your existing domain with a short path like /clarksville-home-value. Short, keyword-first, hyphenated, lowercase.
    2. Write a single-promise headline. “What’s Your Clarksville TN Home Worth in 2026? Get an Instant Estimate + a Hand-Built CMA Within 24 Hours.” That headline does the conversion work.
    3. Install an AVM widget. Chime, Real Geeks, kvCORE, BoldTrail, and Sierra Interactive all offer Clarksville-ready AVMs. Pick one and configure it for Montgomery County, Stewart County, and Christian County KY (Fort Campbell catchment).
    4. Capture name, email, phone, and address — nothing else. Every extra field cuts conversion. Promise the AVM result via email and the CMA via text or call.
    5. Set up a 24-hour SLA on your CMA delivery. The agent who delivers a real CMA inside 24 hours wins the listing. Most don’t even try.
    6. Build the lender call into the workflow. Loop your Clarksville TN mortgage lender into the follow-up to run a payoff and net-sheet scenario for buy-and-sell sellers. This is how mortgage pre-approval Clarksville and listing conversion intersect. [INTERNAL LINK: building a lender referral network]
    7. Drive traffic from 4 sources, in order. Your sphere first (email blast), then Facebook/Instagram retargeting, then Google Business Profile, then paid Meta ads to a tight Montgomery County TN homes audience.

    Comparison: free home valuation vs. other seller lead magnets

    Lead magnet Conversion rate (warm) Seller intent signal Implementation effort Best for
    Free home valuation High (5–8% cold, 30%+ warm) Strongest — only sellers ask Moderate (AVM widget) Listing-focused agents
    Neighborhood market report Medium Medium — buyers + sellers High (recurring content) Hyperlocal authority builders
    Home seller prep checklist Medium Medium-high Low (one-time PDF) Long-runway seller nurture
    First-time buyer guide Medium None for sellers Moderate Buyer-focused niches
    ROI / investment calculator Lower volume, higher quality Investor sellers only High Investor-focused agents

    Positioning the funnel for Clarksville, Fort Campbell, and Nashville

    A generic “Home Value Estimate” page won’t beat Zillow on SEO. A Clarksville-specific page will. Your landing page headline, slug, meta description, and on-page copy should hit a focused cluster of local keywords: Clarksville housing market, Clarksville TN mortgage lender, Montgomery County TN homes, homes for sale near Fort Campbell, Nashville real estate market, Clarksville real estate agent, and Middle Tennessee mortgage. Lean into geo-specificity — that’s where you out-rank Zillow, Redfin, and Realtor.com in your micro-market.

    For Fort Campbell home buying clients who are about to PCS out, the funnel needs a second variant: a “Selling Before You PCS” landing page with a tighter timeline, military-friendly language, and a Fort Campbell VA loan specialist as the lender partner. Military relocation Clarksville sellers move on a 60–90 day window, and the funnel that respects that timeline wins them every time.

    FAQ: Free Home Valuation Funnels for Clarksville Realtors

    How many leads should a Clarksville home valuation landing page generate per month?

    A well-built funnel paired with consistent traffic (sphere + Facebook retargeting + Google Business Profile) should generate 15–40 named seller leads per month in the Clarksville housing market. Paid Meta ads to a tight Montgomery County TN audience can push that to 60+.

    Is an automated valuation accurate enough to send to a Clarksville homeowner?

    An AVM is accurate enough to start a conversation, not to price a listing. Zillow itself reports a 7% median error on off-market homes — that’s roughly $23,000 on a typical Clarksville home. Always position the AVM as the “instant estimate” and the agent-built CMA as the real answer.

    What’s the best lender partnership to plug into a seller valuation funnel?

    A Clarksville TN mortgage lender who can quickly run a payoff, a net-proceeds sheet, and a pre-approval for the seller’s next home. That dual capability — sell-side numbers + buy-side qualification — is what closes buy-and-sell sellers in Middle Tennessee.

    How fast should I follow up on a free home valuation lead?

    Inside 24 hours, ideally inside 4 hours. The Clarksville real estate agent who delivers a hand-built CMA within one business day captures the listing conversation before any competitor knows the lead exists.

    Will Fort Campbell PCS sellers really use a free valuation tool?

    Yes — and they convert faster than civilian sellers because their timeline is fixed. Build a dedicated “Selling Before You PCS from Fort Campbell” variant of the landing page and pair it with a Fort Campbell VA loan specialist who can pre-qualify them for their next-duty-station purchase.

    How does this funnel work with Nashville mortgage rates and Nashville real estate market traffic?

    Many Nashville-area homeowners are evaluating a move north to Clarksville and Montgomery County for affordability. A Clarksville home valuation funnel captures the sell-side of that move, while your Clarksville real estate agent brand captures the buy-side. The funnel turns Nashville market churn into Clarksville listings.

    The bottom line for Clarksville TN realtors

    The free home valuation funnel is the highest-leverage seller-lead system available in 2026 — and the Clarksville real estate agents who build it now will own the listing inventory of the Clarksville housing market for the next three years. Build the landing page, install the AVM, lock in your Clarksville TN mortgage lender for buy-and-sell scenarios, and commit to a 24-hour CMA SLA. Listings follow.

    Written by Kate Matties-Deiboldt at The Blue Note Home — Licensed Mortgage Loan Originator, NMLS #18487, VanDyk Mortgage. Serving sellers, first-time homebuyers, veterans, and PCS relocators across Clarksville, Fort Campbell, Montgomery County, and Middle Tennessee.
    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {“@type”: “Article”, “@id”: “https://thedealdoctor.blog/free-home-valuation-funnel-clarksville-realtors/#article&#8221;, “headline”: “Free Home Valuation Funnel for Clarksville TN Realtors”, “description”: “How Clarksville real estate agents turn ‘what’s my home worth’ curiosity into listing appointments — the full funnel, landing page, and follow-up cadence for 2026.”, “datePublished”: “2026-05-20”, “dateModified”: “2026-05-20”, “author”: {“@type”: “Person”, “name”: “Kate Matties-Deiboldt”, “jobTitle”: “Licensed Mortgage Loan Originator (NMLS #18487)”, “worksFor”: {“@type”: “Organization”, “name”: “VanDyk Mortgage”}}, “publisher”: {“@type”: “Organization”, “name”: “The Blue Note Home”, “url”: “https://thedealdoctor.blog&#8221;}, “mainEntityOfPage”: “https://thedealdoctor.blog/free-home-valuation-funnel-clarksville-realtors/&#8221;, “about”: [“Real estate lead generation”, “Home valuation funnel”, “Clarksville housing market”, “Seller lead magnets”]},
    {“@type”: “FAQPage”, “@id”: “https://thedealdoctor.blog/free-home-valuation-funnel-clarksville-realtors/#faq&#8221;, “mainEntity”: [
    {“@type”: “Question”, “name”: “How many leads should a Clarksville home valuation landing page generate per month?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “A well-built funnel paired with consistent traffic (sphere + Facebook retargeting + Google Business Profile) should generate 15-40 named seller leads per month in the Clarksville housing market. Paid Meta ads to a tight Montgomery County TN audience can push that to 60+.”}},
    {“@type”: “Question”, “name”: “Is an automated valuation accurate enough to send to a Clarksville homeowner?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “An AVM is accurate enough to start a conversation, not to price a listing. Zillow itself reports a 7% median error on off-market homes – that’s roughly $23,000 on a typical Clarksville home. Always position the AVM as the ‘instant estimate’ and the agent-built CMA as the real answer.”}},
    {“@type”: “Question”, “name”: “What’s the best lender partnership to plug into a seller valuation funnel?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “A Clarksville TN mortgage lender who can quickly run a payoff, a net-proceeds sheet, and a pre-approval for the seller’s next home. That dual capability – sell-side numbers + buy-side qualification – is what closes buy-and-sell sellers in Middle Tennessee.”}},
    {“@type”: “Question”, “name”: “How fast should I follow up on a free home valuation lead?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Inside 24 hours, ideally inside 4 hours. The Clarksville real estate agent who delivers a hand-built CMA within one business day captures the listing conversation before any competitor knows the lead exists.”}},
    {“@type”: “Question”, “name”: “Will Fort Campbell PCS sellers really use a free valuation tool?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Yes – and they convert faster than civilian sellers because their timeline is fixed. Build a dedicated ‘Selling Before You PCS from Fort Campbell’ variant of the landing page and pair it with a Fort Campbell VA loan specialist who can pre-qualify them for their next-duty-station purchase.”}},
    {“@type”: “Question”, “name”: “How does this funnel work with Nashville mortgage rates and Nashville real estate market traffic?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Many Nashville-area homeowners are evaluating a move north to Clarksville and Montgomery County for affordability. A Clarksville home valuation funnel captures the sell-side of that move, while your Clarksville real estate agent brand captures the buy-side. The funnel turns Nashville market churn into Clarksville listings.”}}
    ]},
    {“@type”: “BreadcrumbList”, “itemListElement”: [
    {“@type”: “ListItem”, “position”: 1, “name”: “Home”, “item”: “https://thedealdoctor.blog&#8221;},
    {“@type”: “ListItem”, “position”: 2, “name”: “For Realtors”, “item”: “https://thedealdoctor.blog/category/for-realtors/&#8221;},
    {“@type”: “ListItem”, “position”: 3, “name”: “Free Home Valuation Funnel”, “item”: “https://thedealdoctor.blog/free-home-valuation-funnel-clarksville-realtors/&#8221;}
    ]},
    {“@type”: “LocalBusiness”, “@id”: “https://thedealdoctor.blog/#localbusiness&#8221;, “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”, “description”: “Mortgage Loan Originator serving Clarksville, Fort Campbell, Nashville, and Middle Tennessee.”, “address”: {“@type”: “PostalAddress”, “addressLocality”: “Clarksville”, “addressRegion”: “TN”, “addressCountry”: “US”}, “areaServed”: [“Clarksville TN”, “Fort Campbell”, “Montgomery County TN”, “Nashville TN”, “Middle Tennessee”, “Kentucky”], “founder”: {“@type”: “Person”, “name”: “Kate Matties-Deiboldt”, “identifier”: “NMLS #18487”}},
    {“@type”: “HowTo”, “name”: “How to Build a Free Home Valuation Funnel as a Clarksville Real Estate Agent”, “step”: [
    {“@type”: “HowToStep”, “position”: 1, “name”: “Buy a clean landing-page URL”, “text”: “Use your existing domain with a short keyword-first path like /clarksville-home-value.”},
    {“@type”: “HowToStep”, “position”: 2, “name”: “Write a single-promise headline”, “text”: “Promise an instant estimate plus a hand-built CMA within 24 hours.”},
    {“@type”: “HowToStep”, “position”: 3, “name”: “Install an AVM widget”, “text”: “Configure Chime, Real Geeks, kvCORE, BoldTrail, or Sierra Interactive for Montgomery County and Fort Campbell catchment.”},
    {“@type”: “HowToStep”, “position”: 4, “name”: “Capture name, email, phone, and address only”, “text”: “Strip every other form field. Each extra field reduces conversion.”},
    {“@type”: “HowToStep”, “position”: 5, “name”: “Set a 24-hour CMA delivery SLA”, “text”: “Deliver a hand-built CMA within one business day to capture the listing conversation first.”},
    {“@type”: “HowToStep”, “position”: 6, “name”: “Build the lender call into the workflow”, “text”: “Loop in a Clarksville TN mortgage lender to run payoff and net-sheet scenarios for buy-and-sell sellers.”},
    {“@type”: “HowToStep”, “position”: 7, “name”: “Drive traffic from four sources in order”, “text”: “Sphere email, Facebook/Instagram retargeting, Google Business Profile, then paid Meta ads to a Montgomery County TN audience.”}
    ]},
    {“@type”: “SpeakableSpecification”, “cssSelector”: [“.key-takeaways”, “h1”, “h1 + p”]}
    ]
    }

  • Niche Down to Scale Up: Clarksville TN Realtor Playbook

    If you’re a Clarksville real estate agent trying to grow in 2026, niching down — not broadening out — is the fastest way to scale your business. The agents who dominate Middle Tennessee right now serve one buyer extremely well: a first-time homebuyer, a veteran using a VA loan, or a relocator PCSing to Fort Campbell. Picking a single audience and becoming the obvious expert for them is how you stand out in a saturated Montgomery County market.

    This post is written for Clarksville TN realtors who are tired of being a generalist and ready to build a focused, referable practice. As a Clarksville TN mortgage lender, I see firsthand which agents close the most files — and they almost always have a clearly defined niche.

    — Key Takeaways

    • First-time buyers fell to 21% of all home buyers in 2026, the lowest share NAR has tracked since 1981 — meaning the agents who specialize in them face less competition than ever (NAR 2026).
    • VA buyers are an enormous, underserved pool: in April 2026 alone, the VA guaranteed 50,771 loans totaling $23.8 billion (VA Home Loans, FY2026).
    • Fort Campbell sits ~13 miles from central Clarksville and feeds a steady stream of PCS relocators into Montgomery County every season.
    • Niching down means clearer marketing, faster referrals, and a lender partnership that actually performs.
    • Your niche should match your background, your warm sphere, and the buyers your local market actually has.

    Why niching down works in the Clarksville housing market

    A niche is a specific buyer or seller segment you build your brand, content, and lender partnerships around. Niching down is the practice of choosing that segment intentionally instead of taking every client who calls. The Clarksville housing market — with its mix of first-time buyers, Fort Campbell military families, and Nashville-area relocators — rewards agents who can speak fluently to one of those tribes.

    Here’s the math: when first-time buyer share hits a record low of 21%, generalist agents fight harder for fewer buyers. But the agents known as “the first-time homebuyer Clarksville expert” or the “Fort Campbell VA loan specialist’s go-to agent” attract those buyers before they ever shop around. Specialization is the cheapest marketing you’ll ever do.

    Which niche should a Clarksville real estate agent pick?

    There are three high-volume niches in Middle Tennessee that consistently outperform a generalist book. Each requires a different content strategy, lender relationship, and follow-up cadence.

    Niche 1: First-time homebuyers in Clarksville and Montgomery County

    A first-time homebuyer is anyone who hasn’t owned a primary residence in the past three years. They’re terrified, under-educated, and desperate for someone to translate the process. The median Clarksville home price sat near $337,900 in early 2026 (Realtor.com 2026), which keeps Montgomery County TN homes inside reach for FHA, USDA, and THDA programs that other Tennessee markets have priced out.

    If you pick this niche, you become the “no dumb questions” agent. Your content explains earnest money, closing costs, THDA first-time buyer down payment assistance, mortgage pre-approval Clarksville workflows, and how a Loan Estimate actually reads. [INTERNAL LINK: pre-approval partnership for Clarksville realtors]

    Niche 2: Veterans using VA loans near Fort Campbell

    VA loans Clarksville TN is one of the most lucrative niches in the country — and one of the least well served. A VA loan is a zero-down, no-PMI mortgage backed by the Department of Veterans Affairs and available to qualifying active-duty, veteran, and surviving-spouse borrowers. With 25,282 VA purchase loans guaranteed in April 2026 alone (VA Home Loans, FY2026), the demand is structural, not seasonal.

    If you serve this niche, you need a Fort Campbell VA loan specialist on speed dial. You need to know the difference between entitlement, the funding fee, and a VA appraisal Tie-In. You need to understand that BAH (Basic Allowance for Housing) counts as qualifying income. Most generalist agents lose VA buyers in the first conversation. Specialists win them in the first five minutes.

    Niche 3: Military relocators PCSing to Fort Campbell

    A PCS to Fort Campbell — Permanent Change of Station — moves thousands of soldiers and families through the Clarksville and Oak Grove housing markets every year. Fort Campbell sits roughly 13 miles from central Clarksville with typical commutes of 20–35 minutes (Scott Zeller Homes 2026). Military relocation Clarksville buyers need agents who understand PCS timelines, virtual showings, and homes for sale near Fort Campbell by gate proximity, not just by ZIP code.

    If you choose this niche, your funnel is built around relocation content, virtual tours, and a tight referral loop with on-post sponsors. [INTERNAL LINK: move-to-Clarksville relocation funnel for PCS buyers]

    Comparison: which niche fits which agent?

    Niche Best for agents who… Average price point Lender partner type Lead source
    First-time homebuyer Clarksville Love teaching, patient, strong on social media $250K–$340K FHA/USDA/THDA specialist Buyer seminars, Instagram, Facebook groups
    VA loans Clarksville TN Are veterans themselves or military-adjacent $300K–$450K Fort Campbell VA loan specialist Base referrals, MIL/VET groups, Google search
    PCS to Fort Campbell relocators Communicate well over Zoom, fast responders $300K–$425K VA + conventional dual-licensed lender Sponsor referrals, relocation companies, YouTube

    How to niche down in 5 steps

    1. Pick the niche that matches your real life. If you’re a military spouse, the PCS-to-Fort-Campbell niche is yours. If you bought your first home three years ago and remember the panic, first-time buyers is your tribe. Authenticity scales; pretending doesn’t.
    2. Audit your last 20 transactions. Which buyers were the easiest, most referable, and most profitable? That pattern is your data — let it pick the niche for you.
    3. Build a content engine around one keyword cluster. Pick 6–10 local keywords like “first-time homebuyer Clarksville,” “Fort Campbell home buying,” “PCS to Fort Campbell,” “VA loan eligibility Tennessee,” and write to those weekly. Specialists rank; generalists don’t.
    4. Lock in a lender partnership that mirrors your niche. A Clarksville TN mortgage lender who closes 80% VA loans is a force multiplier for a VA-focused agent. A lender who lives THDA and first-time-buyer programs is the right partner for the first-time niche. [INTERNAL LINK: building a lender referral network]
    5. Rebrand your bio, headshot, and website above the fold. Within seven words, a visitor should know exactly who you serve. “Clarksville TN Realtor for PCS Military Families” beats “Top-Producing Clarksville Real Estate Agent” every time.

    What if my niche is too small for Clarksville?

    It almost never is. Clarksville and Montgomery County TN are anchored by Fort Campbell, the 101st Airborne, and a steady flow of Nashville commuters. Even a hyper-specific niche — “VA buyers building new construction in Sango” or “first-time buyers using THDA in St. Bethlehem” — produces enough volume in Middle Tennessee to fill a calendar. Nashville mortgage rates and Nashville real estate market dynamics also pull cross-county buyers into Clarksville every spring, expanding your relocator pool naturally.

    If you’re worried about leaving money on the table by saying no to off-niche leads, refer them out. A referral fee from a fellow Clarksville real estate agent is faster, cleaner income than stretching outside your lane.

    How to market your niche without sounding like everyone else

    Niche marketing is the practice of speaking directly to one buyer persona in language they recognize. For first-time buyers in Clarksville, that means TikTok and Instagram Reels with on-screen captions about earnest money, THDA, and buying a home in Nashville vs. Clarksville. For Fort Campbell VA buyers, it means YouTube walkthroughs that mention gate distances, BAH, and funding fees by name. For PCS relocators, it’s a Zoom-friendly listing-tour workflow and a relocation packet branded for Montgomery County TN homes.

    Two more disciplines separate the niche specialist from the generalist: response speed and lender alignment. Buyers in 2026 expect a reply in minutes, not hours, and they expect their agent and lender to communicate like one team. If you nail those two — fast response, tight lender partnership — your niche will compound on itself through referrals.

    FAQ: Niching Down as a Clarksville Real Estate Agent

    Is it risky to niche down to just first-time homebuyers in Clarksville?

    No. With first-time buyers at a record-low 21% nationally, the agents who own that niche locally face less competition and capture a disproportionate share of the buyers who are in the market. First-time homebuyer Clarksville is one of the strongest niches in Middle Tennessee.

    How do I become a Fort Campbell VA loan specialist’s referral partner?

    Start by asking three Clarksville TN mortgage lenders who their top three VA-focused agents are, then ask why. Build your VA content, attend an on-post real estate brief, and offer to co-host a VA homebuyer workshop. Lenders refer agents who make their job easier.

    How long does it take to dominate a niche in the Clarksville housing market?

    Most agents see meaningful traction within 6–12 months of consistent niche-focused content, paired with one referral partnership (lender, sponsor, or relocation company). Two years of focus typically produces market recognition.

    Can I serve two niches at once — for example, first-time buyers and VA buyers?

    Yes, but only if they overlap naturally. First-time homebuyer + VA buyer is a strong combination because many junior enlisted are buying their first home with a VA loan. PCS-to-Fort-Campbell relocators and VA buyers also overlap heavily. Pairing unrelated niches (luxury + first-time) usually dilutes both.

    What’s the best lender partnership for a Clarksville real estate agent niching into VA loans?

    Look for a Clarksville TN mortgage lender who closes a high volume of VA loans specifically, understands BAH and entitlement, and serves Fort Campbell home buying clients regularly. A dedicated Fort Campbell VA loan specialist will close faster, communicate more clearly with the buyer’s command, and protect your transaction.

    How does niching down affect my Nashville real estate market opportunities?

    Niching down in Clarksville actually expands your Nashville opportunities through referrals. As Nashville mortgage rates and pricing push buyers north into Montgomery County, Nashville agents will refer their priced-out clients to the Clarksville specialist they trust. Niche specialists become the obvious referral partner.

    The bottom line for Clarksville TN realtors

    Scaling a real estate business in Middle Tennessee in 2026 is not about being everything to everyone — it’s about being the obvious answer for one buyer. First-time buyers, VA buyers, and Fort Campbell relocators are three of the highest-volume, lowest-competition niches in the country, and they all live in your backyard. Pick one, partner with the right lender, and let the niche compound.

    Written by Kate Matties-Deiboldt at The Blue Note Home — Licensed Mortgage Loan Originator, NMLS #18487, VanDyk Mortgage. Serving first-time homebuyers, veterans, and PCS relocators across Clarksville, Fort Campbell, Montgomery County, and Middle Tennessee.
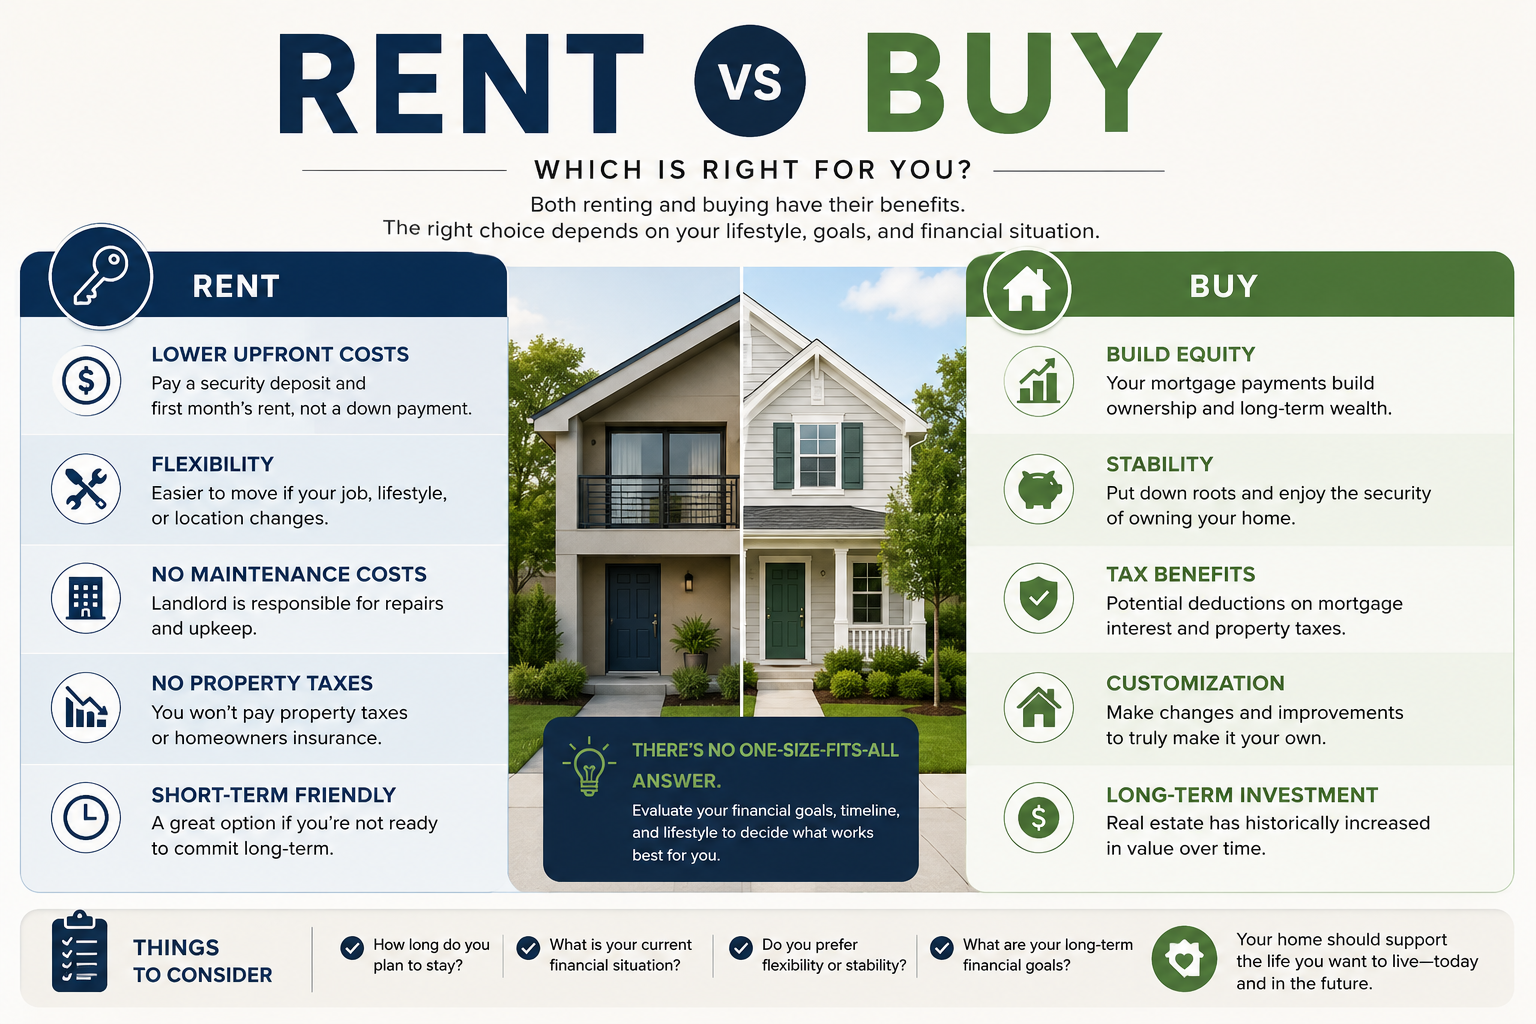
    {
    “@context”: “https://schema.org&#8221;,
    “@graph”: [
    {
    “@type”: “Article”,
    “@id”: “https://thedealdoctor.blog/niche-down-clarksville-realtors-first-time-va-pcs/#article&#8221;,
    “headline”: “Niche Down to Scale Up: Clarksville TN Realtor Playbook”,
    “description”: “First-time buyers, VA buyers, and Fort Campbell relocators are the three highest-ROI niches for Clarksville real estate agents in 2026.”,
    “datePublished”: “2026-05-19”,
    “dateModified”: “2026-05-19”,
    “author”: {“@type”: “Person”, “name”: “Kate Matties-Deiboldt”, “jobTitle”: “Licensed Mortgage Loan Originator (NMLS #18487)”, “worksFor”: {“@type”: “Organization”, “name”: “VanDyk Mortgage”}},
    “publisher”: {“@type”: “Organization”, “name”: “The Blue Note Home”, “url”: “https://thedealdoctor.blog&#8221;},
    “mainEntityOfPage”: “https://thedealdoctor.blog/niche-down-clarksville-realtors-first-time-va-pcs/&#8221;,
    “about”: [“Real estate niche marketing”, “First-time homebuyer Clarksville”, “VA loans Clarksville TN”, “PCS to Fort Campbell”]
    },
    {
    “@type”: “FAQPage”,
    “@id”: “https://thedealdoctor.blog/niche-down-clarksville-realtors-first-time-va-pcs/#faq&#8221;,
    “mainEntity”: [
    {“@type”: “Question”, “name”: “Is it risky to niche down to just first-time homebuyers in Clarksville?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “No. With first-time buyers at a record-low 21% nationally, the agents who own that niche locally face less competition and capture a disproportionate share of the buyers who are in the market. First-time homebuyer Clarksville is one of the strongest niches in Middle Tennessee.”}},
    {“@type”: “Question”, “name”: “How do I become a Fort Campbell VA loan specialist’s referral partner?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Start by asking three Clarksville TN mortgage lenders who their top three VA-focused agents are, then ask why. Build your VA content, attend an on-post real estate brief, and offer to co-host a VA homebuyer workshop. Lenders refer agents who make their job easier.”}},
    {“@type”: “Question”, “name”: “How long does it take to dominate a niche in the Clarksville housing market?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Most agents see meaningful traction within 6-12 months of consistent niche-focused content, paired with one referral partnership (lender, sponsor, or relocation company). Two years of focus typically produces market recognition.”}},
    {“@type”: “Question”, “name”: “Can I serve two niches at once – for example, first-time buyers and VA buyers?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Yes, but only if they overlap naturally. First-time homebuyer + VA buyer is a strong combination because many junior enlisted are buying their first home with a VA loan. PCS-to-Fort-Campbell relocators and VA buyers also overlap heavily. Pairing unrelated niches (luxury + first-time) usually dilutes both.”}},
    {“@type”: “Question”, “name”: “What’s the best lender partnership for a Clarksville real estate agent niching into VA loans?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Look for a Clarksville TN mortgage lender who closes a high volume of VA loans specifically, understands BAH and entitlement, and serves Fort Campbell home buying clients regularly. A dedicated Fort Campbell VA loan specialist will close faster, communicate more clearly with the buyer’s command, and protect your transaction.”}},
    {“@type”: “Question”, “name”: “How does niching down affect my Nashville real estate market opportunities?”, “acceptedAnswer”: {“@type”: “Answer”, “text”: “Niching down in Clarksville actually expands your Nashville opportunities through referrals. As Nashville mortgage rates and pricing push buyers north into Montgomery County, Nashville agents will refer their priced-out clients to the Clarksville specialist they trust. Niche specialists become the obvious referral partner.”}}
    ]
    },
    {
    “@type”: “BreadcrumbList”,
    “itemListElement”: [
    {“@type”: “ListItem”, “position”: 1, “name”: “Home”, “item”: “https://thedealdoctor.blog&#8221;},
    {“@type”: “ListItem”, “position”: 2, “name”: “For Realtors”, “item”: “https://thedealdoctor.blog/category/for-realtors/&#8221;},
    {“@type”: “ListItem”, “position”: 3, “name”: “Niche Down to Scale Up”, “item”: “https://thedealdoctor.blog/niche-down-clarksville-realtors-first-time-va-pcs/&#8221;}
    ]
    },
    {
    “@type”: “LocalBusiness”,
    “@id”: “https://thedealdoctor.blog/#localbusiness&#8221;,
    “name”: “The Blue Note Home — Kate Matties-Deiboldt, VanDyk Mortgage”,
    “description”: “Mortgage Loan Originator serving Clarksville, Fort Campbell, Nashville, and Middle Tennessee.”,
    “address”: {“@type”: “PostalAddress”, “addressLocality”: “Clarksville”, “addressRegion”: “TN”, “addressCountry”: “US”},
    “areaServed”: [“Clarksville TN”, “Fort Campbell”, “Montgomery County TN”, “Nashville TN”, “Middle Tennessee”, “Kentucky”],
    “founder”: {“@type”: “Person”, “name”: “Kate Matties-Deiboldt”, “identifier”: “NMLS #18487”}
    },
    {
    “@type”: “HowTo”,
    “name”: “How to Niche Down as a Clarksville Real Estate Agent”,
    “step”: [
    {“@type”: “HowToStep”, “position”: 1, “name”: “Pick the niche that matches your real life”, “text”: “Choose a niche based on your authentic background and warm sphere.”},
    {“@type”: “HowToStep”, “position”: 2, “name”: “Audit your last 20 transactions”, “text”: “Identify the buyer type that was easiest, most referable, and most profitable.”},
    {“@type”: “HowToStep”, “position”: 3, “name”: “Build a content engine around one keyword cluster”, “text”: “Write weekly to 6-10 local keywords tied to your niche.”},
    {“@type”: “HowToStep”, “position”: 4, “name”: “Lock in a lender partnership that mirrors your niche”, “text”: “Partner with a Clarksville TN mortgage lender whose loan mix matches your buyer type.”},
    {“@type”: “HowToStep”, “position”: 5, “name”: “Rebrand your bio, headshot, and website above the fold”, “text”: “Make your niche obvious within seven words on every public-facing surface.”}
    ]
    },
    {
    “@type”: “SpeakableSpecification”,
    “cssSelector”: [“.key-takeaways”, “h1”, “h1 + p”]
    }
    ]
    }

  • Pre-Approval Partnership for Clarksville TN Realtors (2026)

    Pre-Approval Partnership for Clarksville TN Realtors (2026)

    A Clarksville real estate agent who co-markets with one dedicated, local mortgage partner generates roughly twice the qualified lead flow of an agent who refers buyers to whichever lender they bump into. The reason is simple: in 2026, every serious buyer needs a real pre-approval before sellers will even look at their offer, and the agent who hands buyers a same-day Fort Campbell VA loan specialist closes more deals than the agent who hands them a Google search. According to NAR (2025), first-time buyers now make up just 21% of the market and the median down payment is 19% — every dollar of financing matters, and a strong mortgage pre-approval Clarksville conversation up front is what unlocks the offer.

    Key Takeaways

    • First-time homebuyer Clarksville leads close 2–3x more often when the agent introduces a Clarksville TN mortgage lender by day 2 of the conversation, not week 2.
    • First-time buyers are now just 21% of the market, the lowest share since 1981 (NAR, 2025) — every qualified lead is more valuable than ever.
    • Recent buyers typically paid 99% of asking price (NAR 2025 Profile, PDF) — competitive offers require ironclad pre-approval, not pre-qualification.
    • Clarksville sold prices in spring 2026 ran $308,000–$325,000, with median listing around $345,000 and 48 days on market (Chord Real Estate, 2026).
    • Co-marketing is legal — but only when each party pays fair market value for their share of the marketing (Forvis Mazars on RESPA Section 8, 2025).
    • Build one partnership, document it, and run the 6-piece co-marketing system below for 12 months.

    What Is a Pre-Approval Partnership?

    A pre-approval partnership is a formal, RESPA-compliant co-marketing relationship between a Clarksville real estate agent and one local mortgage loan originator in which both parties share the cost of marketing pieces that promote both businesses to a defined audience. Done right, it produces faster pre-approvals, stronger offers, and shared lead capture — without violating the Real Estate Settlement Procedures Act (RESPA). Done wrong, it triggers CFPB and state regulator scrutiny that ends careers.

    The legal line: RESPA Section 8 prohibits giving or accepting a ‘thing of value’ in exchange for the referral of settlement-service business. Co-marketing is allowed when each party pays the fair market value of their share of the promotion and the materials promote both parties roughly equally (Forvis Mazars, 2025). A 50/50 sponsored Facebook ad? Fine. A lender paying 100% for the agent’s billboard with a tiny lender logo in the corner? Not fine.

    Why Co-Marketing Outperforms Solo Marketing in the Clarksville Housing Market

    The Clarksville housing market in 2026 is balanced but competitive — 48 median days on market, sale-to-list ratios near 100%, and median sold prices around $308,000–$325,000 (Chord Real Estate, 2026). In that environment, three buyer pools dominate lead flow:

    • Veterans and active-duty using VA loans Clarksville TN — they need a Fort Campbell VA loan specialist who understands BAH, COE, and entitlement, not a generic call-center lender.
    • First-time homebuyer Clarksville leads — many are THDA first-time buyer candidates or USDA loans Tennessee eligible, and they need education before they need a showing.
    • Out-of-state relocators and PCS to Fort Campbell families — they are buying a city sight-unseen and need a tight realtor-lender team to make decisions remotely.

    One Clarksville TN realtor + one Clarksville TN mortgage lender split the cost of reaching all three pools. The agent gets warm, pre-approved leads. The lender gets contract-stage referrals. Both names appear on every door hanger, social ad, open house sign-in, and homebuyer workshop flyer in your patch.

    The 6-Piece Co-Marketing System

    Piece 1 — The Joint Branded Pre-Approval Workshop

    One night a month at the Clarksville-Montgomery County Public Library or a community room. Free to attend. Agent talks about the Clarksville housing market, what homes cost in Sango vs. Hampton Station, what to expect from inspections and offers. Lender talks about pre-qualified vs. pre-approved vs. underwritten, FHA vs. VA vs. USDA vs. conventional, and walks through real numbers on a $310,000 home. Both names on every flyer, every Facebook event, every follow-up email. Cost is split 50/50.

    Piece 2 — The Co-Branded Open House Sign-In

    QR code at the door routes to a landing page with both your photos and a single form: name, phone, are you working with a lender. The visitor leaves having met (digitally) both of you. Within 60 seconds of sign-in, the lender sends a soft ‘If you want to talk numbers this week, I can do a 10-minute call’ text. [INTERNAL LINK: Open House Follow-Up Sequences for Clarksville Realtors]

    Piece 3 — The 50/50 Social Ad Set

    Run a Facebook/Instagram ad targeting Montgomery County TN homes searches, military relocation Clarksville keywords, and ‘first-time homebuyer Clarksville’ lookalikes. Both names, both photos, both NMLS / license numbers in the creative. Both pay 50% of spend. Document the invoice split. This is the most common co-marketing piece — and the easiest to keep RESPA-clean.

    Piece 4 — The Monthly Co-Branded Newsletter

    One email per month to a shared list of past clients, current leads, and workshop attendees. Half the email is agent content (Clarksville housing market update, Montgomery County TN homes inventory, a featured listing). Half is lender content (rate snapshot, a VA loan eligibility Tennessee tip, a buyer FAQ). One CTA each. Both logos in the header.

    Piece 5 — The Joint Listing Presentation Page

    When the realtor goes on a listing appointment, the deck includes a page co-branded with the lender that says: ‘Every buyer who tours this home will be encouraged to get pre-approved with our trusted local lender — meaning faster, cleaner offers and fewer contract failures.’ Sellers love it. It positions both parties as a team.

    Piece 6 — The Co-Hosted Property Tour Video

    Once a month, film a 3–5 minute video where the agent walks a home and the lender pops in for 30 seconds with the payment breakdown: ‘At today’s Nashville mortgage rates, this $329,000 home with 5% down runs about $2,180/month including taxes and insurance — and if you’re VA eligible, zero down and no PMI.’ Post to YouTube, Reels, TikTok, Facebook. Tag the listing.

    RESPA-Compliant vs. Risky: A Side-by-Side

    Co-Marketing Element RESPA-Compliant Approach Risky / Likely Violation
    Ad spend split 50/50 with documented invoices Lender pays 100%, agent gets prime placement
    Branding Both names, photos, and license numbers equally visible Tiny lender logo in corner of agent’s flyer
    Audience targeting Broad consumer audience (homebuyers, PCS families, Sango residents) Only the agent’s past clients
    Referrals No promise to refer business in exchange for marketing ‘In exchange for sponsoring this, send me your VA buyers’
    Documentation Written co-marketing agreement, fair market value justification Verbal handshake, no paper trail
    Lead routing Each lead chooses freely; no auto-assigned referrals All workshop attendees are automatically registered with the lender

    If anything in the right column describes your current setup, fix it this week. The CFPB has issued multiple seven-figure RESPA penalties since 2023, and 2025 enforcement guidance from Forvis Mazars (2025) makes clear the agency is still active.

    How to Pick the Right Lender Partner

    One partner. Not five. A Clarksville TN realtor with five ‘preferred’ lenders has zero — buyers can tell. Pick a Clarksville TN mortgage lender who meets all of the following:

    1. Licensed in Tennessee (and ideally Kentucky for Fort Campbell crossover) with a clean NMLS record.
    2. Specializes in or actively closes VA loans Clarksville TN, FHA, USDA loans Tennessee, and conventional — not just one product.
    3. Responds to texts within 15 minutes during business hours.
    4. Will sit at your open houses and host workshops without being asked twice.
    5. Can issue a real pre-approval (credit pulled, income documented, AUS run) within 24 hours.
    6. Carries E&O, signs a written co-marketing agreement, and tracks shared marketing spend.

    For Clarksville TN realtors working veteran and military relocation Clarksville buyers, the right partner is a Fort Campbell VA loan specialist who actually understands BAH, deployment timelines, and PCS orders. [INTERNAL LINK: VA Loans Demystified for Realtors]

    The Bottom Line for Clarksville TN Realtors

    Co-marketing is not a hack. It is a 12-month commitment to one lender partner, a monthly workshop, a shared ad budget, and a documented compliance file. The Clarksville TN realtors at the top of every Montgomery County TN homes search result and every ‘Clarksville real estate agent’ recommendation thread are not lucky — they are running this exact system with a single lender, in lockstep, every month. At The Blue Note Home, we build these partnerships for Middle Tennessee mortgage and real estate pros who want to stop competing on price and start winning on team strength.

    FAQ — Lender Co-Marketing for Clarksville Realtors

    Is realtor-lender co-marketing legal in Tennessee?

    Yes, when structured correctly. RESPA Section 8 allows co-marketing as long as each party pays fair market value for their share of the promotion and the materials promote both parties roughly equally. Referral kickbacks for settlement-service business are prohibited (Forvis Mazars, 2025).

    How much should a Clarksville lender and realtor each spend?

    Most active Clarksville TN realtor / lender partnerships split $400–$1,500 per month across ads, workshops, printed materials, and shared software. The exact split is less important than documenting that each party pays for their proportional share.

    Can my lender pay for my CRM, signs, or business cards?

    No. RESPA prohibits a lender from paying for materials that primarily promote the realtor without proportional benefit to the lender. Shared materials with equal branding are fine; gifts and one-sided marketing are not.

    What’s the difference between pre-qualified and pre-approved in Clarksville?

    Pre-qualified is an informal estimate of how much a buyer might borrow (Realtor.com, 2025). Pre-approved means the lender has pulled credit, verified income, run automated underwriting, and issued a written commitment. In the Clarksville housing market, sellers expect pre-approval before they will counter-offer. [INTERNAL LINK: Pre-Qualified vs. Pre-Approved vs. Underwritten]

    How fast can a buyer get pre-approved through a Fort Campbell VA loan specialist?

    A real pre-approval — credit pulled, income documented, AUS approval — can usually be issued within 24 hours, often same-day for organized borrowers. VA loan eligibility Tennessee documentation (DD-214 or Statement of Service) is the most common bottleneck for first-time veteran buyers.

    Should I have one lender partner or several?

    One primary partner produces the deepest co-marketing benefit. If buyers ask for options, you can always recommend a backup lender — but spreading co-marketing dollars across multiple lenders dilutes the partnership and creates RESPA complications around proportional benefit.


    About the author: Kate Matties-Deiboldt (NMLS #18487) is a licensed mortgage loan originator with VanDyk Mortgage based in Clarksville, TN, specializing in VA loans, FHA, USDA, and first-time homebuyer programs across Middle Tennessee and Kentucky. She publishes at The Blue Note Home.

    {“@context”:”https://schema.org&#8221;,”@graph”:[{“@type”:”Article”,”@id”:”https://thedealdoctor.blog/pre-approval-partnership-clarksville-realtors/#article&#8221;,”headline”:”Pre-Approval Partnership for Clarksville TN Realtors (2026)”,”description”:”How Clarksville TN realtors co-market with a Fort Campbell VA loan specialist to double lead flow — a step-by-step, RESPA-compliant 2026 playbook.”,”image”:”https://thedealdoctor.blog/wp-content/uploads/2026/05/pre-approval-partnership-clarksville.jpg&#8221;,”datePublished”:”2026-05-18″,”dateModified”:”2026-05-18″,”author”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”jobTitle”:”Mortgage Loan Originator (NMLS #18487)”,”worksFor”:{“@type”:”Organization”,”name”:”VanDyk Mortgage”},”url”:”https://thedealdoctor.blog/about&#8221;},”publisher”:{“@type”:”Organization”,”@id”:”https://thedealdoctor.blog/#org&#8221;,”name”:”The Blue Note Home”,”logo”:{“@type”:”ImageObject”,”url”:”https://thedealdoctor.blog/wp-content/uploads/logo.png&#8221;}},”mainEntityOfPage”:{“@type”:”WebPage”,”@id”:”https://thedealdoctor.blog/pre-approval-partnership-clarksville-realtors/&#8221;},”keywords”:”Clarksville real estate agent, Clarksville TN mortgage lender, Fort Campbell VA loan specialist, mortgage pre-approval Clarksville, VA loans Clarksville TN, first-time homebuyer Clarksville, Middle Tennessee mortgage, Clarksville housing market, Montgomery County TN homes, VA loan eligibility Tennessee, military relocation Clarksville”},{“@type”:”FAQPage”,”mainEntity”:[{“@type”:”Question”,”name”:”Is realtor-lender co-marketing legal in Tennessee?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes, when structured correctly. RESPA Section 8 allows co-marketing as long as each party pays fair market value for their share of the promotion and the materials promote both parties roughly equally. Referral kickbacks for settlement-service business are prohibited.”}},{“@type”:”Question”,”name”:”How much should a Clarksville lender and realtor each spend?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Most active Clarksville TN realtor and lender partnerships split $400-$1,500 per month across ads, workshops, printed materials, and shared software. The exact split is less important than documenting that each party pays for their proportional share.”}},{“@type”:”Question”,”name”:”Can my lender pay for my CRM, signs, or business cards?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”No. RESPA prohibits a lender from paying for materials that primarily promote the realtor without proportional benefit to the lender.”}},{“@type”:”Question”,”name”:”What is the difference between pre-qualified and pre-approved in Clarksville?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Pre-qualified is an informal estimate. Pre-approved means the lender has pulled credit, verified income, run automated underwriting, and issued a written commitment.”}},{“@type”:”Question”,”name”:”How fast can a buyer get pre-approved through a Fort Campbell VA loan specialist?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”A real pre-approval can usually be issued within 24 hours, often same-day for organized borrowers. VA loan eligibility Tennessee documentation is the most common bottleneck.”}},{“@type”:”Question”,”name”:”Should I have one lender partner or several?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”One primary partner produces the deepest co-marketing benefit. Spreading dollars across multiple lenders creates RESPA complications.”}}]},{“@type”:”BreadcrumbList”,”itemListElement”:[{“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog/&#8221;},{“@type”:”ListItem”,”position”:2,”name”:”Marketing Tips”,”item”:”https://thedealdoctor.blog/category/marketing-tips/&#8221;},{“@type”:”ListItem”,”position”:3,”name”:”Pre-Approval Partnership”}]},{“@type”:”LocalBusiness”,”@id”:”https://thedealdoctor.blog/#localbusiness&#8221;,”name”:”The Blue Note Home – Kate Matties-Deiboldt, Mortgage Loan Officer”,”description”:”VA loan specialist and mortgage loan originator serving Clarksville TN, Fort Campbell KY, and Middle Tennessee. NMLS #18487.”,”image”:”https://thedealdoctor.blog/wp-content/uploads/logo.png&#8221;,”url”:”https://thedealdoctor.blog&#8221;,”areaServed”:[“Clarksville, TN”,”Fort Campbell, KY”,”Nashville, TN”,”Montgomery County, TN”,”Middle Tennessee”],”address”:{“@type”:”PostalAddress”,”addressLocality”:”Clarksville”,”addressRegion”:”TN”,”addressCountry”:”US”},”founder”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”}},{“@type”:”HowTo”,”name”:”How to Build a RESPA-Compliant Pre-Approval Partnership”,”description”:”A 6-piece co-marketing system for Clarksville TN realtors.”,”step”:[{“@type”:”HowToStep”,”position”:1,”name”:”Joint Branded Pre-Approval Workshop”,”text”:”Host a monthly free workshop at the library with agent and lender content; split costs 50/50.”},{“@type”:”HowToStep”,”position”:2,”name”:”Co-Branded Open House Sign-In”,”text”:”Use a QR code routing to a co-branded landing page; lender sends 60-second follow-up text.”},{“@type”:”HowToStep”,”position”:3,”name”:”50/50 Social Ad Set”,”text”:”Run targeted Facebook/Instagram ads with both names and license numbers; split spend 50/50 with documented invoices.”},{“@type”:”HowToStep”,”position”:4,”name”:”Monthly Co-Branded Newsletter”,”text”:”Send a shared monthly email — half agent market content, half lender rate and program content.”},{“@type”:”HowToStep”,”position”:5,”name”:”Joint Listing Presentation Page”,”text”:”Add a co-branded page to the listing deck positioning realtor and lender as a team.”},{“@type”:”HowToStep”,”position”:6,”name”:”Co-Hosted Property Tour Video”,”text”:”Film a monthly walkthrough where the lender provides a 30-second payment breakdown at current rates.”}]},{“@type”:”SpeakableSpecification”,”cssSelector”:[“.key-takeaways”,”h1 + p”]}]}

  • Open House Follow-Up Sequences for Clarksville Realtors

    Open House Follow-Up Sequences for Clarksville Realtors

    The single biggest reason open house visitors never become clients is slow, generic follow-up — not bad open houses. Clarksville real estate agents who reach a visitor within five minutes and then run a structured 7-touch sequence over the next 30 days convert dramatically more buyers than agents who blast a single ‘nice to meet you’ email and hope for the best. According to NAR research (2025) summarized by Goliath Data, responding to a new lead within 60 seconds converts 55% more appointments than responding at five minutes — and after 30 minutes, appointment-set rates collapse to under 4% (Swiftleads AI, 2026).

    Key Takeaways

    • Voice contact within 60 seconds converts 27.1% of leads to booked appointments; at 30+ minutes it drops to 3.8% (Swiftleads AI, 2026).
    • Industry-wide real estate lead conversion sits at just 0.4%–1.2% (JustCall, 2026) — a structured sequence is the difference between top producer and average.
    • Clarksville TN homes averaged a $353,000 sale price and 47 days on market in April 2026 (JKim Realty MLS report, 2026) — buyers are deliberate and shoppable for weeks.
    • 91% of sellers used an agent in 2025 (NAR, 2025); your open house visitors are tomorrow’s listing leads too.
    • PCS-to-Fort-Campbell buyers start searching 90–120 days before report date (Mil Housing Network, 2026) — your follow-up window is long, but only if you stay top of mind.
    • Run the 7-touch, 30-day sequence below and pair every buyer with a Clarksville TN mortgage lender for fast pre-approval.

    Why Open House Follow-Up Is Broken for Most Clarksville Realtors

    An open house follow-up sequence is a planned, multi-channel series of messages — call, text, email, social, mail — sent to every visitor after they sign in, designed to move them from curious looker to qualified buyer. Most Clarksville TN realtors send one email the next day and call it a sequence. That is not a sequence; it is a wave goodbye. Industry-wide real estate lead conversion averages just 0.4%–1.2% (JustCall, 2026) precisely because most agents stop after one or two touches.

    The Clarksville housing market makes this even more painful. With 47 days on market and 2,012 active listings in April 2026 (JKim Realty, 2026), buyers have time to keep shopping — and they will, with whichever Clarksville real estate agent stays in front of them. A first-time homebuyer Clarksville visitor at your Sunday open house is talking to two other agents by Wednesday unless you have already moved them into a real sequence.

    What Is the ’60-Second Rule’ and Why Does It Matter?

    The 60-second rule is the principle that the first voice contact attempt to a new lead should happen within 60 seconds of the lead being captured. Leads contacted by voice within 60 seconds convert to booked appointments at 27.1%, dropping to 14.6% at 5 minutes and 3.8% at 30+ minutes (Swiftleads AI, 2026). For open houses, ’60 seconds’ means a text or call before they pull out of the driveway. Set up your sign-in tool to auto-trigger a text the moment a visitor enters their phone number.

    The 7 Follow-Up Sequences That Convert Open House Visitors

    Sequence 1 — The 60-Second Text (Day 0, while they’re still on the block)

    Before the visitor reaches their car, send: ‘Hi [Name] — Kate Matties-Deiboldt with VanDyk Mortgage here on behalf of the listing agent. Loved meeting you at 123 Main today. If you want a quick payment estimate or to know what you’d qualify for, text me back — takes 5 minutes. NMLS #18487.’ One in four people respond. That’s a real-time mortgage pre-approval Clarksville conversation you couldn’t have any other way.

    Sequence 2 — The Same-Night Personalized Email (Day 0, evening)

    One short paragraph. Mention something specific from your conversation — the bonus room, the school district, the BAH stretch they were doing the math on. Attach a one-pager on the home, a list of three comparable listings nearby, and a soft CTA: ‘Want me to set up showings on any of these this week?’

    Sequence 3 — The Loan-Ready Call (Day 2)

    A scheduled voice call. Goal: shift them from ‘looking’ to ‘talking to a lender.’ Half of Clarksville buyers near Fort Campbell qualify for a VA loan. A VA loan is a mortgage backed by the U.S. Department of Veterans Affairs that allows eligible service members, veterans, and surviving spouses to buy a home with no down payment (VA.gov). If you sense military, hand them to a Fort Campbell VA loan specialist by Day 2 — not Day 22. [INTERNAL LINK: VA Loans Demystified for Realtors]

    Sequence 4 — The ‘Just Listed / Just Sold’ Text (Day 5)

    Send one curated comp from their area or price range. No pitch. Just: ‘Saw this hit the market this morning in [neighborhood]. Thought of you — three bed, big yard, walking distance to Rossview. Want a tour?’ This works for first-time homebuyer Clarksville and PCS to Fort Campbell leads equally well.

    Sequence 5 — The Value-Add Email (Day 10)

    Drop one piece of education they actually need — a Clarksville housing market update, a THDA first-time buyer eligibility checklist, the difference between FHA and conventional, or a Montgomery County TN homes inventory snapshot. Include one image, one chart, one sentence CTA.

    Sequence 6 — The Phone Check-In (Day 17)

    Two weeks after the open house, call. Not ‘are you still looking?’ — too easy to say no. Try: ‘Hey, two homes hit in the school zone you liked this weekend, wanted to make sure you saw them before they moved fast.’

    Sequence 7 — The 30-Day Decision Touch (Day 30)

    By now you know if they are buying. A final call or in-person coffee. If they’re a 30–60 day buyer, lock in a buyer agency agreement and a hard mortgage pre-approval Clarksville. If they’re 6+ months out, drop them into your monthly newsletter and quarterly check-in cadence.

    Open House Follow-Up Sequence at a Glance

    Day Channel Goal Conversion Lever
    Day 0 (60 sec) SMS Catch them warm Speed (27.1% conversion vs 3.8% at 30 min)
    Day 0 (PM) Email Reinforce rapport Personalization + comps
    Day 2 Call Move to pre-approval Lender intro
    Day 5 SMS Stay top-of-mind Relevant new listing
    Day 10 Email Educate + qualify Value content (VA / THDA / USDA)
    Day 17 Call Force a status check Specific listing reference
    Day 30 Call / coffee Close or nurture Decision conversation

    How This Plays in the Current Clarksville Housing Market

    The Clarksville housing market in spring 2026 is balanced — median sale prices between $308,000 and $325,000 depending on the source, listing prices around $345,000, and 48 median days on market with sale-to-list ratios near 100% (Chord Real Estate, 2026). That is the perfect environment for a disciplined follow-up sequence: buyers are shopping for weeks, not minutes, and the agent who stays in front of them wins.

    Layer in Fort Campbell. Military relocation Clarksville buyers begin home searches 90–120 days before their report date (Mil Housing Network, 2026) — meaning a PCS visitor who walks into your June open house may not close until late September. A 30-day sequence that flows into a monthly nurture cadence is exactly what captures that buyer. Pair every PCS lead with a Fort Campbell VA loan specialist on Day 2 so you can write offers the moment they find the right home. [INTERNAL LINK: Building a Move to Clarksville Relocation Funnel]

    How This Plugs Into the Mortgage Side

    A great open house follow-up sequence falls apart at the offer stage if the buyer is not mortgage-ready. The fastest path to a closed Clarksville deal is a co-marketed open house: realtor at the door, lender in the kitchen, both names on the sign-in QR code. Visitors who walk out with a Clarksville TN mortgage lender already in their phone are 2–3x more likely to come back with an offer. [INTERNAL LINK: Pre-Approval Partnership: Why Co-Marketing With a Local Lender Doubles Your Lead Flow]

    At The Blue Note Home, we work with Middle Tennessee mortgage realtors who treat their open house sign-in sheet as the front door to a 30-day system — not a Sunday-afternoon novelty. Every visitor gets the 7-touch sequence above, every military buyer gets a VA loan eligibility Tennessee conversation by Day 2, and every first-time buyer hears about THDA first-time buyer and USDA loans Tennessee programs by Day 10.

    FAQ — Open House Follow-Up for Clarksville Realtors

    How fast should I follow up after an open house?

    The first contact attempt — ideally a personalized text — should happen within 60 seconds of the visitor signing in. Voice contact within 60 seconds converts 27.1% of leads to appointments versus 3.8% at 30+ minutes (Swiftleads AI, 2026).

    What is the best follow-up sequence length for open houses?

    Seven touches across 30 days, mixing SMS, email, and voice. After Day 30, drop unconverted leads into a monthly nurture sequence — many Clarksville buyers (especially PCS to Fort Campbell families) shop for 90–120 days before they buy.

    Should I text or email open house visitors first?

    Text first, then email. SMS open rates are 90%+ and response rates within five minutes are dramatically higher than email. Send the email same day as a longer-form follow-up with comparable listings attached.

    How do I get more open house visitors to give a real phone number?

    Use a digital sign-in (tablet or QR code) that says ‘By signing in you agree to a quick text confirming your visit.’ Confirmation framing dramatically reduces fake numbers compared to a paper clipboard.

    How do I follow up with PCS-to-Fort-Campbell buyers differently?

    Move slower on showings but faster on lender introduction. PCS buyers often start 90–120 days before report date, so they need a Fort Campbell VA loan specialist relationship before they need a tour list. Send a short VA loan eligibility Tennessee primer in Sequence 5 and offer a virtual home tour option.

    What CRM should a Clarksville TN realtor use for open house sequences?

    Any CRM that supports SMS automation, email cadences, and trigger-based workflows (Follow Up Boss, Lofty, kvCORE, Sierra Interactive, or even HubSpot Free). The CRM matters less than actually running the seven touches.


    About the author: Kate Matties-Deiboldt (NMLS #18487) is a licensed mortgage loan originator with VanDyk Mortgage based in Clarksville, TN, specializing in VA loans, FHA, USDA, and first-time homebuyer programs across Middle Tennessee and Kentucky. She publishes at The Blue Note Home.

    {“@context”:”https://schema.org&#8221;,”@graph”:[{“@type”:”Article”,”@id”:”https://thedealdoctor.blog/open-house-follow-up-sequences-clarksville-realtors/#article&#8221;,”headline”:”Open House Follow-Up Sequences for Clarksville Realtors”,”description”:”A 7-touch, 30-day open house follow-up playbook for Clarksville TN realtors — backed by 2025-2026 NAR and lead-response data.”,”image”:”https://thedealdoctor.blog/wp-content/uploads/2026/05/open-house-follow-up-clarksville.jpg&#8221;,”datePublished”:”2026-05-17″,”dateModified”:”2026-05-17″,”author”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”,”jobTitle”:”Mortgage Loan Originator (NMLS #18487)”,”worksFor”:{“@type”:”Organization”,”name”:”VanDyk Mortgage”},”url”:”https://thedealdoctor.blog/about&#8221;},”publisher”:{“@type”:”Organization”,”@id”:”https://thedealdoctor.blog/#org&#8221;,”name”:”The Blue Note Home”,”logo”:{“@type”:”ImageObject”,”url”:”https://thedealdoctor.blog/wp-content/uploads/logo.png&#8221;}},”mainEntityOfPage”:{“@type”:”WebPage”,”@id”:”https://thedealdoctor.blog/open-house-follow-up-sequences-clarksville-realtors/&#8221;},”keywords”:”Clarksville real estate agent, open house follow-up, VA loans Clarksville TN, Fort Campbell VA loan specialist, mortgage pre-approval Clarksville, Clarksville housing market, first-time homebuyer Clarksville, military relocation Clarksville, Clarksville TN mortgage lender, Middle Tennessee mortgage”},{“@type”:”FAQPage”,”mainEntity”:[{“@type”:”Question”,”name”:”How fast should I follow up after an open house?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”The first contact attempt should happen within 60 seconds. Voice contact within 60 seconds converts 27.1% of leads to appointments versus 3.8% at 30+ minutes (Swiftleads AI, 2026).”}},{“@type”:”Question”,”name”:”What is the best follow-up sequence length for open houses?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Seven touches across 30 days, mixing SMS, email, and voice. After Day 30, drop unconverted leads into a monthly nurture sequence.”}},{“@type”:”Question”,”name”:”Should I text or email open house visitors first?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Text first, then email. SMS open rates exceed 90% and same-hour response rates are dramatically higher than email.”}},{“@type”:”Question”,”name”:”How do I get more open house visitors to give a real phone number?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Use a digital sign-in tablet or QR code with confirmation framing: By signing in you agree to a quick text confirming your visit.”}},{“@type”:”Question”,”name”:”How do I follow up with PCS-to-Fort-Campbell buyers differently?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Move slower on showings but faster on lender introduction. PCS buyers often start 90-120 days before report date, so they need a Fort Campbell VA loan specialist relationship before they need a tour list.”}},{“@type”:”Question”,”name”:”What CRM should a Clarksville TN realtor use for open house sequences?”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Any CRM that supports SMS automation, email cadences, and trigger workflows — Follow Up Boss, Lofty, kvCORE, Sierra Interactive, or HubSpot Free all work.”}}]},{“@type”:”BreadcrumbList”,”itemListElement”:[{“@type”:”ListItem”,”position”:1,”name”:”Home”,”item”:”https://thedealdoctor.blog/&#8221;},{“@type”:”ListItem”,”position”:2,”name”:”Marketing Tips”,”item”:”https://thedealdoctor.blog/category/marketing-tips/&#8221;},{“@type”:”ListItem”,”position”:3,”name”:”Open House Follow-Up Sequences”}]},{“@type”:”LocalBusiness”,”@id”:”https://thedealdoctor.blog/#localbusiness&#8221;,”name”:”The Blue Note Home – Kate Matties-Deiboldt, Mortgage Loan Officer”,”description”:”VA loan specialist and mortgage loan originator serving Clarksville TN, Fort Campbell KY, and Middle Tennessee. NMLS #18487.”,”image”:”https://thedealdoctor.blog/wp-content/uploads/logo.png&#8221;,”url”:”https://thedealdoctor.blog&#8221;,”areaServed”:[“Clarksville, TN”,”Fort Campbell, KY”,”Nashville, TN”,”Montgomery County, TN”,”Middle Tennessee”],”address”:{“@type”:”PostalAddress”,”addressLocality”:”Clarksville”,”addressRegion”:”TN”,”addressCountry”:”US”},”founder”:{“@type”:”Person”,”name”:”Kate Matties-Deiboldt”}},{“@type”:”HowTo”,”name”:”7 Open House Follow-Up Sequences That Convert”,”description”:”A 7-step, 30-day open house follow-up playbook for Clarksville TN realtors.”,”step”:[{“@type”:”HowToStep”,”position”:1,”name”:”60-Second Text”,”text”:”Send a personalized SMS within 60 seconds of the visitor signing in.”},{“@type”:”HowToStep”,”position”:2,”name”:”Same-Night Personalized Email”,”text”:”Send a short email referencing something specific from the conversation plus three comparable listings.”},{“@type”:”HowToStep”,”position”:3,”name”:”Loan-Ready Call (Day 2)”,”text”:”Voice call to introduce the buyer to a Clarksville TN mortgage lender or Fort Campbell VA loan specialist.”},{“@type”:”HowToStep”,”position”:4,”name”:”Just Listed Text (Day 5)”,”text”:”Send one curated new listing in their area or price range with a soft tour CTA.”},{“@type”:”HowToStep”,”position”:5,”name”:”Value-Add Email (Day 10)”,”text”:”Send one piece of buyer education: market update, THDA program, or FHA vs conventional comparison.”},{“@type”:”HowToStep”,”position”:6,”name”:”Phone Check-In (Day 17)”,”text”:”Call referencing a specific new listing in a neighborhood they liked.”},{“@type”:”HowToStep”,”position”:7,”name”:”30-Day Decision Touch”,”text”:”Final call or coffee to either close into a buyer agency agreement or drop into long-term nurture.”}]},{“@type”:”SpeakableSpecification”,”cssSelector”:[“.key-takeaways”,”h1 + p”]}]}